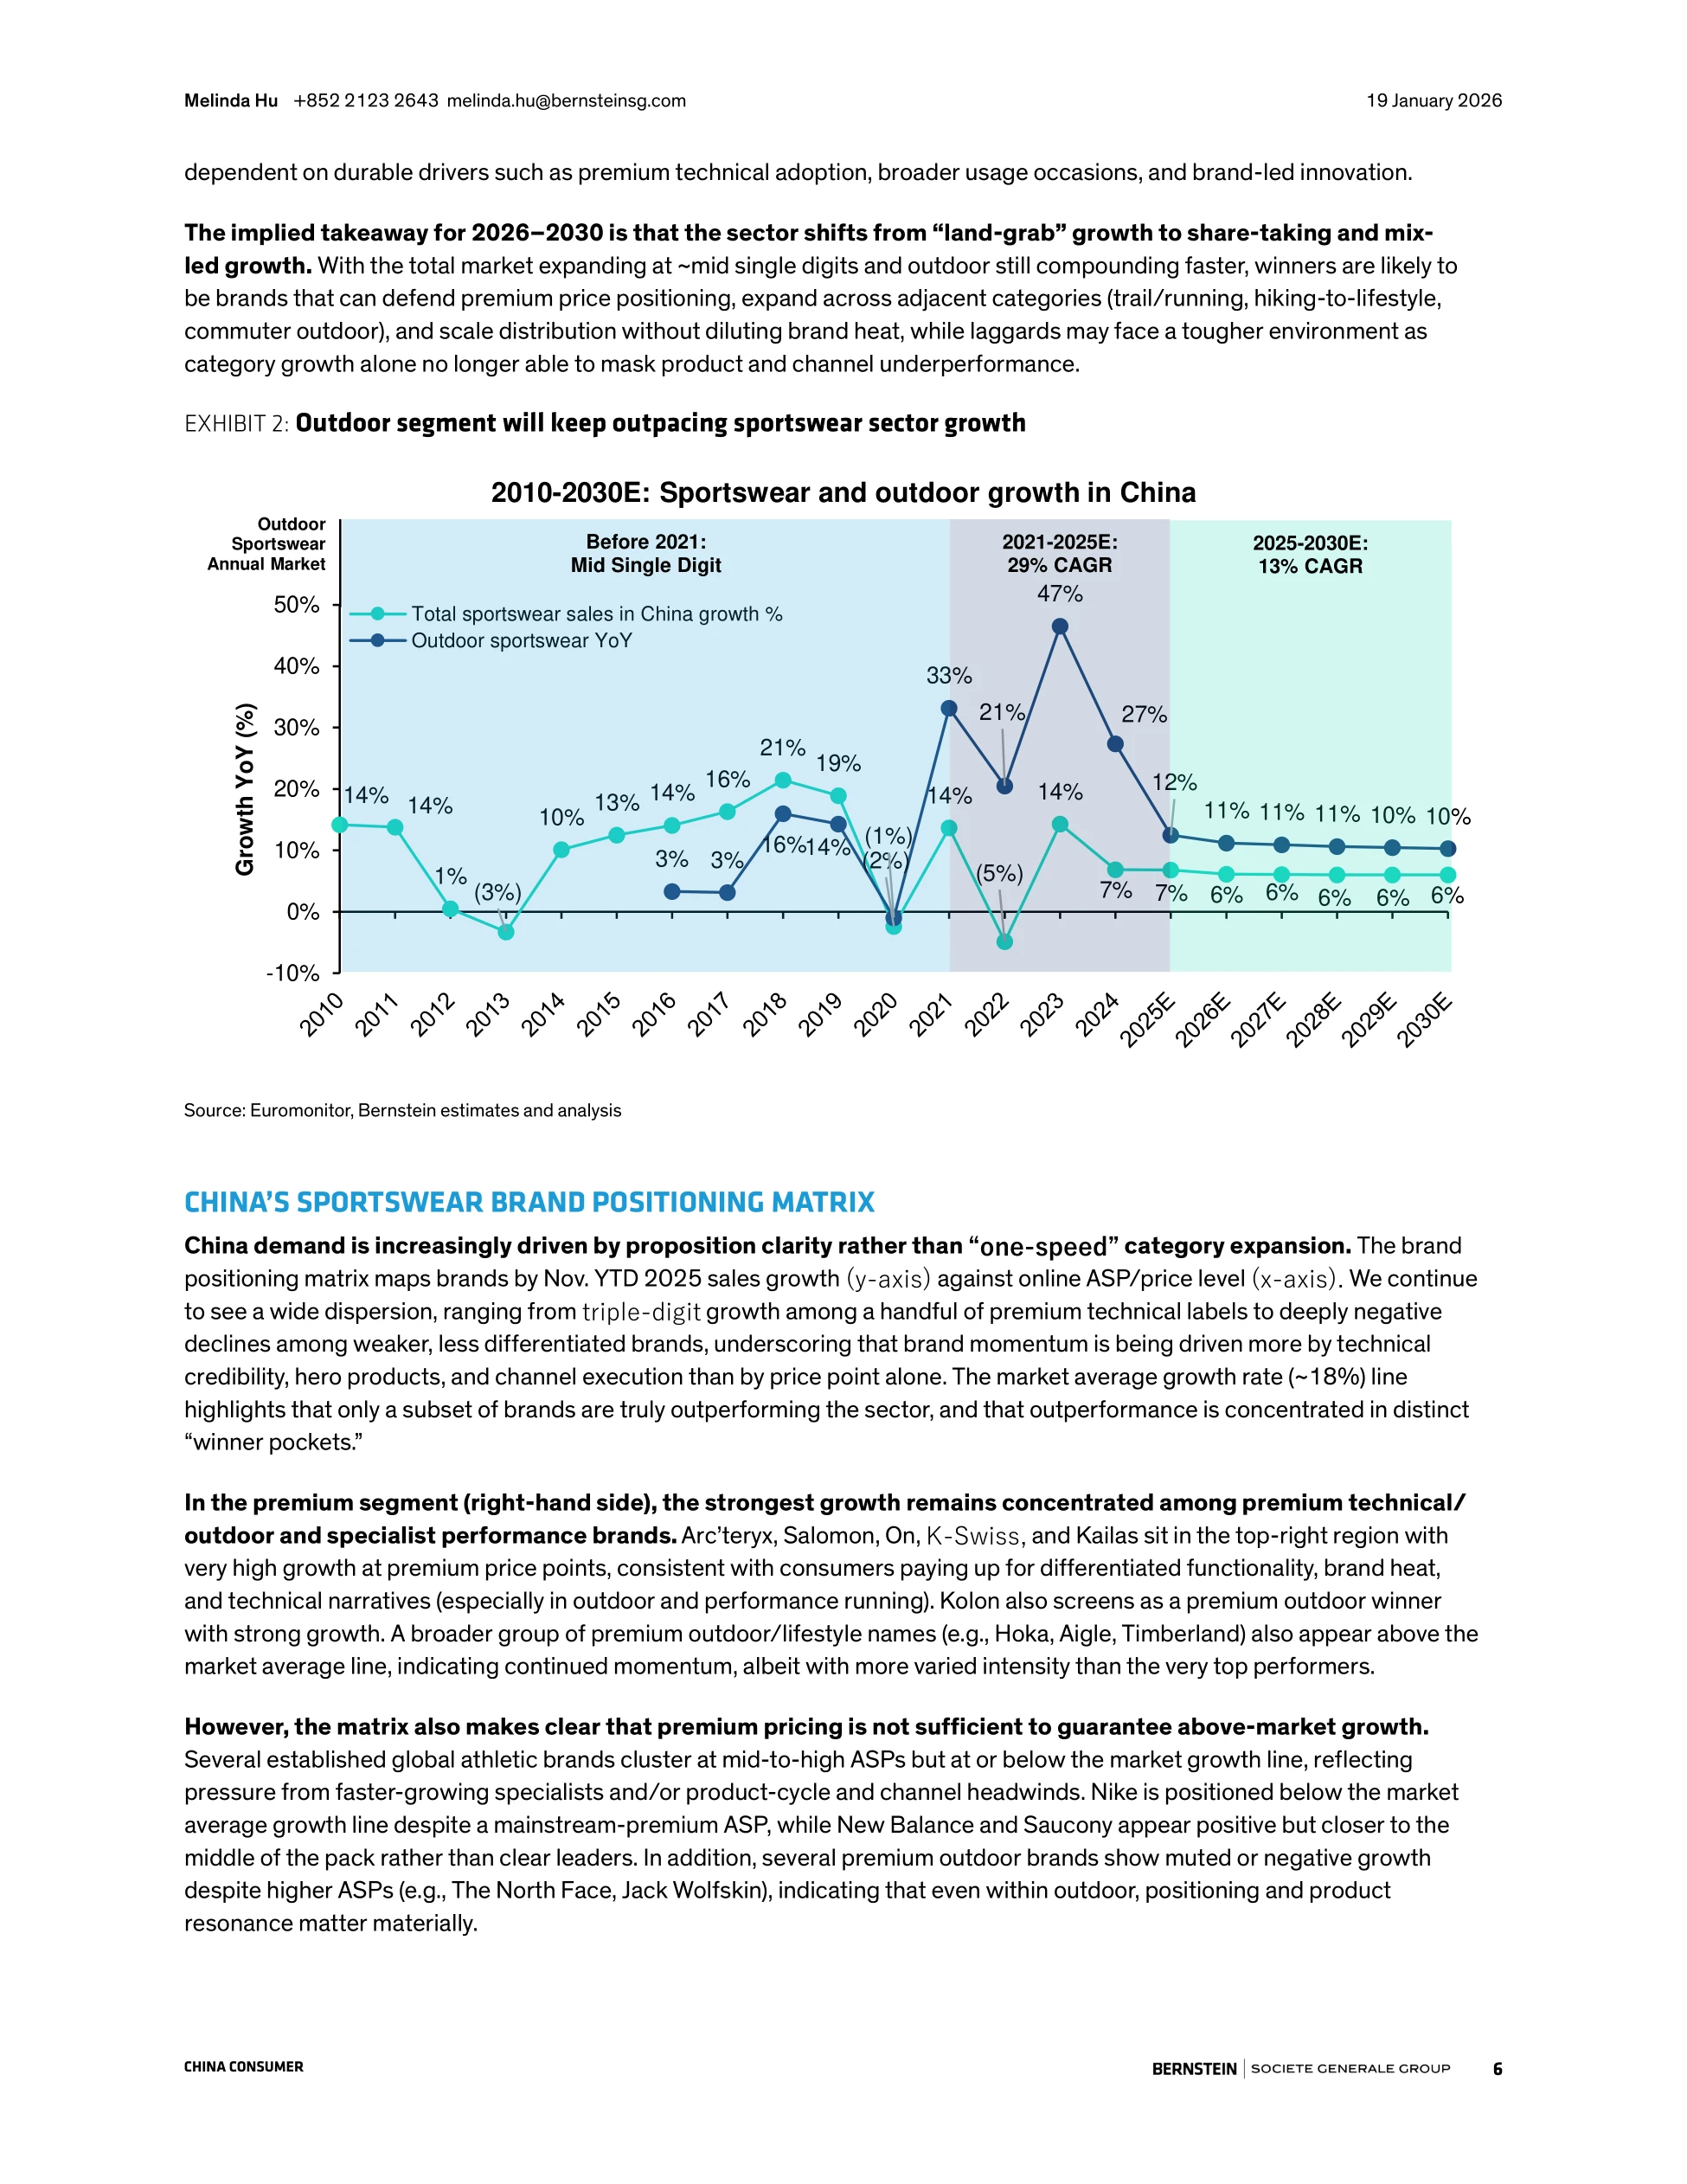
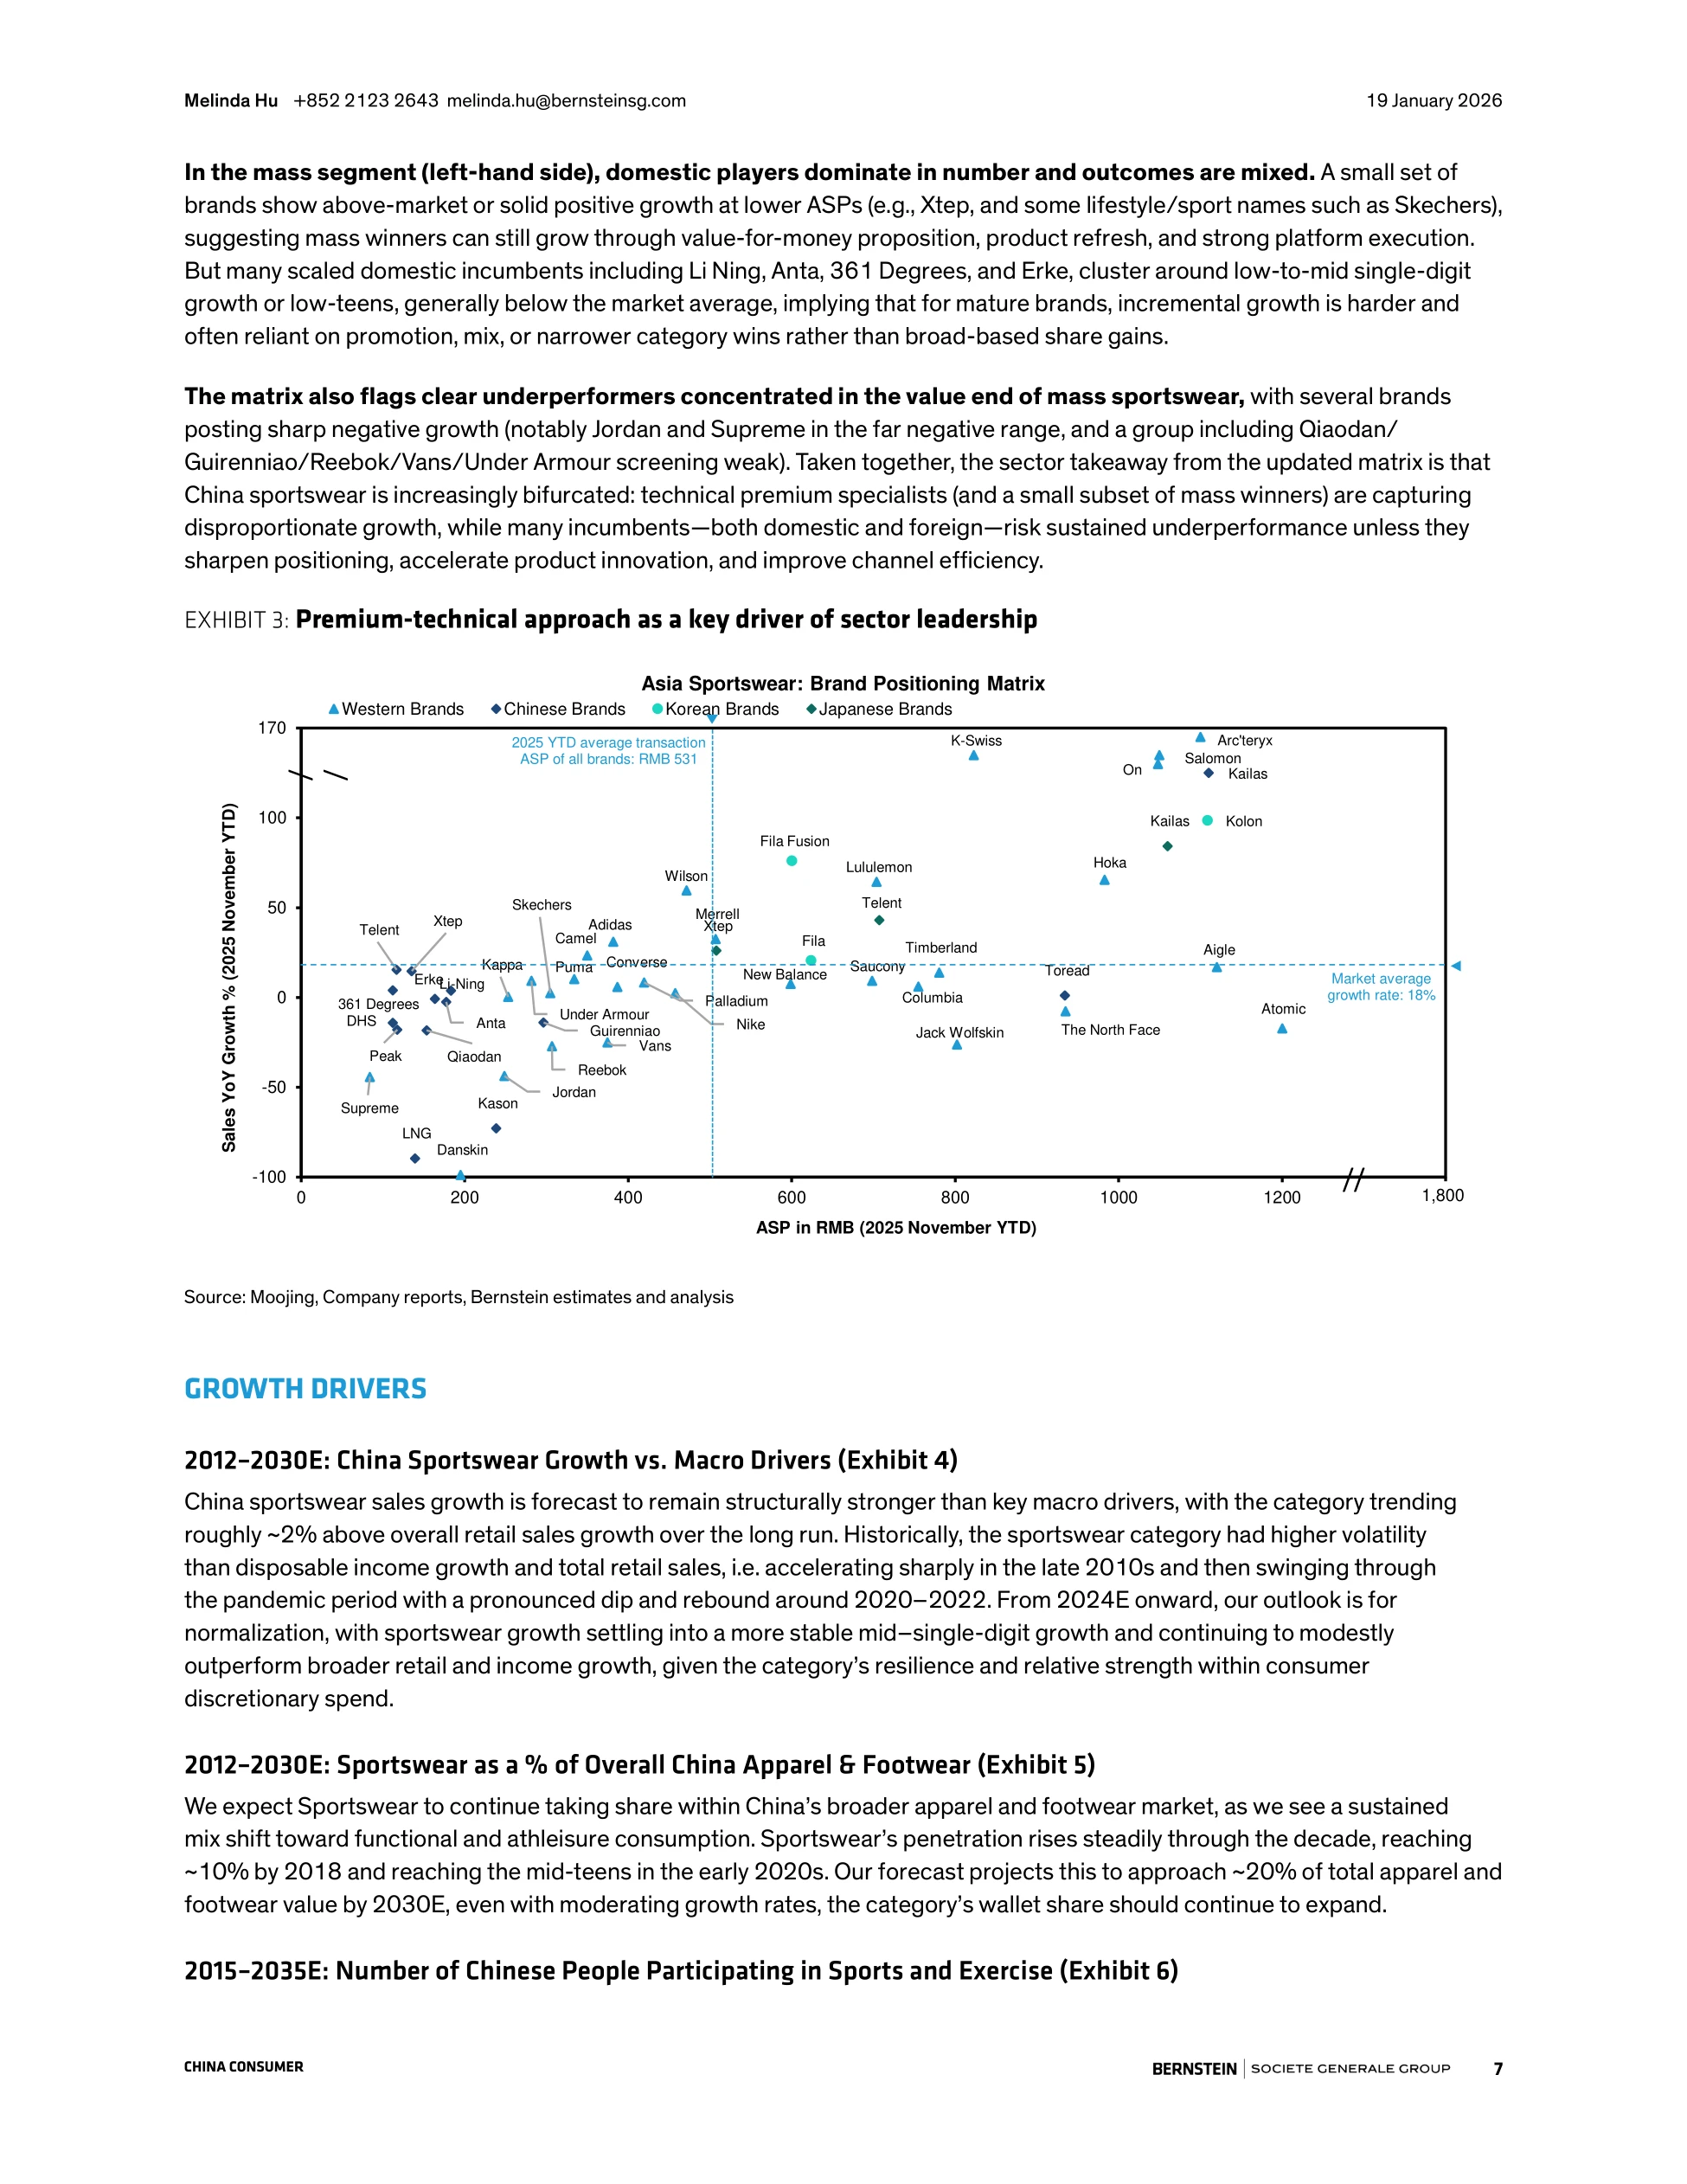
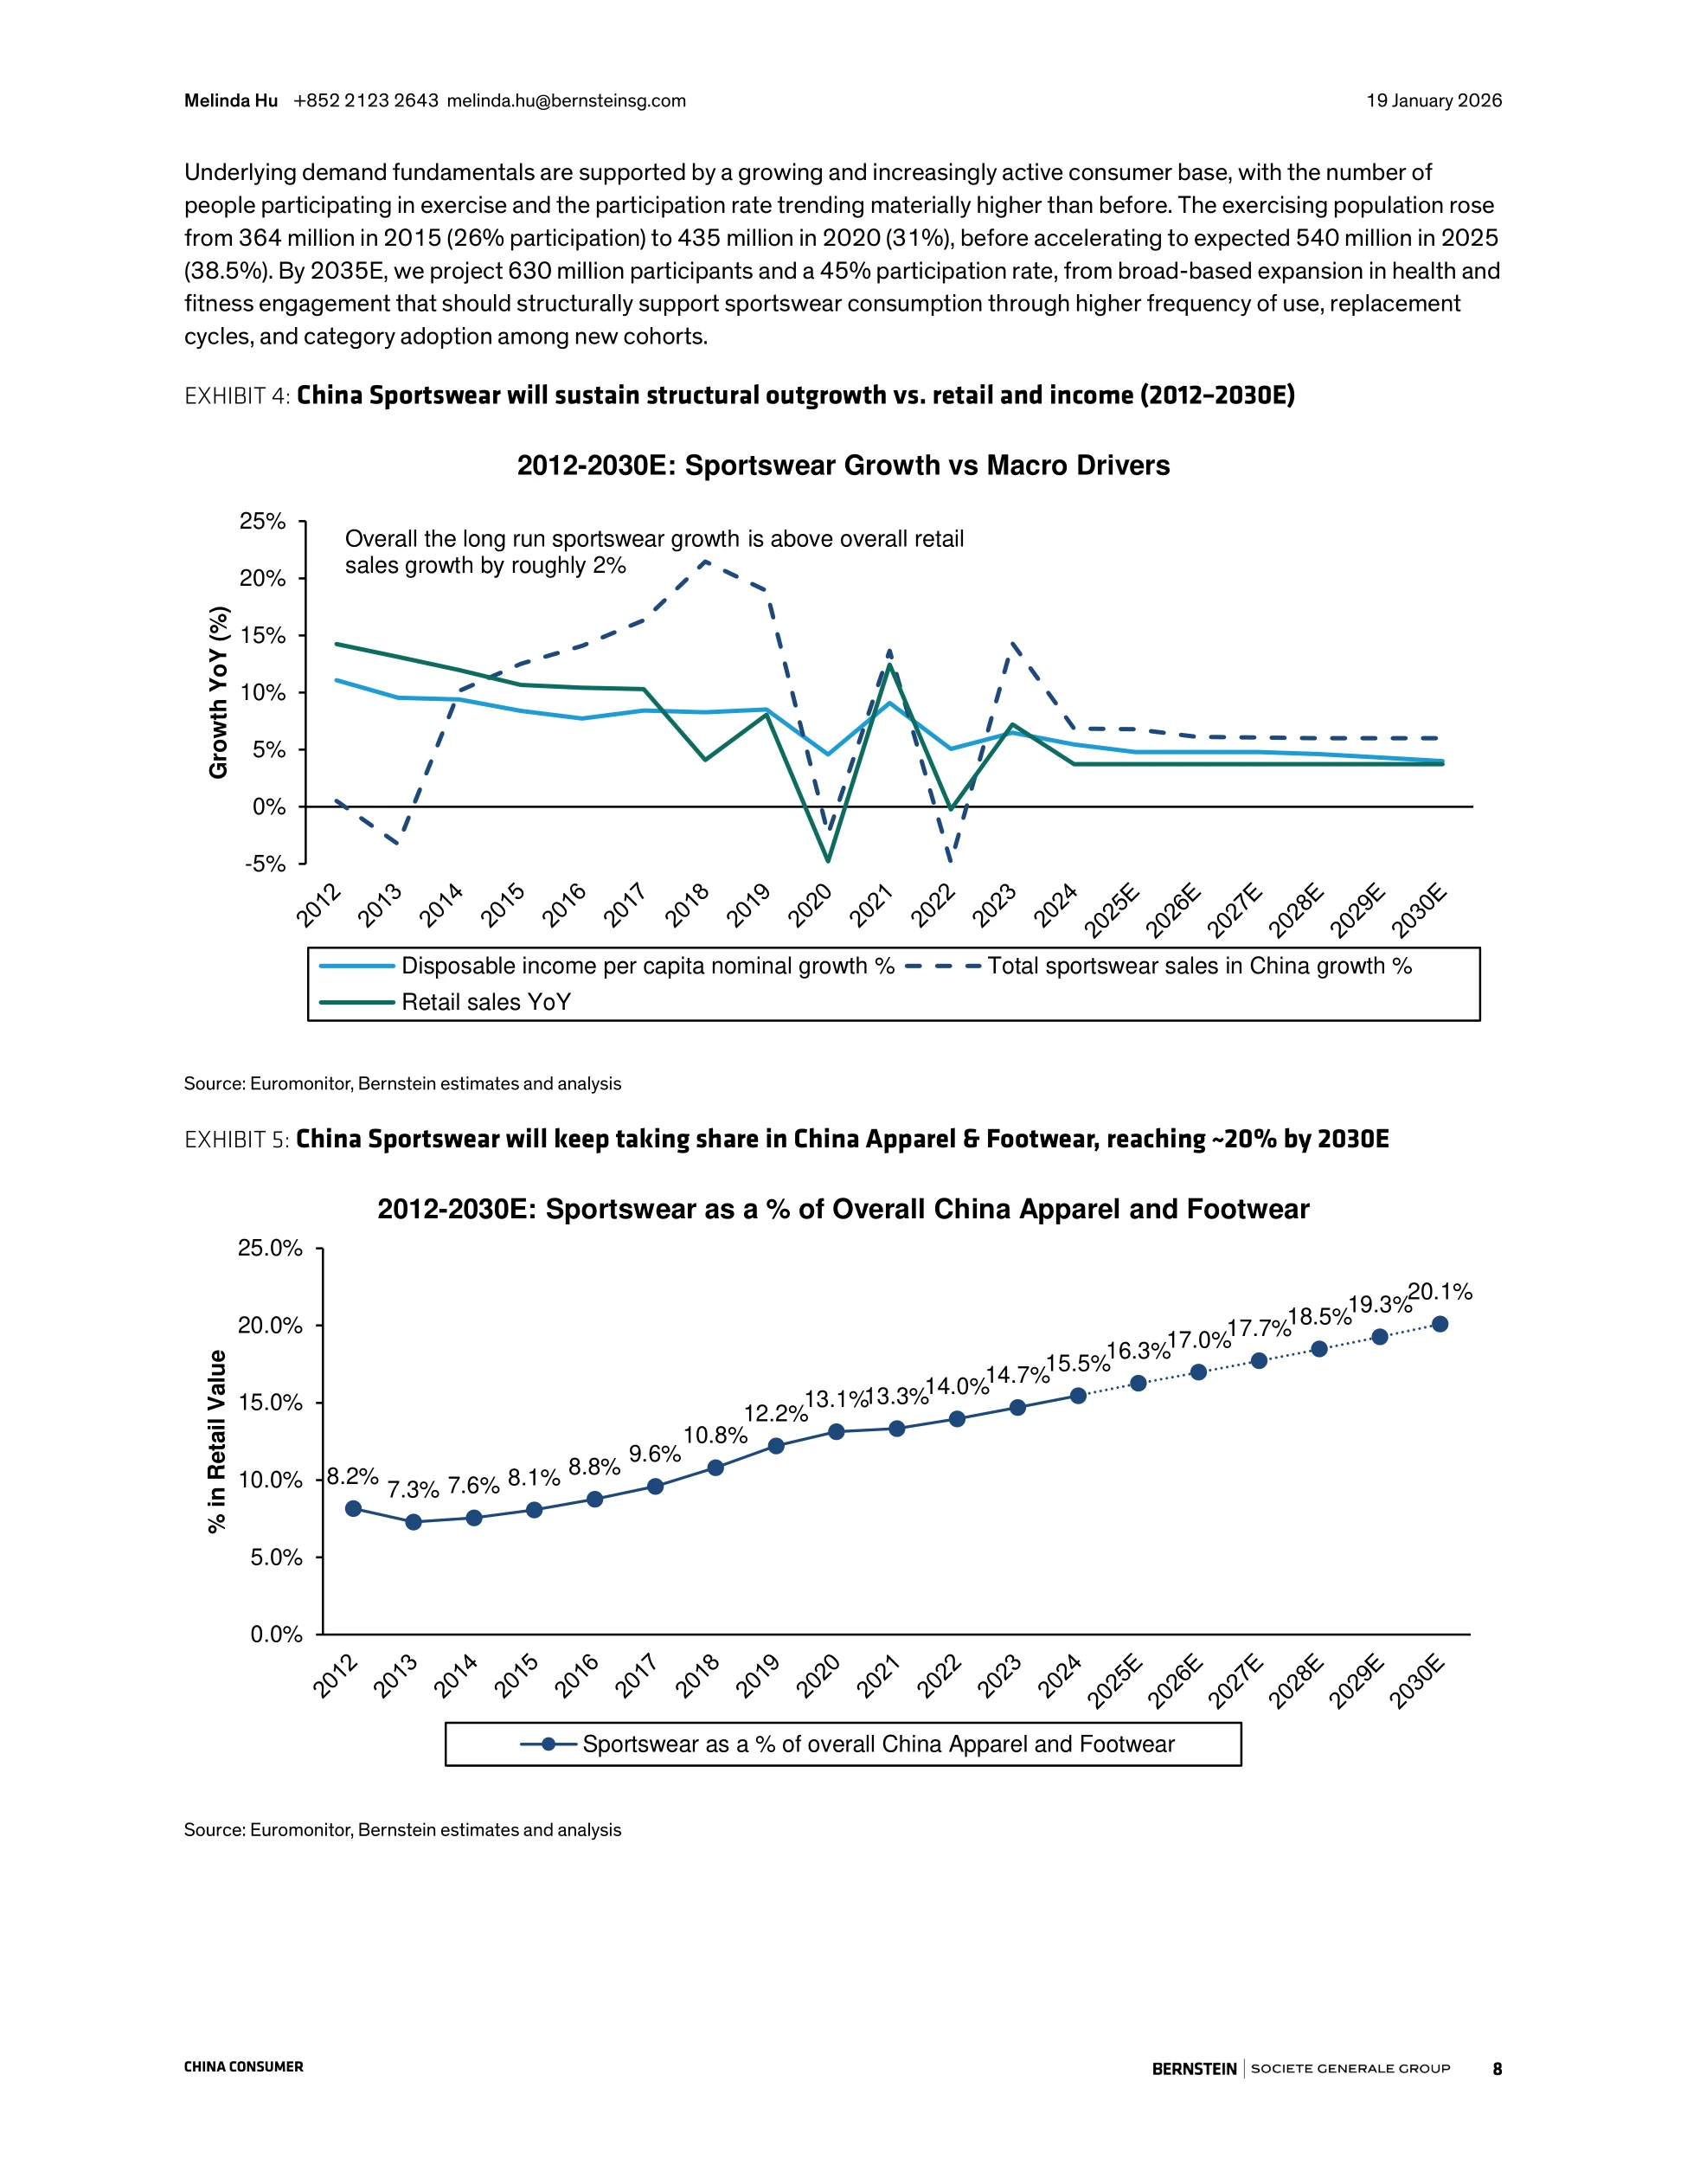
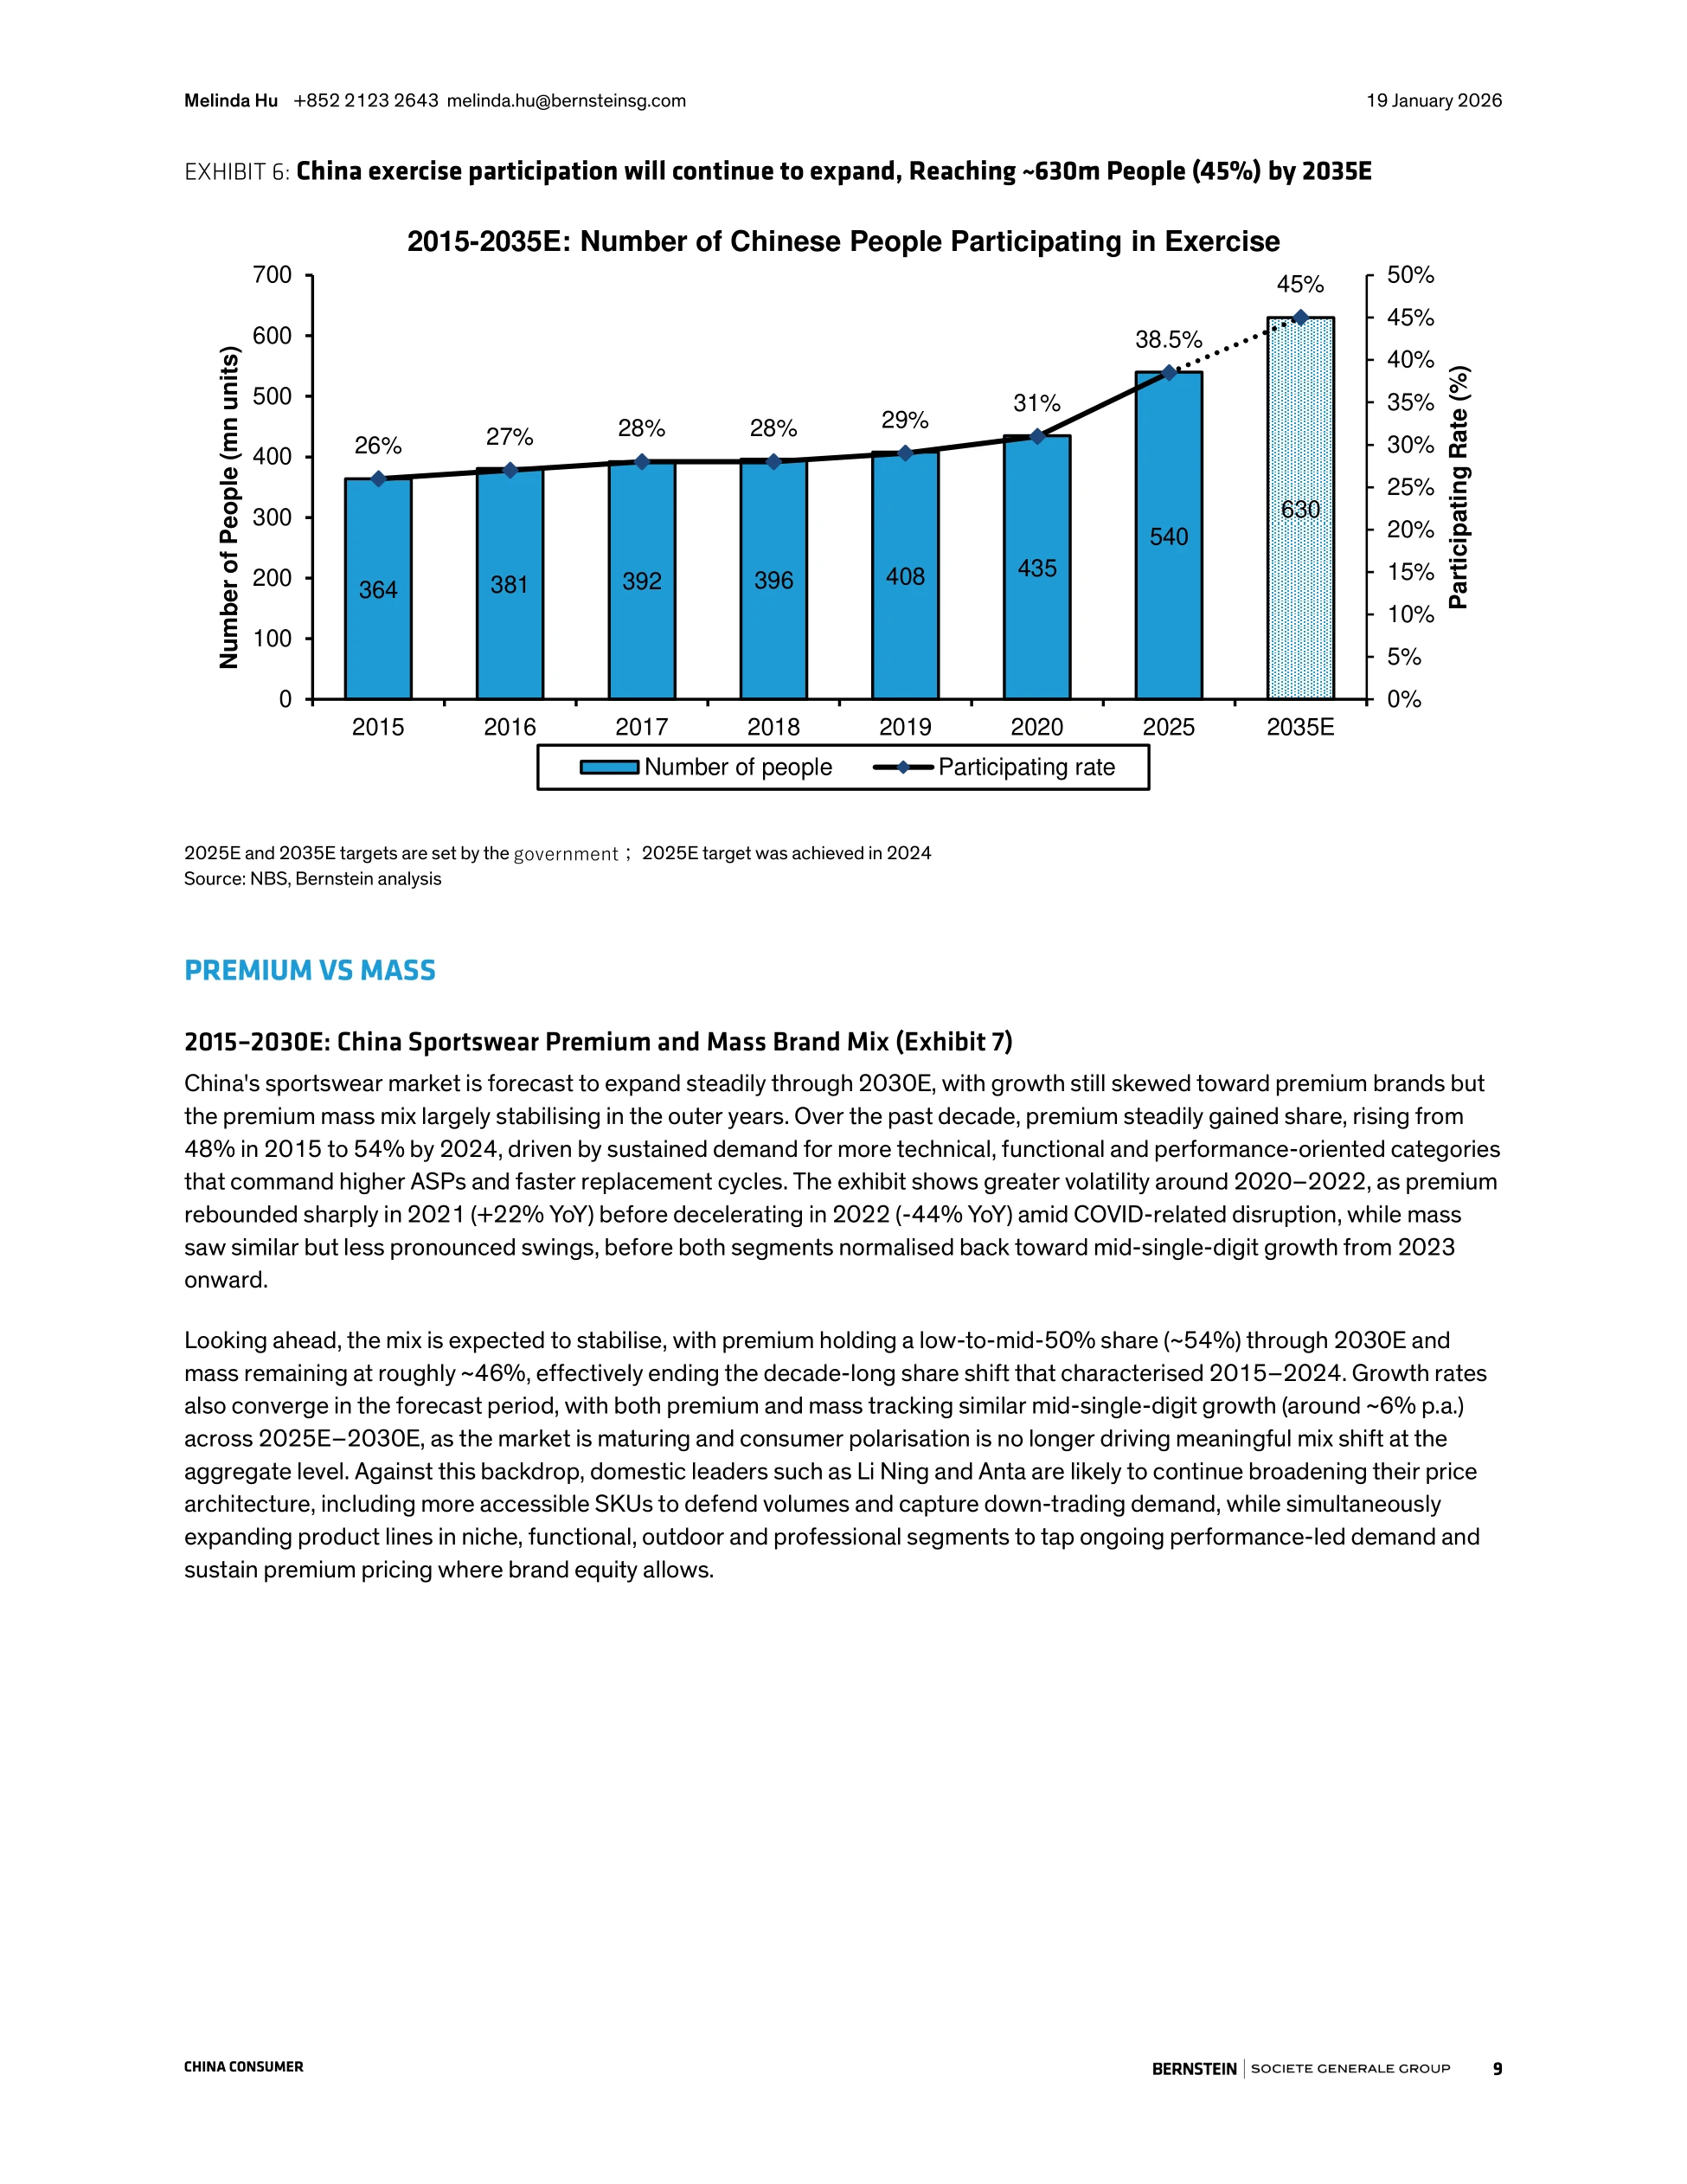
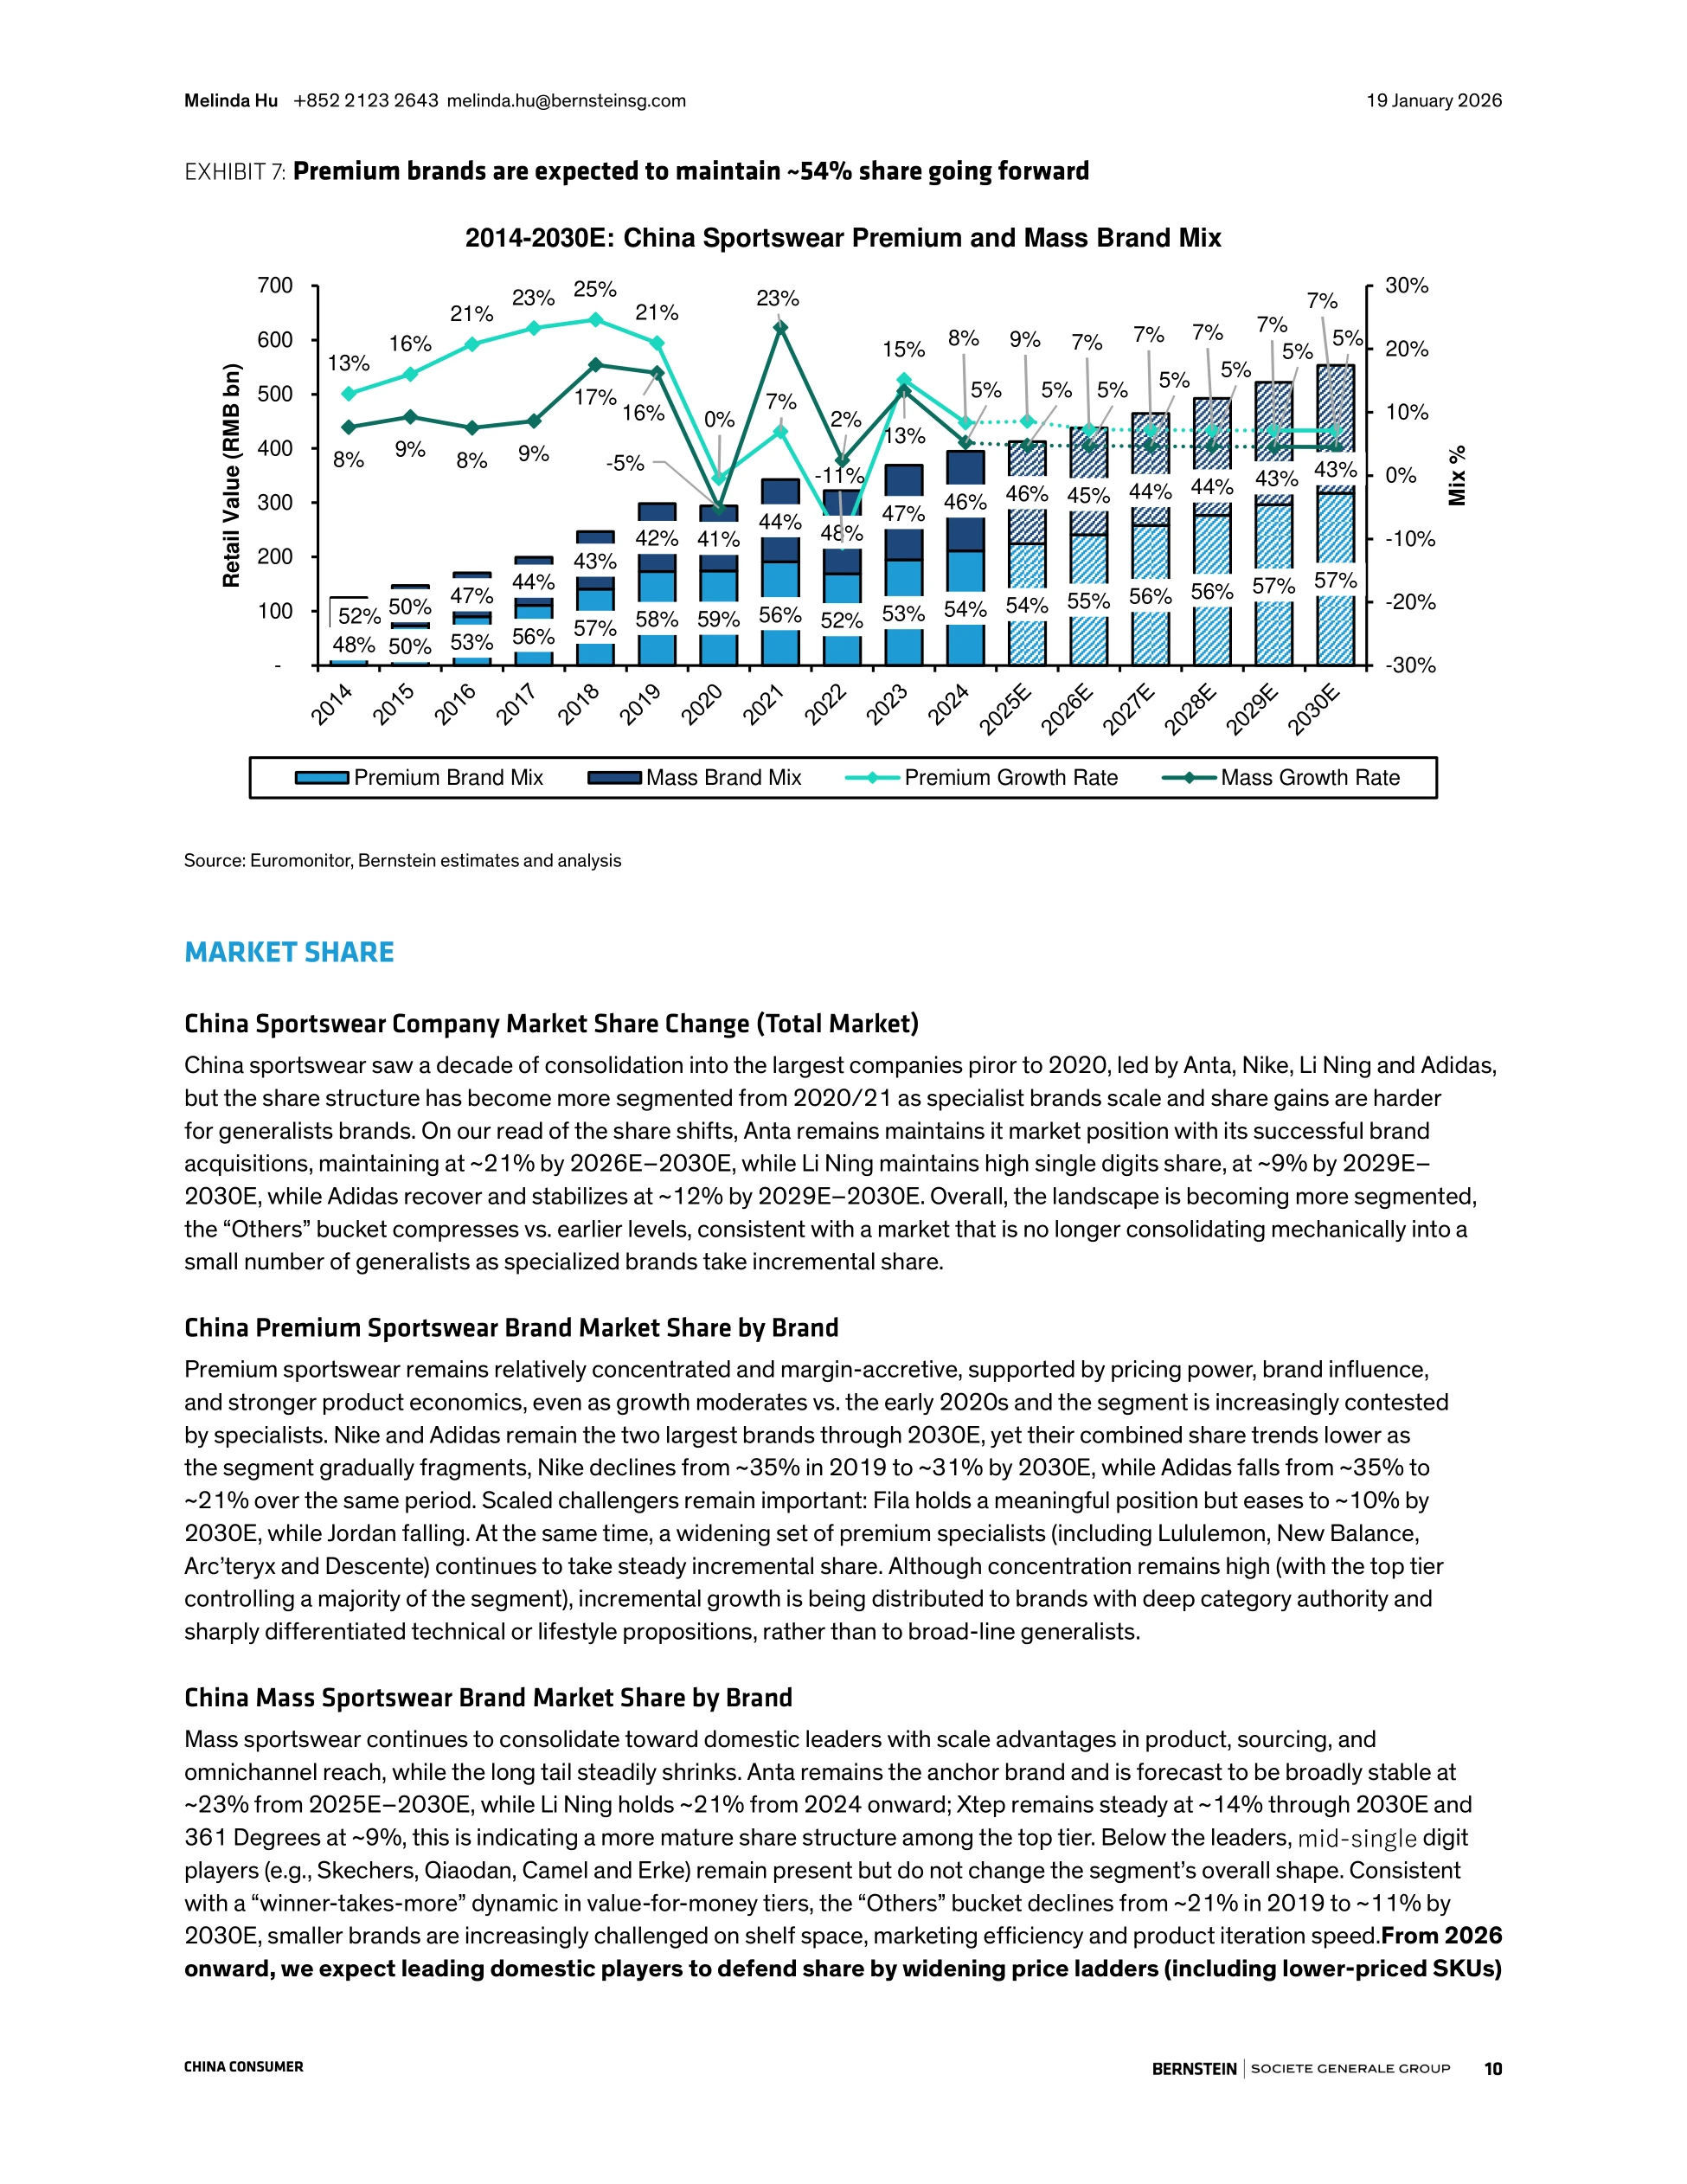
19 January 2026China ConsumerChina Sportswear 2026 Outlook: Outdoor Matures but SpecialistMomentum IntactMelinda Hu+852 2123 2643melinda.hu@bernsteinsg.comKai Zhang+852 2123 2665kai.zhang@bernsteinsg.comFrankie Fong+852 2123 2637frankie.fong@bernsteinsg.comChina's sportswear market is transitioning from high-growth expansion to mature,share-taking growth through 2030E, with total market moderating to ~6% CAGRwhile outdoor maintains structural outperformance at ~12% CAGR. The sector isshifting from "land-grab" category penetration to share reallocation and premiumization,with success increasingly dependent on brand differentiation, technical innovation, andchannel efficiency.Outdoor is now the largest category but maturing with growth moderating to+12% YoY from 29% CAGR (2021–2025E), but with sustained brand substitutionas technical specialists take share from generalists. Market players are respondingby broadening price architecture and expanding into niche, functional, and professionalsegments. Apparel leads FY25 category performance at +18% YoY while sneakers grew+14% YoY, indicating healthy growth across all sportswear categories.Technical specialists like Arc'teryx and Salomon are taking share within outdooreven as category growth decelerates, as consumers shift toward technical, higher-ASP products. Arc'teryx strengthens to ~20% outdoor share by 2025E (from ~7% in2019), Salomon to ~6%, and Descente to ~18%. Within premium overall, established globalsportswear brands lose share (declining from combined ~70% in 2019 to ~52% by 2030E)to technical and lifestyle specialists including outdoor, running, yoga, and athleisure-focused players. In mass, the competitive landscape is consolidating around four majordomestic brands: Anta (~23%), Li Ning (~21%), Xtep (~14%), and 361 Degrees (~9%),who maintain stable shares through 2030E by leveraging scale advantages, while thefragmented tail of smaller players ("Others") loses significant ground.Brand performance in 2025 is highly polarized (+167% to -99%), as technicalspecialists capture disproportionate growth while many established brandsstagnate or decline. Top performers are concentrated among technical outdoor andrunning specialists: Arc'teryx (+167%), Salomon (+150%), Descente (+84%) deliveringtriple-digit or strong double-digit growth despite premium price points, while severalestablished brands sit at or below the ~18% market average growth line. Premiumpositioning alone is insufficient, success depends on positioning through continuousinnovation, expanding across adjacent categories (trail running, hiking-to-lifestyle), andscaling distribution without diluting brand equity.In mass, outcomes are bifurcated between a small set of winners executing onvalue-for-money and widespread underperformance among scaled incumbents.A handful of brands (Xtep, Skechers) show solid growth through sharp propositions andplatform execution, while many scaled domestic players (Anta, Li Ning...