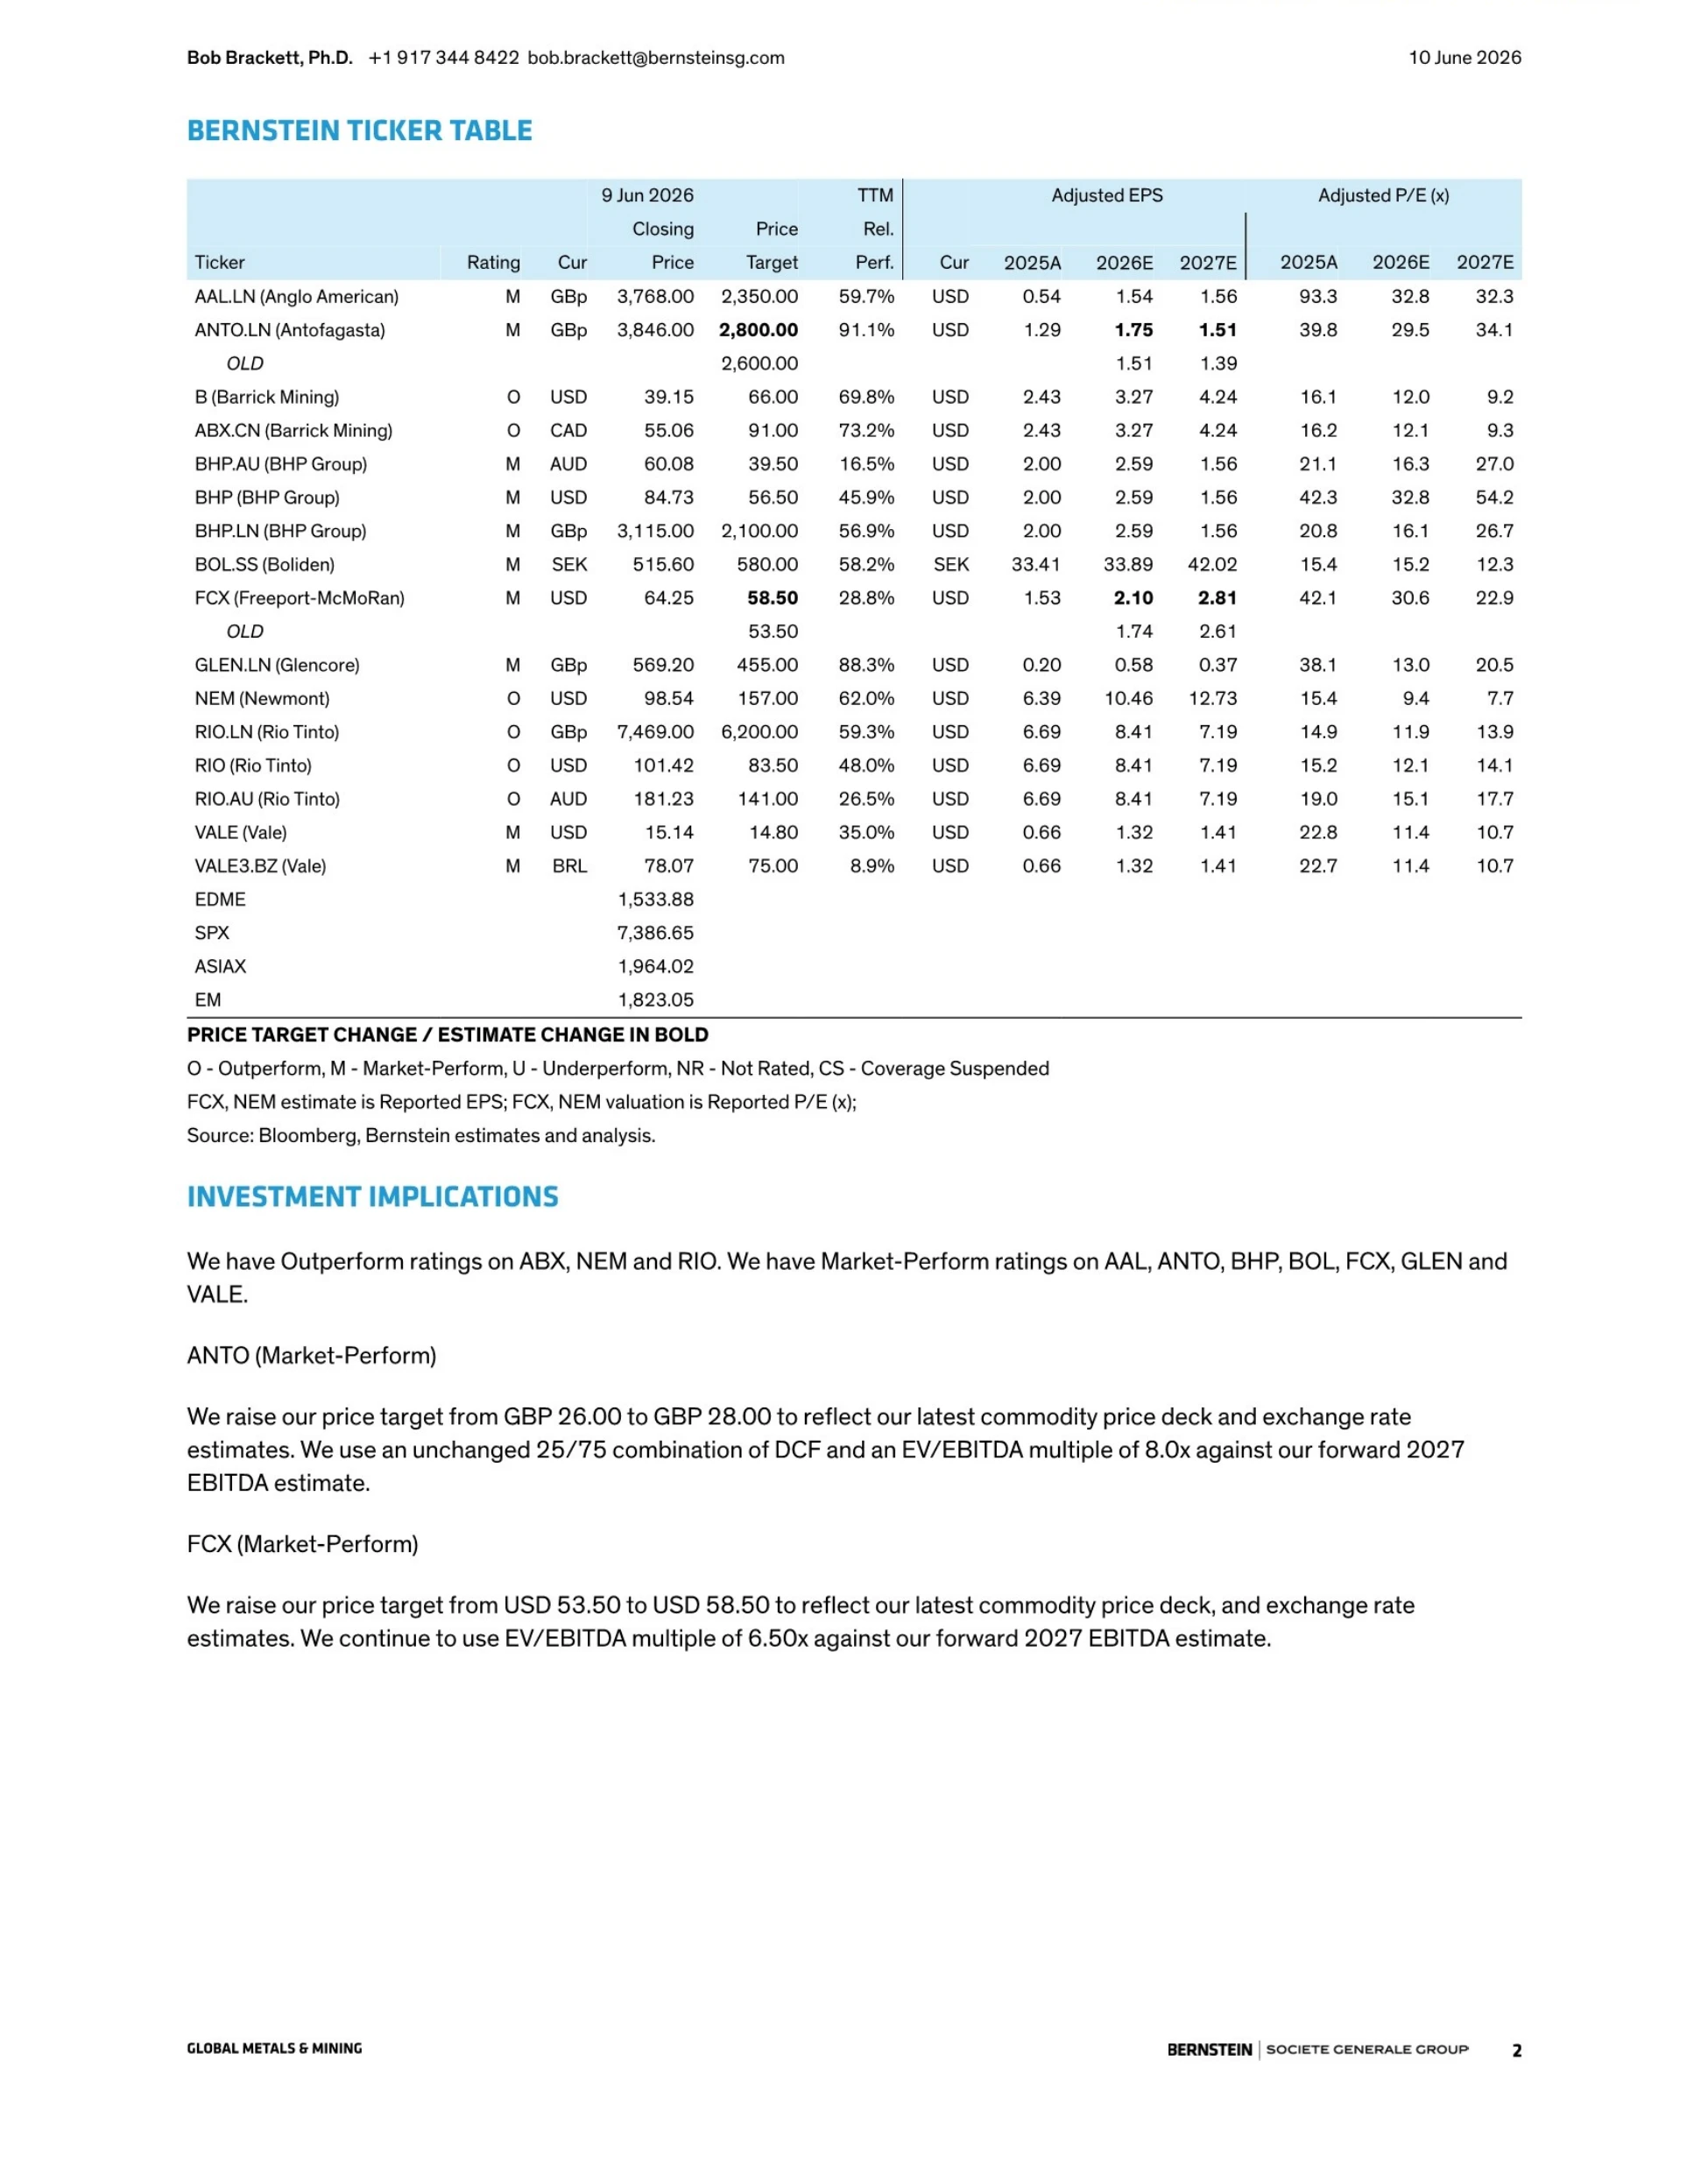
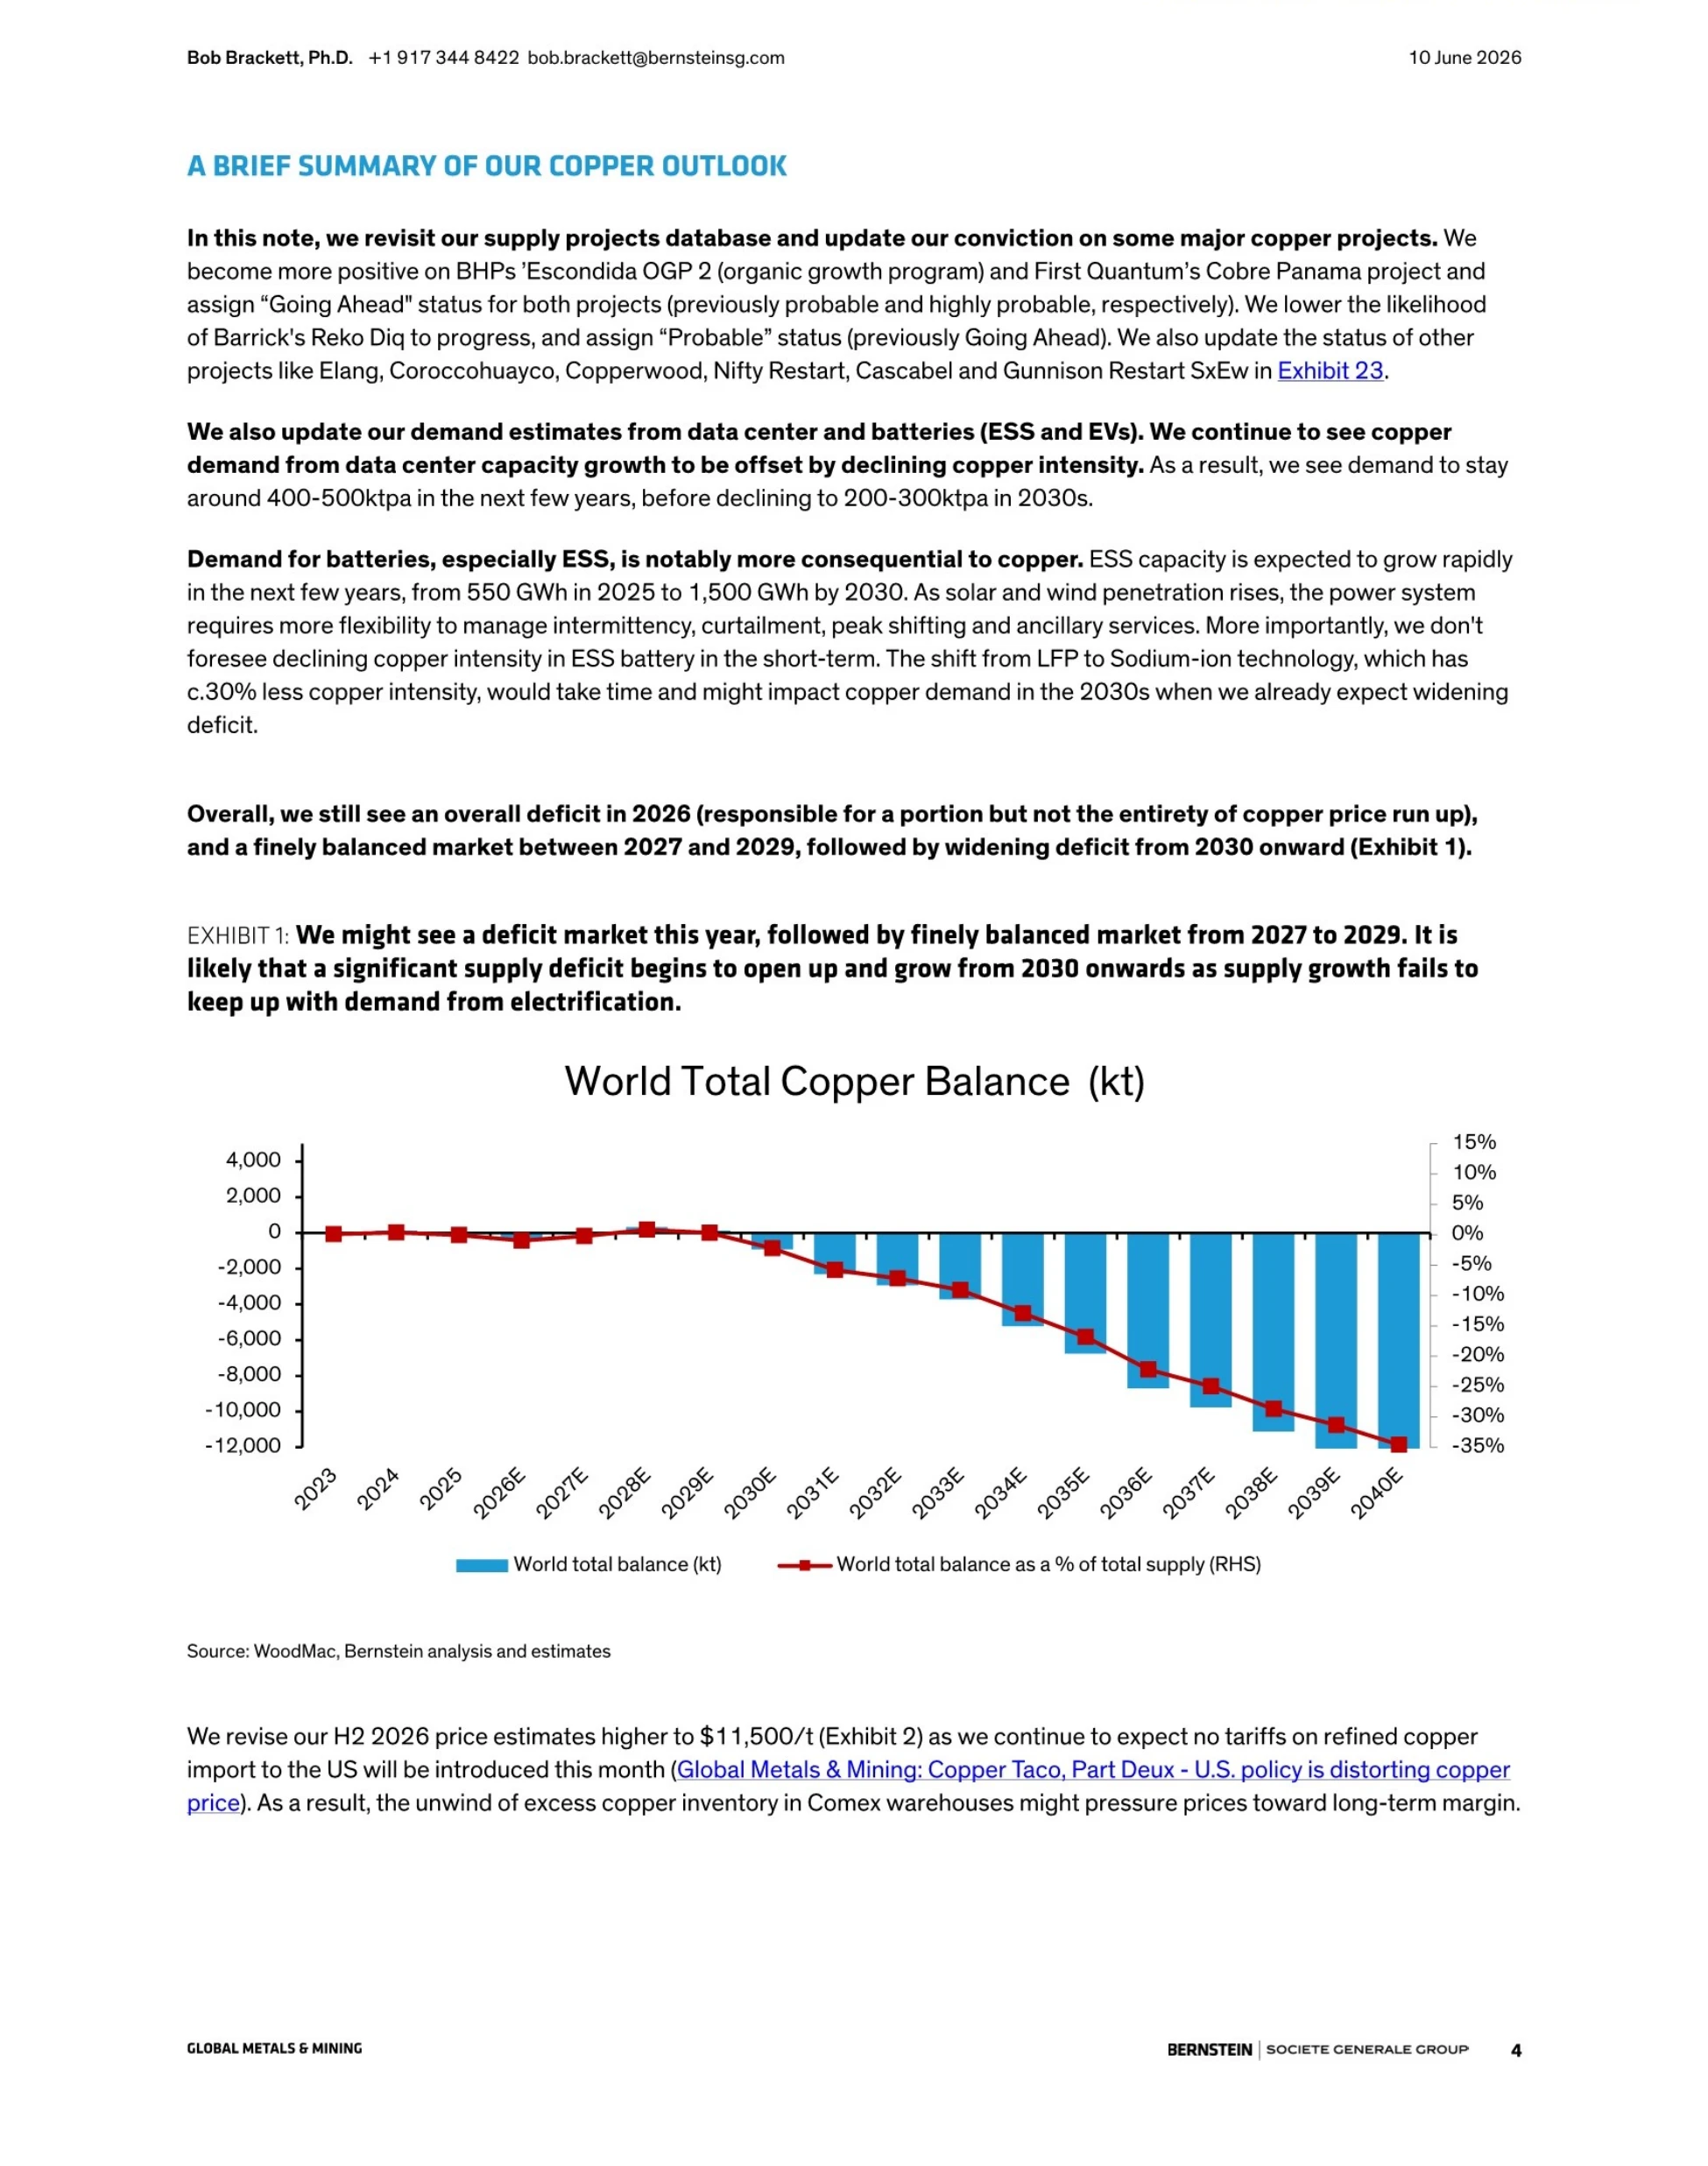
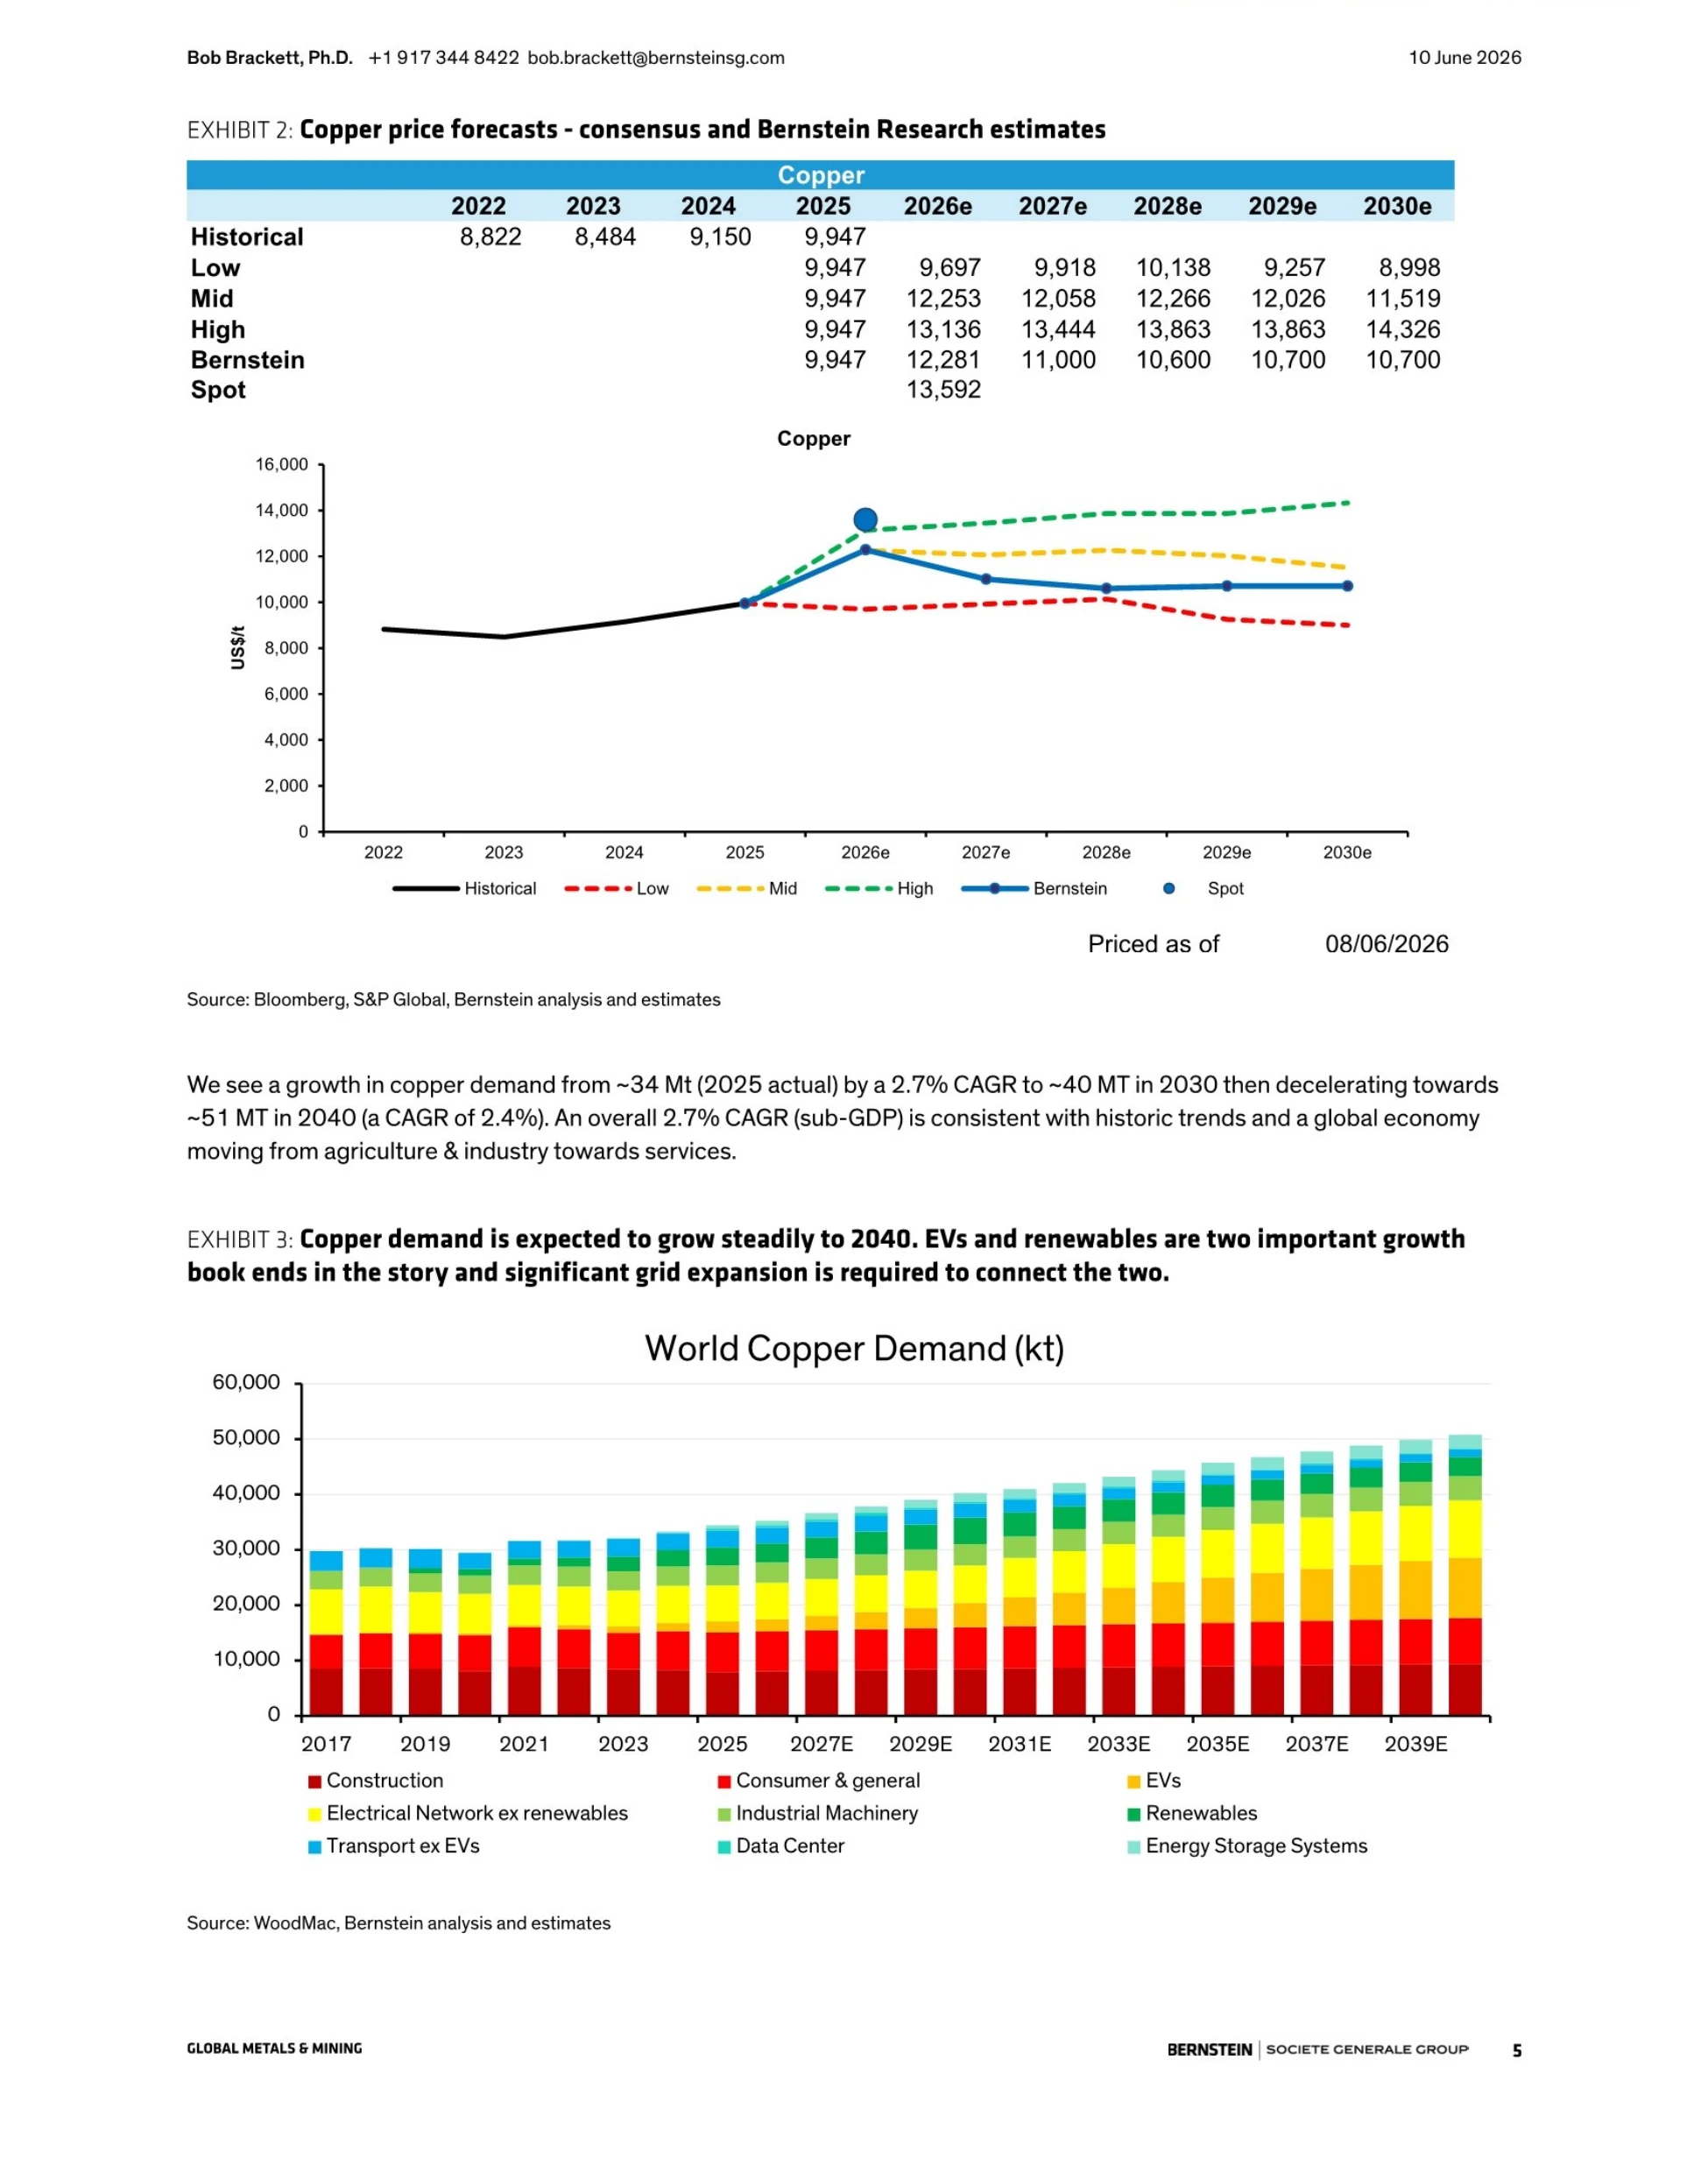
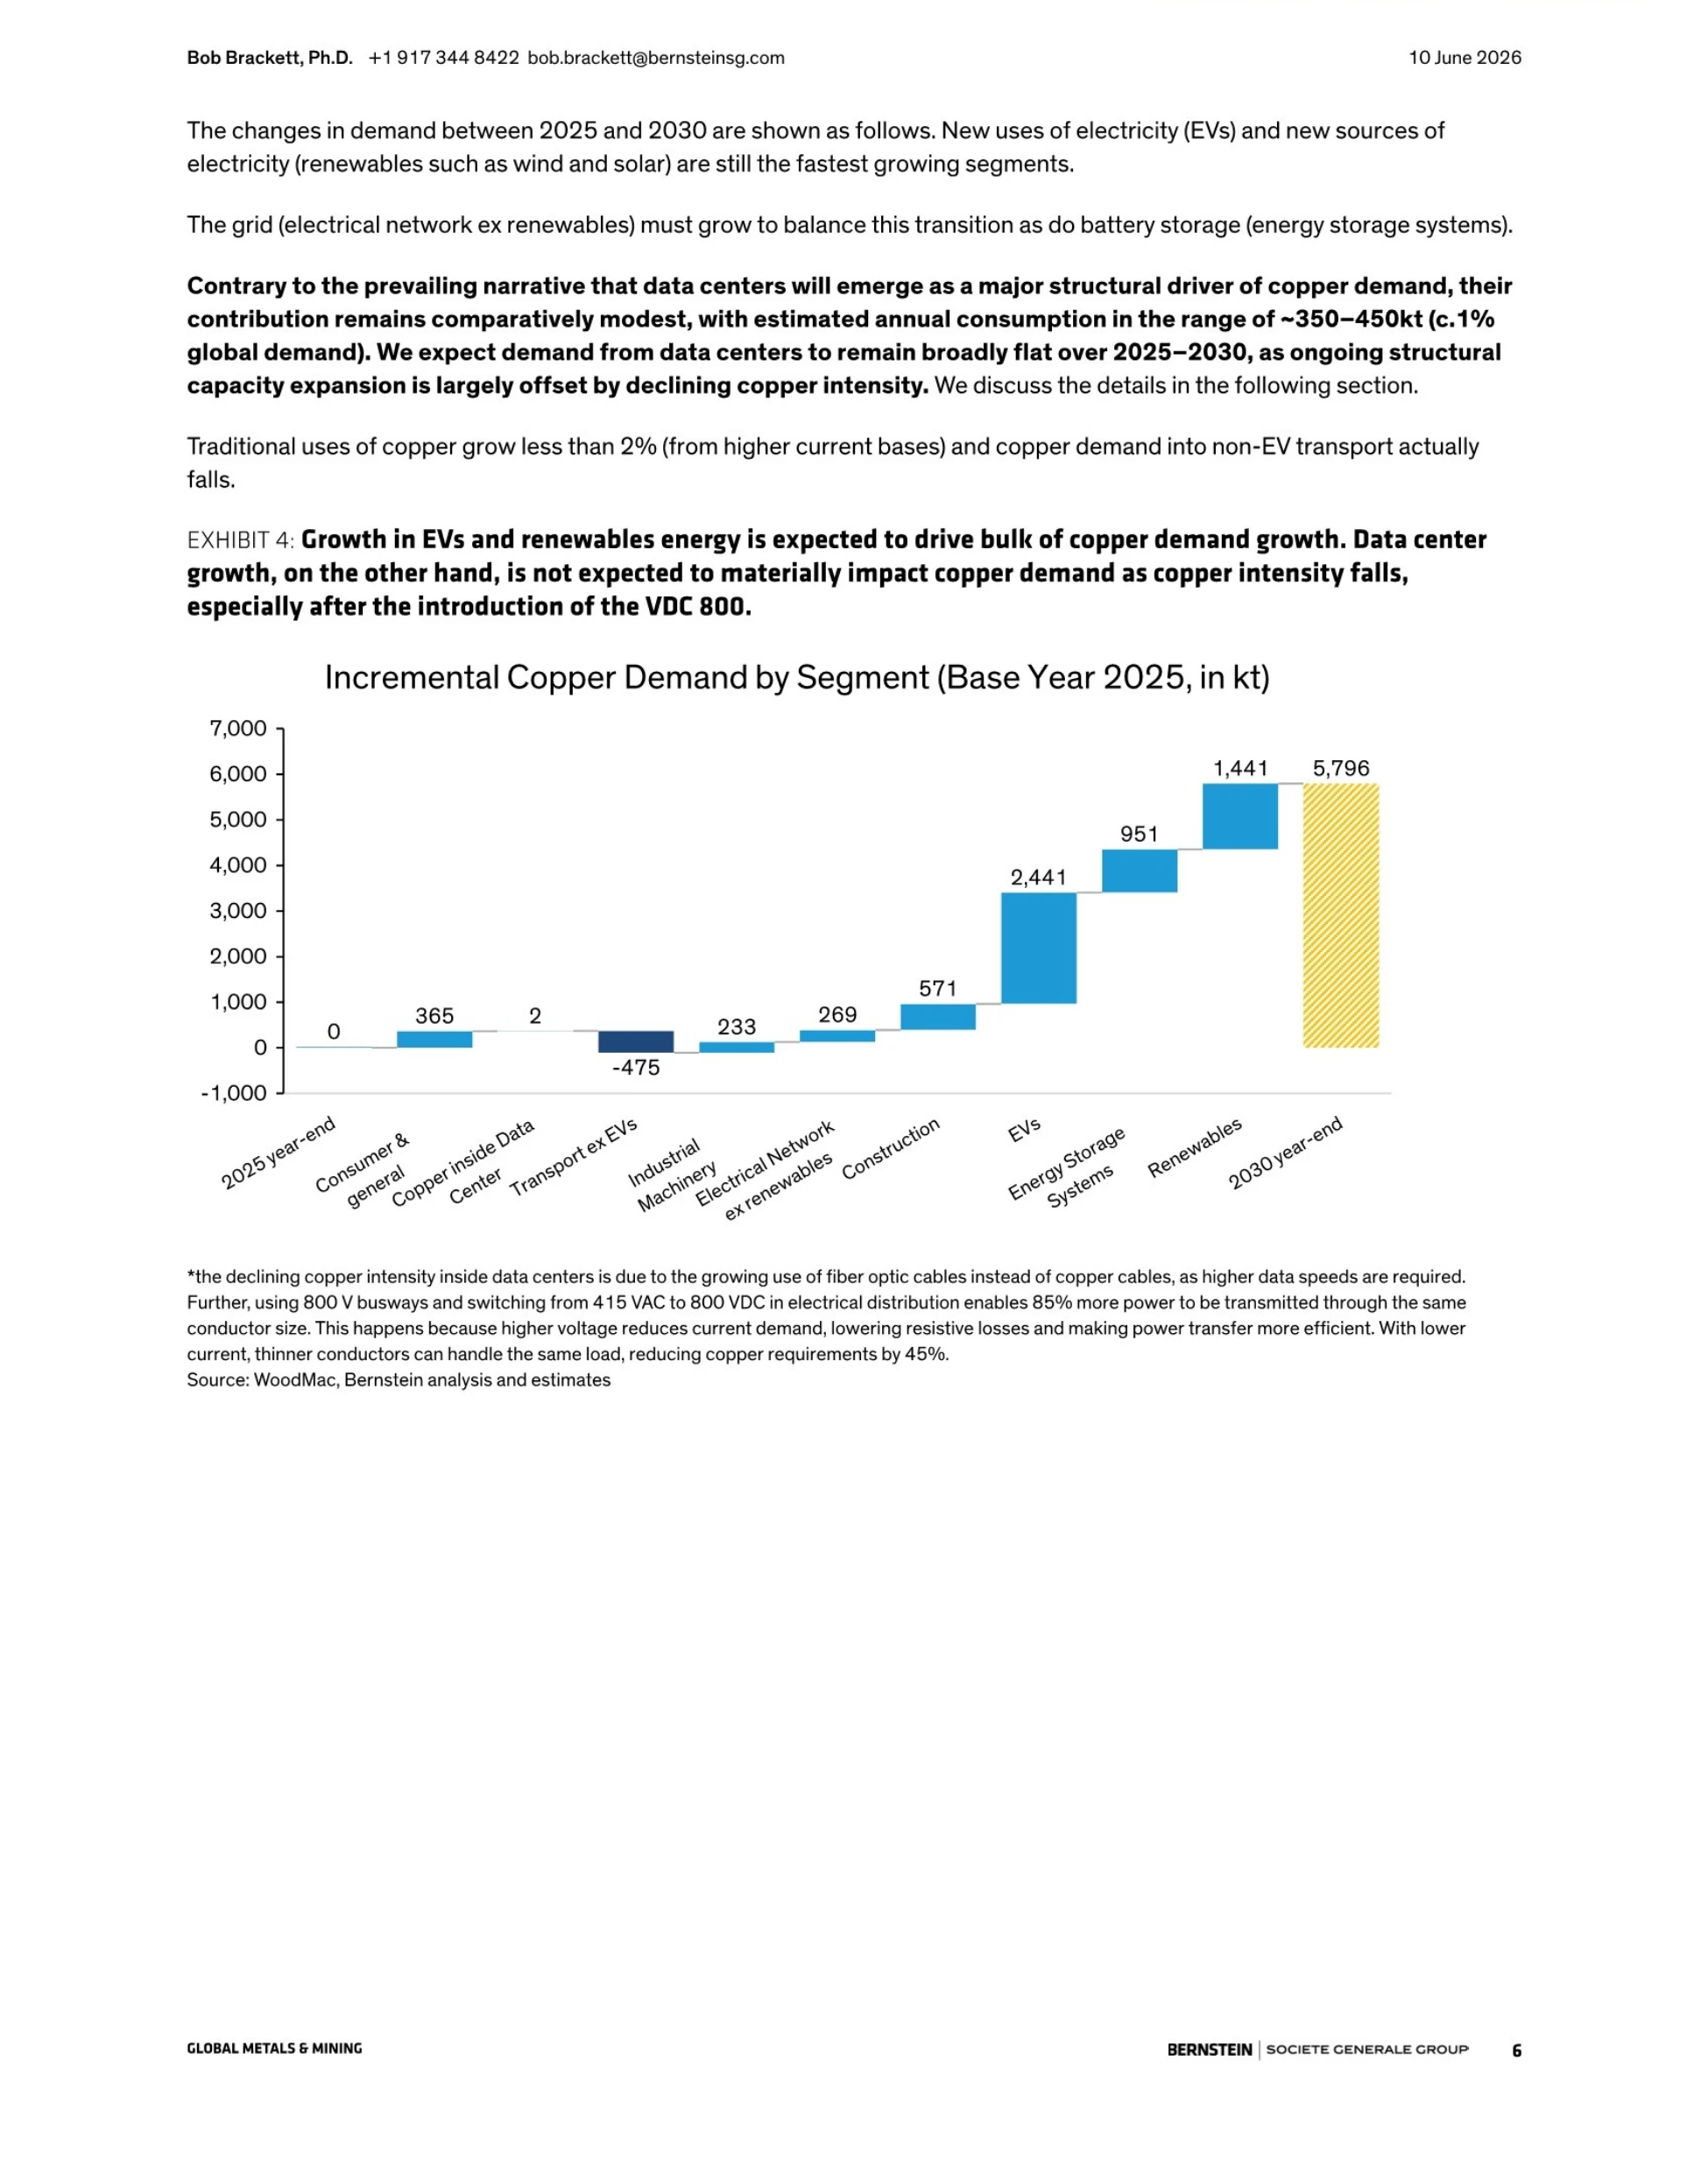
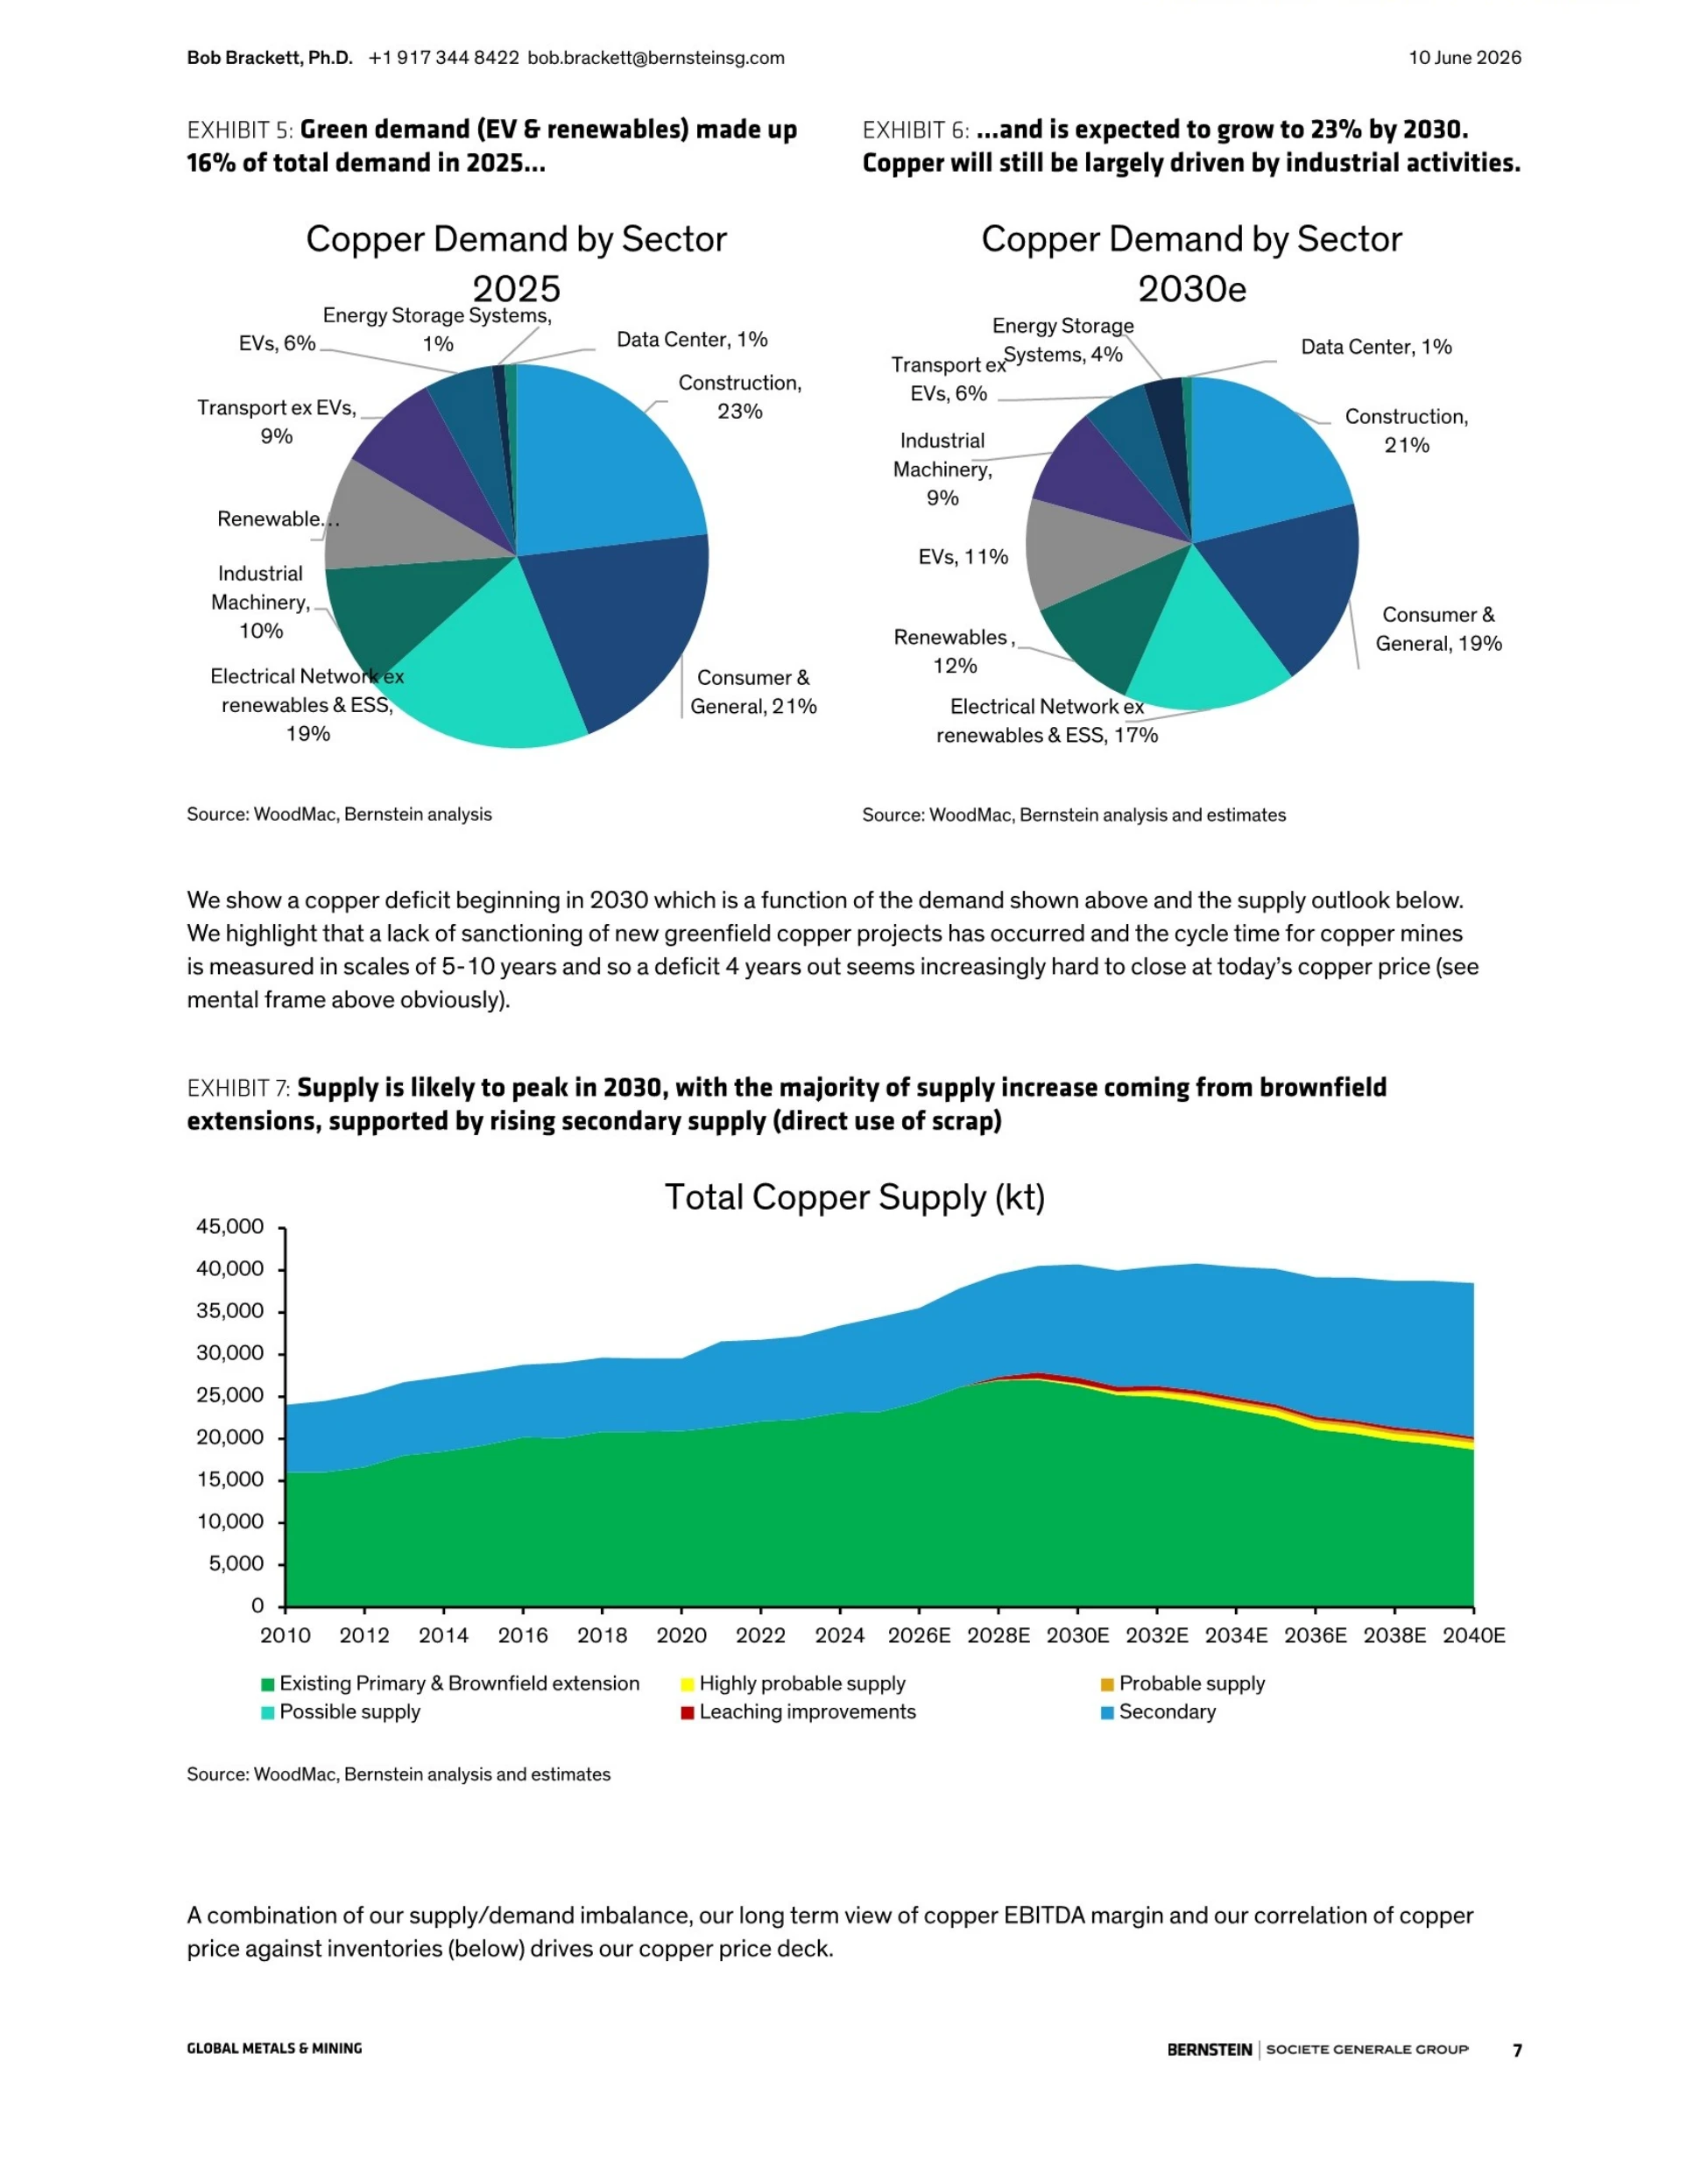
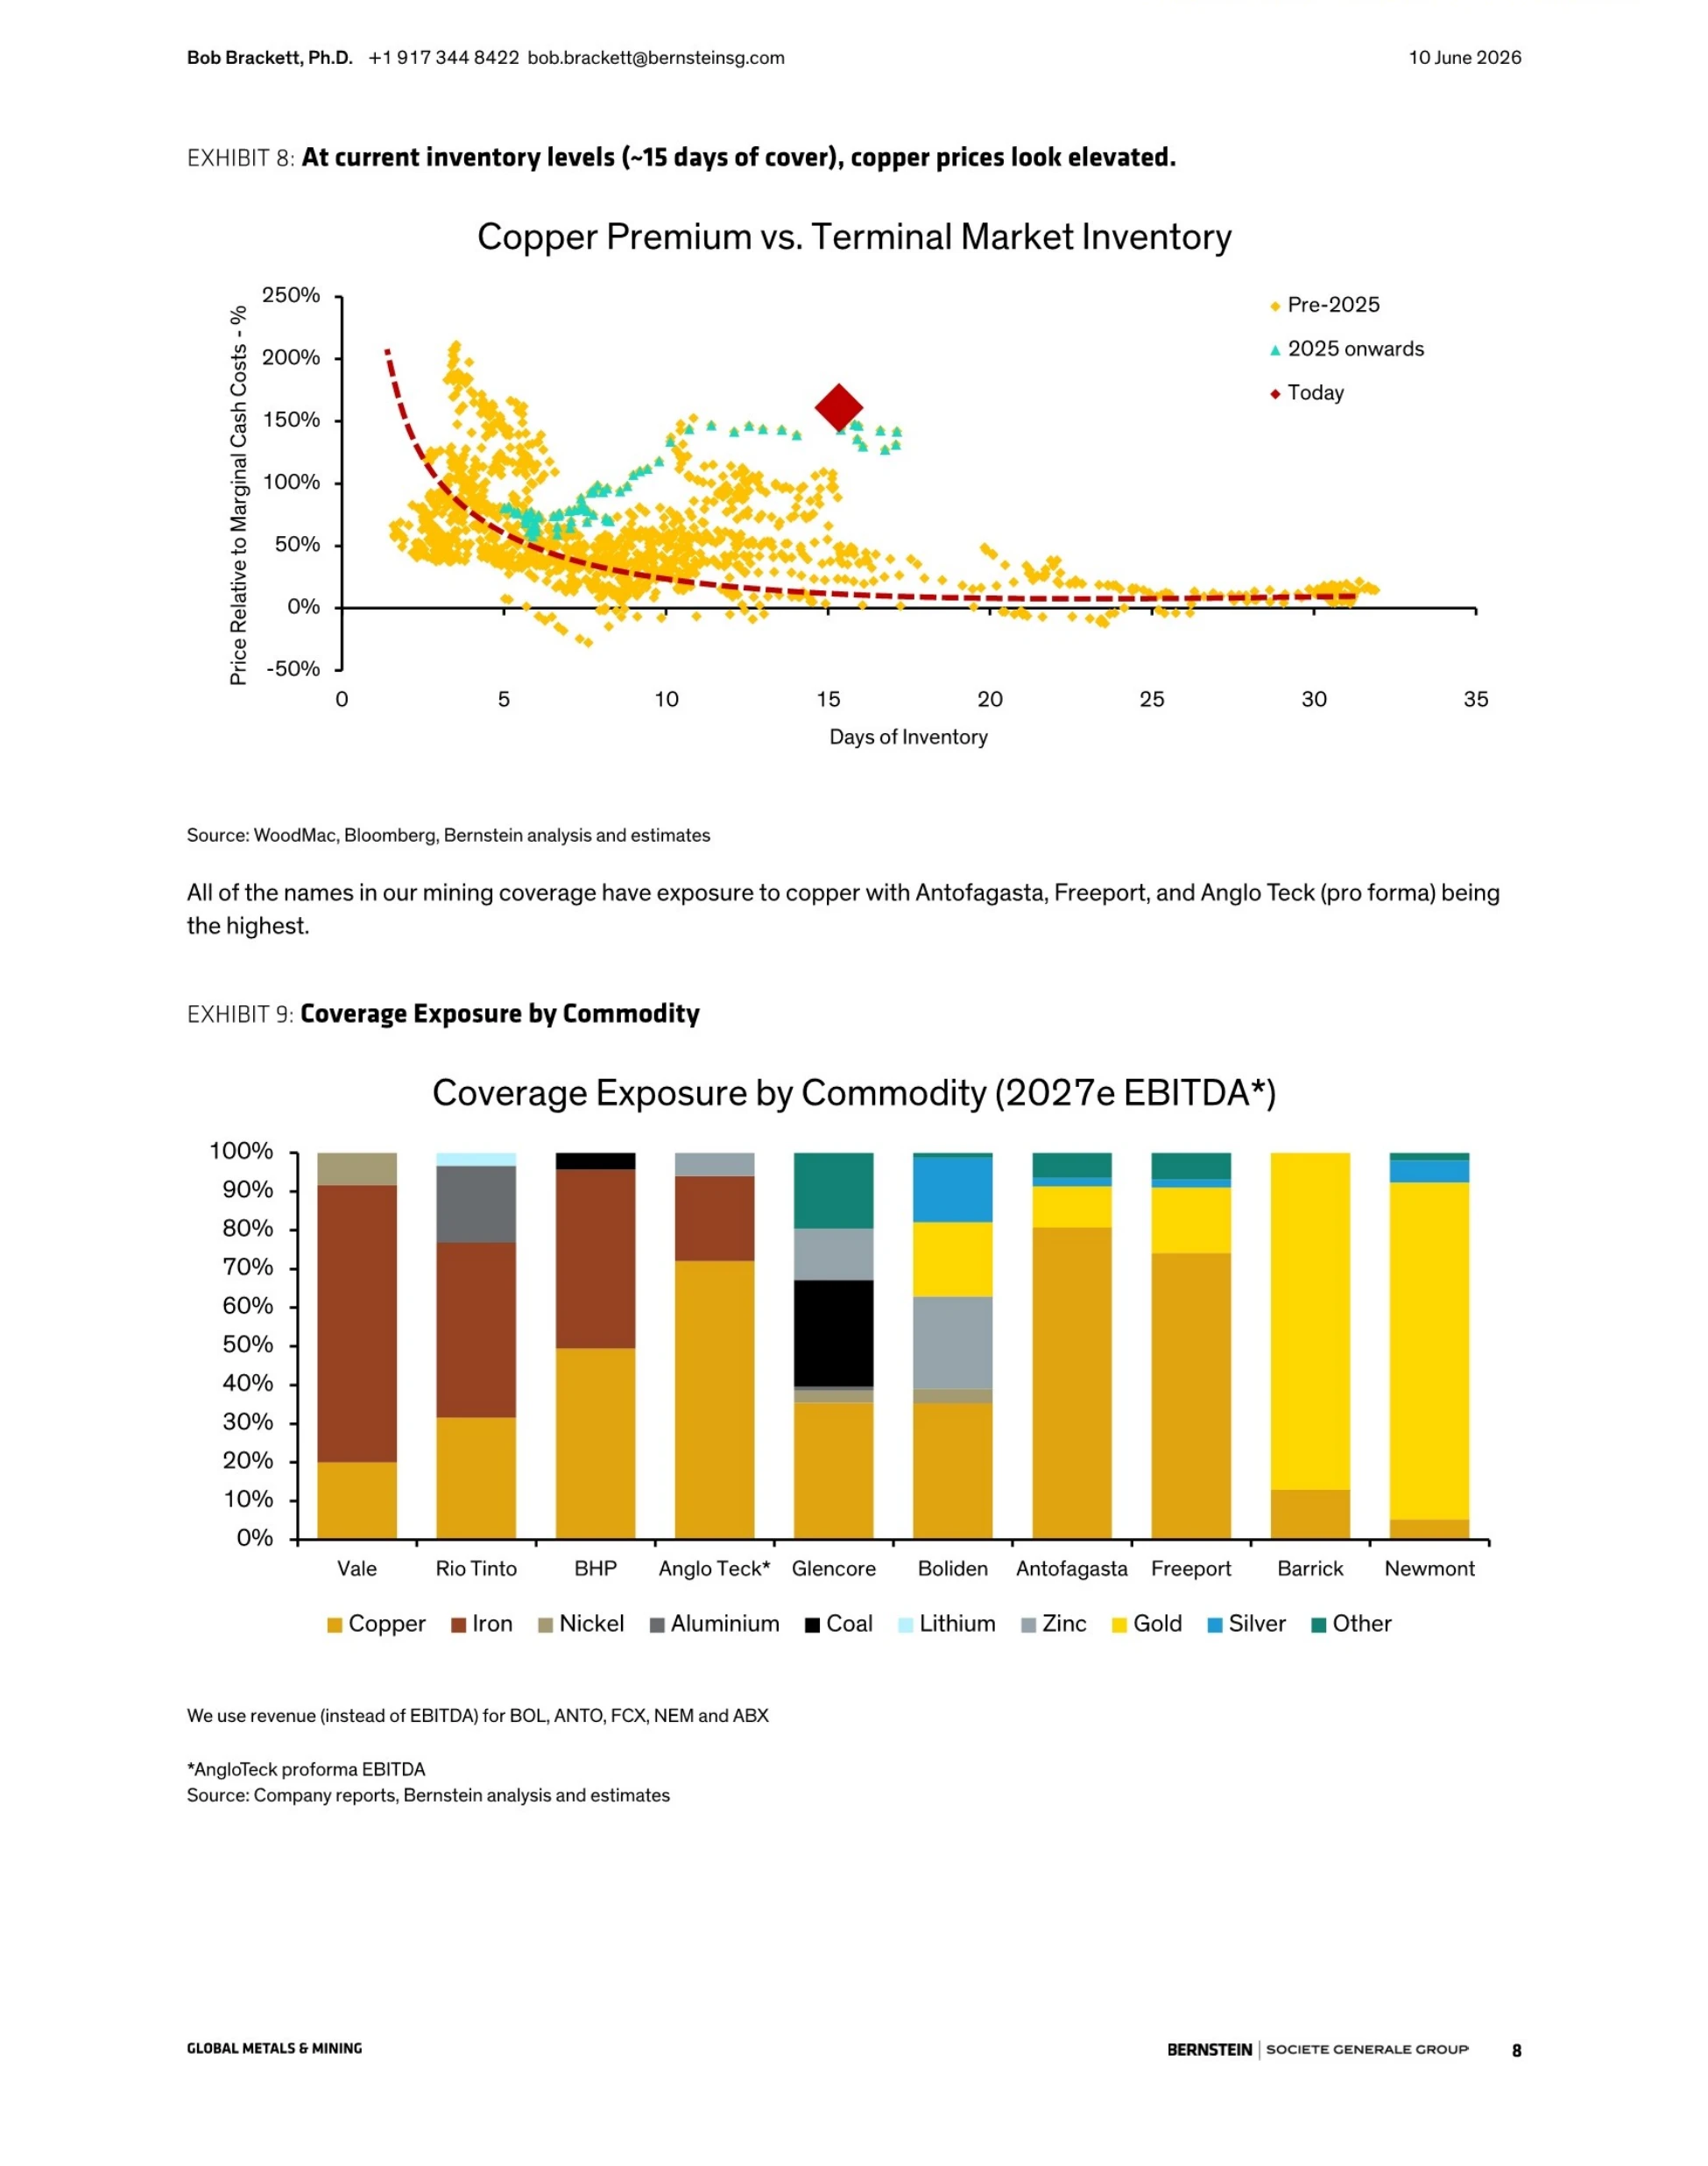
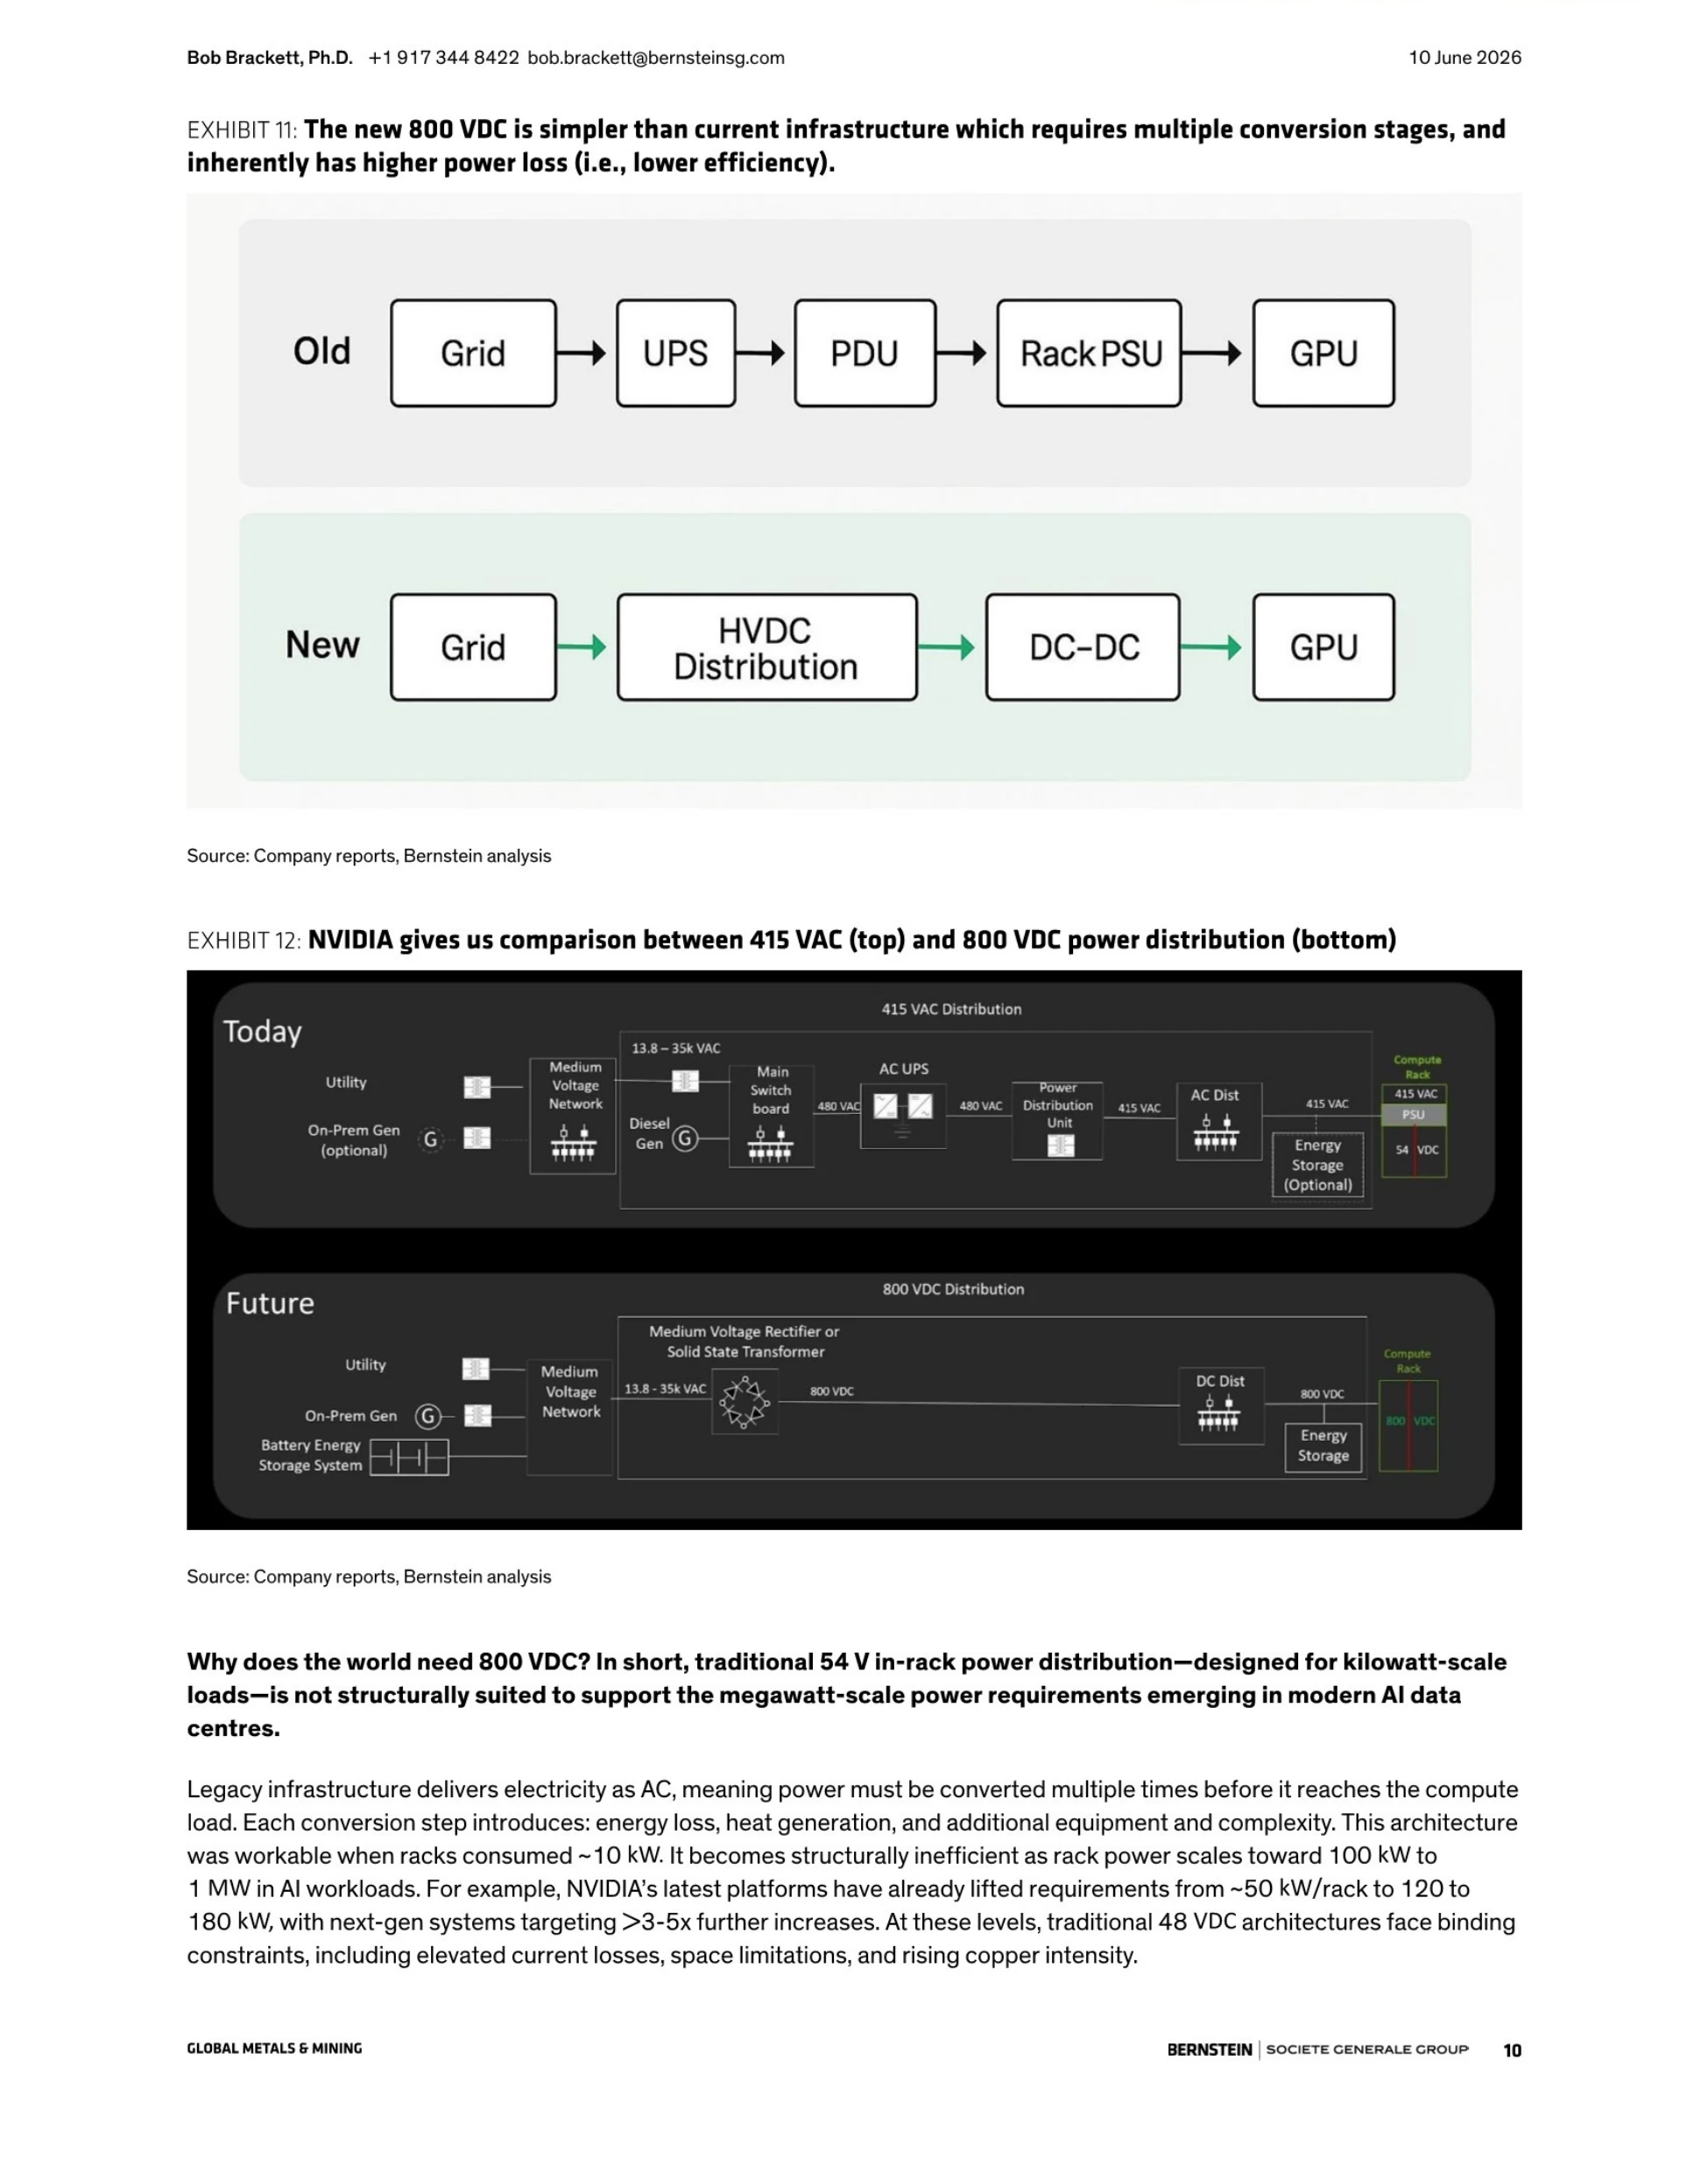
1IRHWGjBsY9ZdX7NbP7NsQrRmOoQlOmMpRjMpOpPaQnMpRNZrQrRwMpMpRSOCIETEGENERALEGROUPGlobal Metals & MiningCopper Long View: Three misconceptions around data centers andcopperBob Brackett, Ph.D.Weupdateourlongtermviewoncopperhereindepth.Ourmodelsareavailabletoclients+1917344 8422Weorganizein foursectionsasfollows:wesummarize ourcallinafewcharts.We thenbob.brackett@bernsteinsg.comreviewwhat'snew&improvedinthis currentoutlook.Finally,weprovidethe completedetails.We wait fora better entry point intoafuture coppermarketwe expectto tighten.Andrianto Guntoro, CFA+4420 7676 6825On demand, our updated data center (DC) work highlights three areas whereandrianto.guntoro@bernsteinsg.comapproaching~200 GW by 2030, copper intensity is expected to fall meaningfully (Exhibit10).The shift toward 800 VDC architecture, particularly in Al training facilities, reducescopper requirements by as much as 45%, with a more gradual impact in inferencing.Second,theread-throughtoT&D capex and copperdemand withingrids islessdirect than headline growth implies.Interconnection delays across the U.S.and Europeare pushing more operators toward behind-the-meter (BTM) solutions, with up to~33-44% of demand potentially met on-site (Exhibit 21).This dampens near-term grid build-outintensity. However, given that BTM is stll viewed as a bridge rather than a substitute, we stillby~$50-80bnperannumover2030-2050(Exhibit22).Bycontrast,energystoragesystems (Ess)emergeasamorerobustsourceofcopperdemandthandatacenters.Capacityis settoscalefrom~550GWh in2025to~1,500 GWh by2030 (Exhibit 26),driven by rising renewable penetration and theneedfor system flexibility. Unlike data centers,we do not see ameaningful near-term decline inion, likely to scale in the 2030s.On the supplyside,werevisitkeyprojectsand adjust ourconvictionlevels (Exhibit23).We upgrade BHP's Escondida OGP2 and First Quantum's Cobre Panama to"GoingAheadreflecting improved visibility on execution.Conversely,wetakea more cautiousview on Barrick's Reko Diq,downgrading it to"Probable"We also refresh the status ofseveral other projects, including Elang, Coroccohuayco, Copperwood, Nifty Restart,Cascabel, and Gunnison SX-EW.In terms of investment ideas:Weseecopperpricecurrentlyelevatedwithreasonably skewed risktothedownside.We see copper-focused equitiesmostly reflecting optimism on copperastheytrade at meaningful premium to their 5-year average multiples (Exhibit 46).For example,Lundin and Southern Copper aretrading at more than+2 standarddeviations above theirrespective 5-year averages.In comparison,ANTO (Market-Perform)and FCX (Market-Perform)are trading atapproximately+1.7 and+0.6 standard deviations above their 5-yearaverages.With2027consensus atc.$12,500/t,valuations implyexpectationsfor>$13,500/t copperprice.WereiterateourMarket-Performratingon our copperpureplays ANTO and FCX.See the Disclosure Appendix of thisreportfor requireddisclosures,analyst certifications and otherwww.bernsteinresearch.comimportant information.Alternatively,visit our Global Research Disclosure Website.FirstPublished:1...