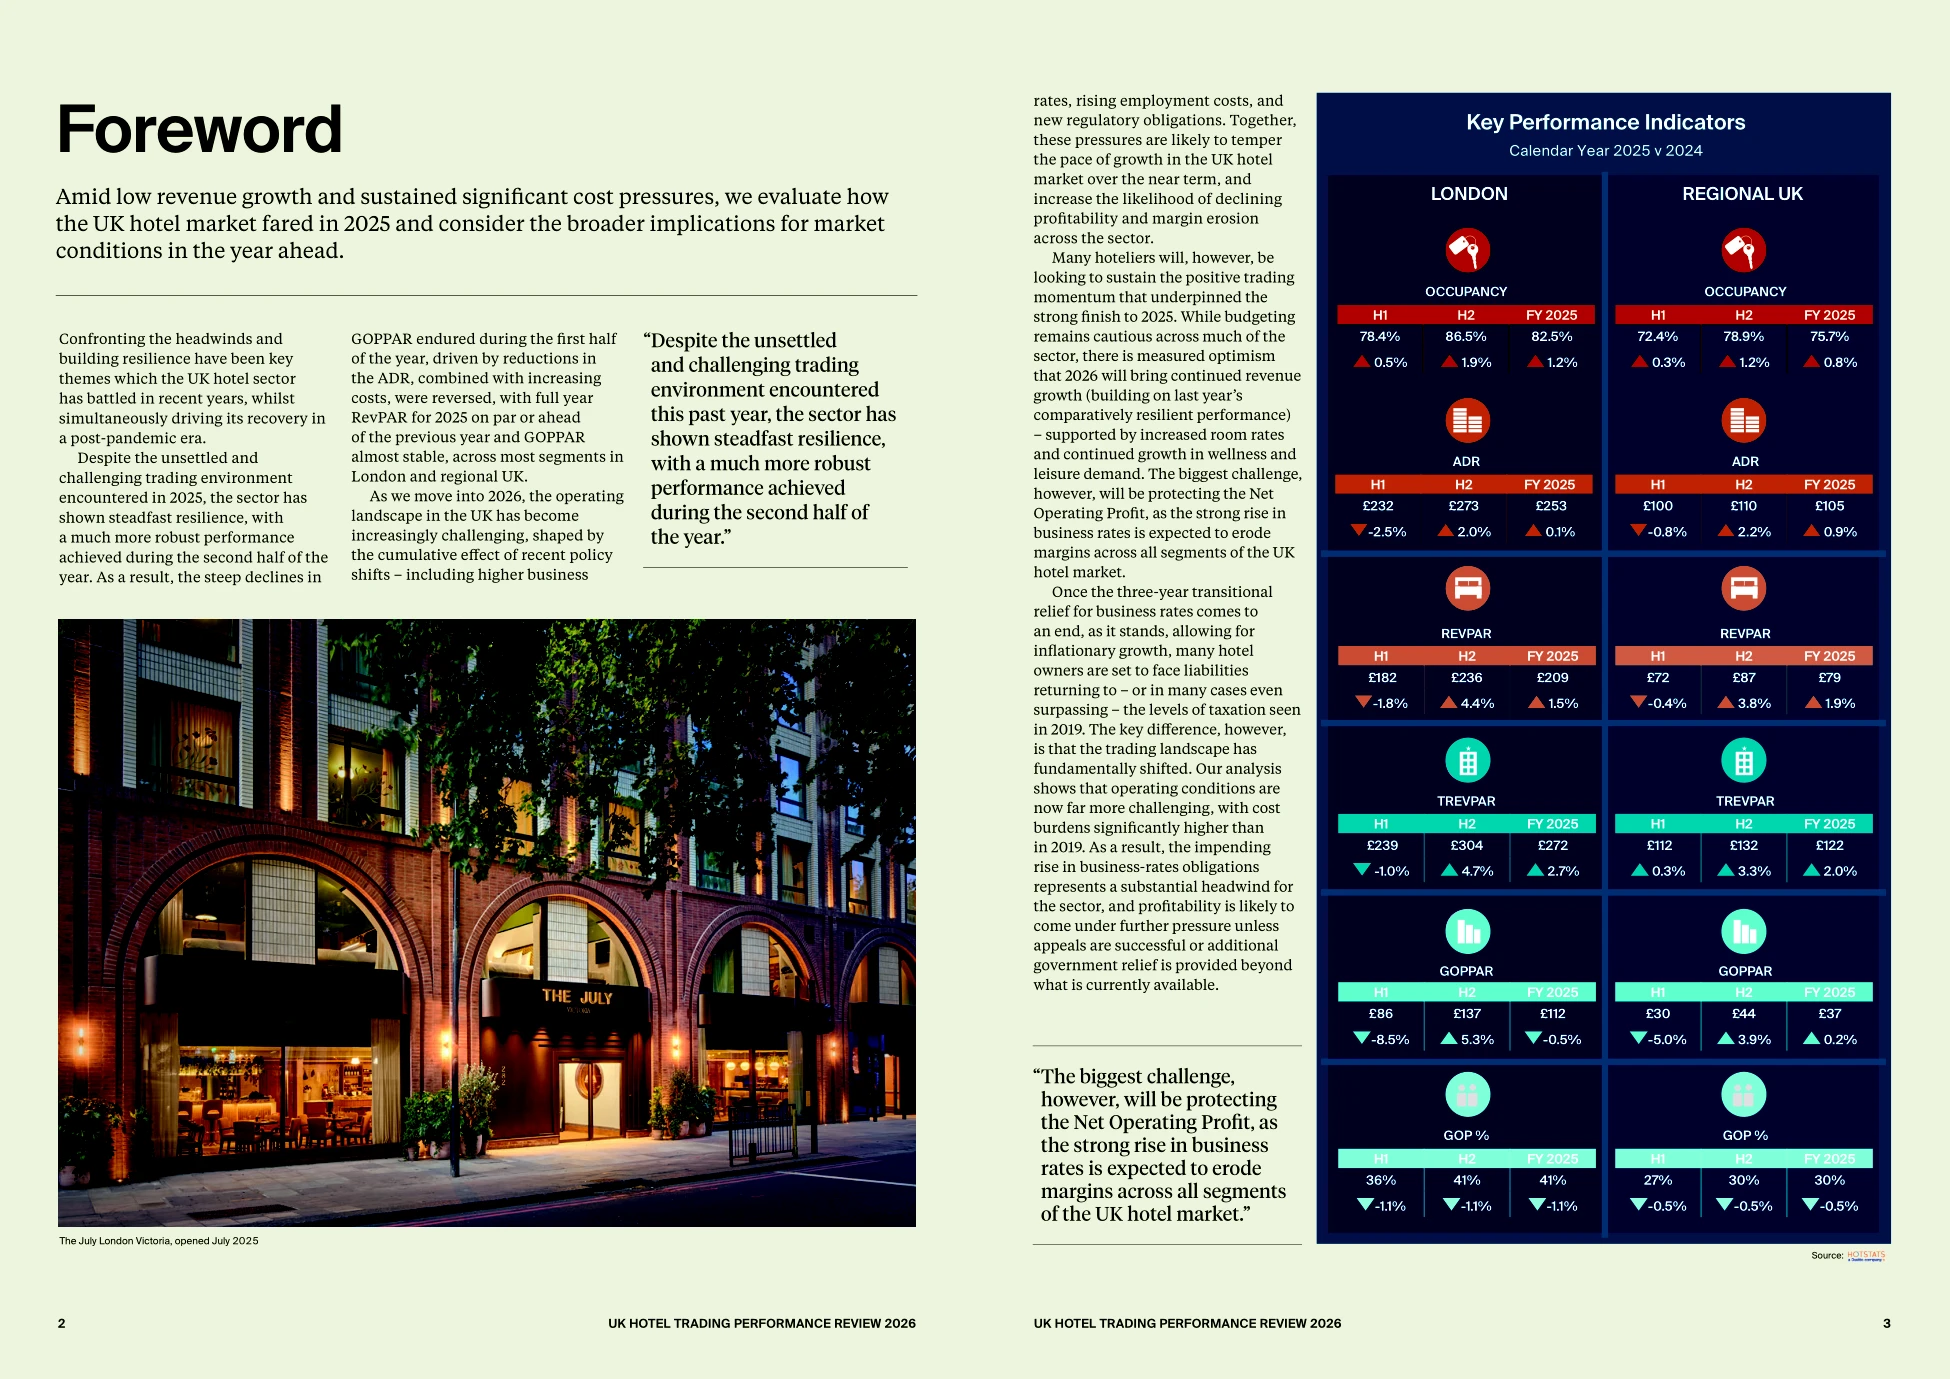
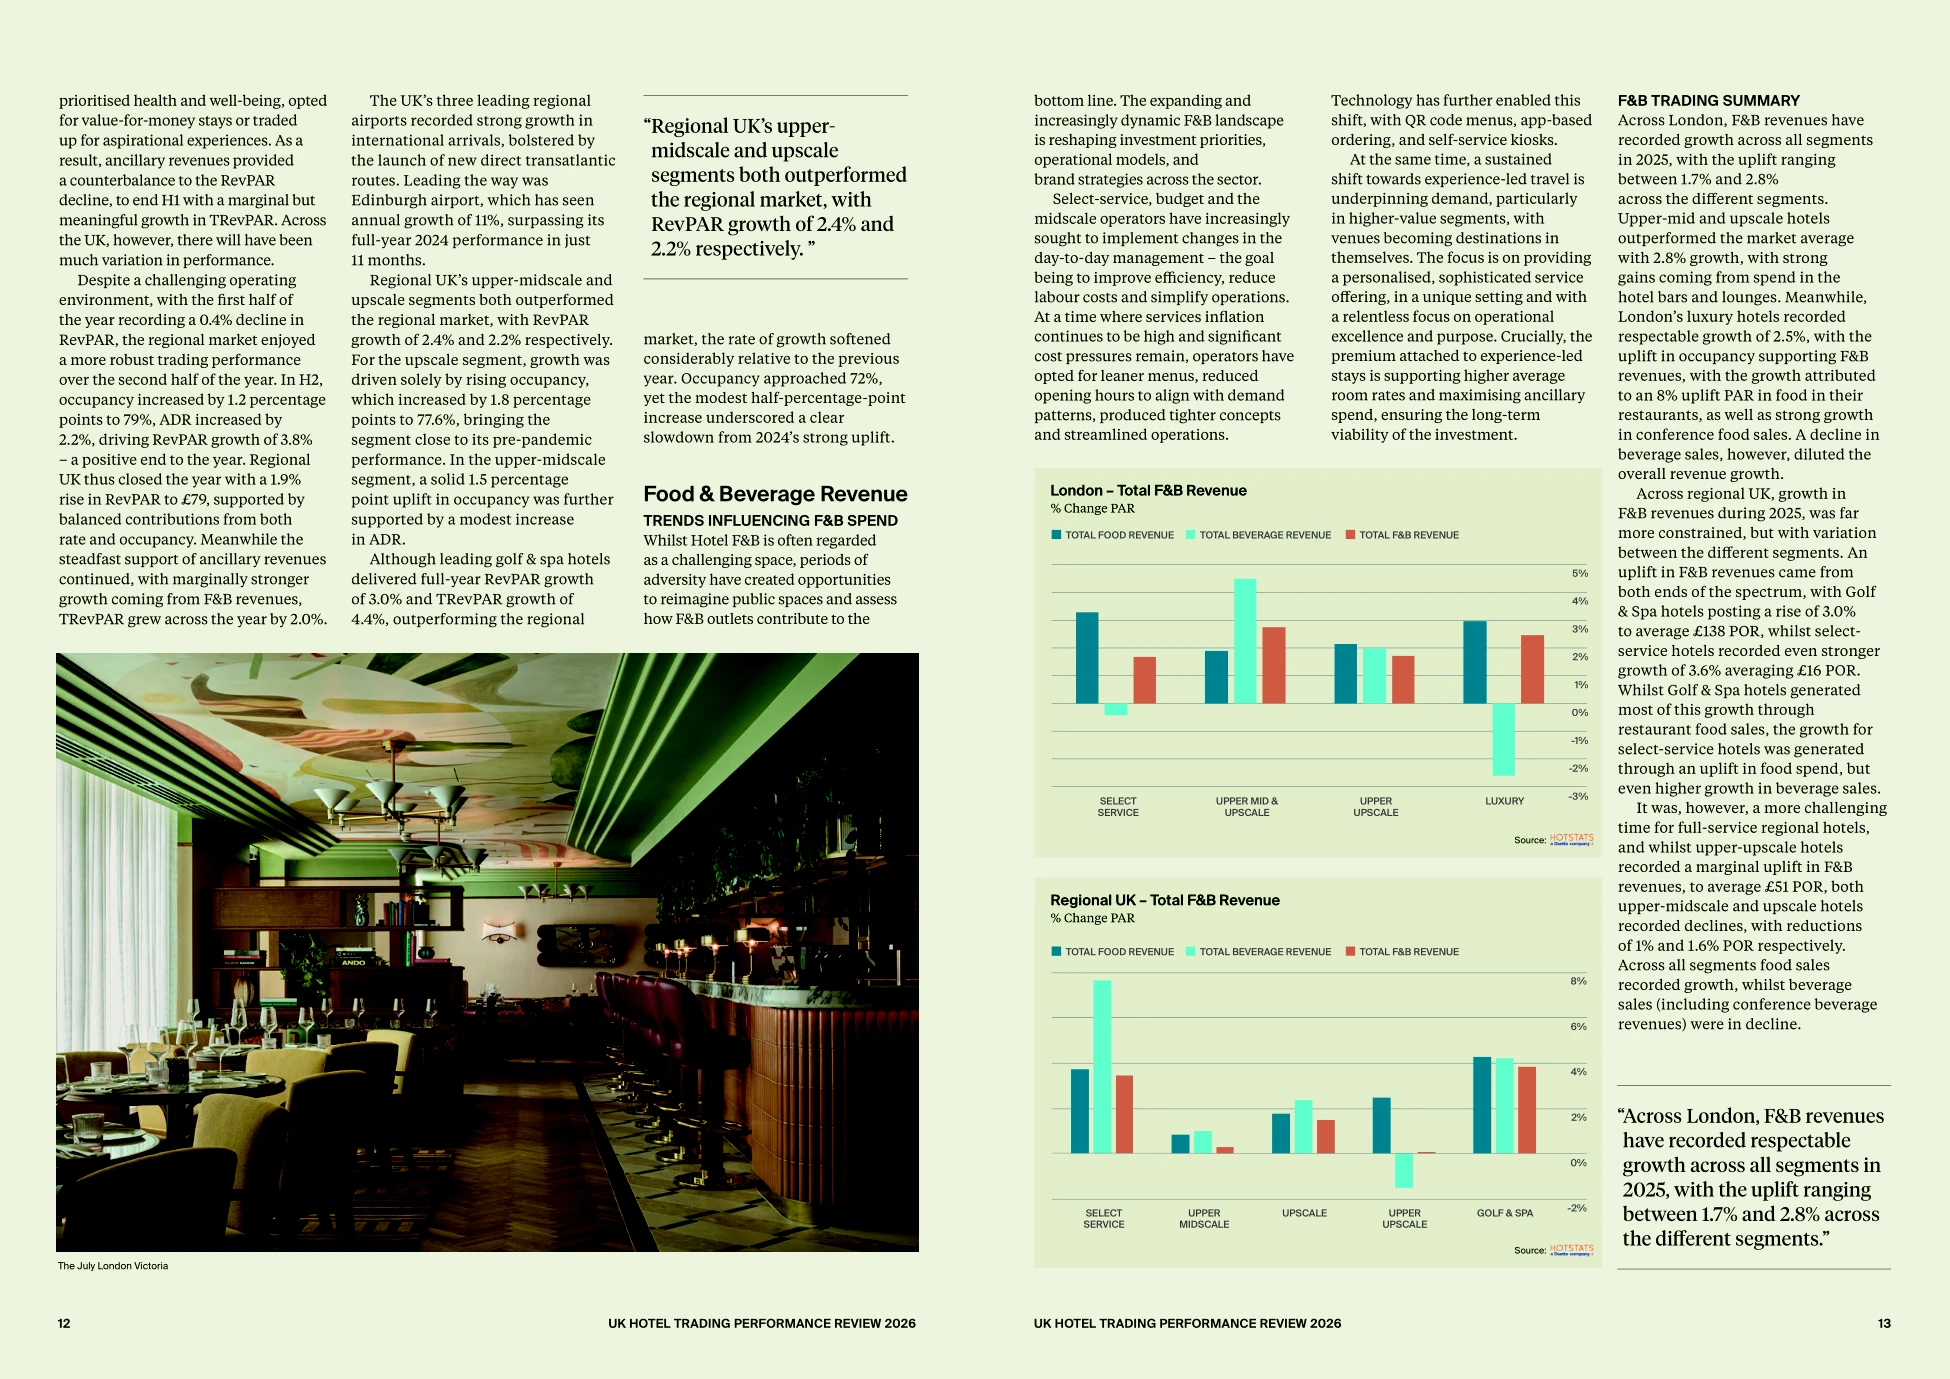
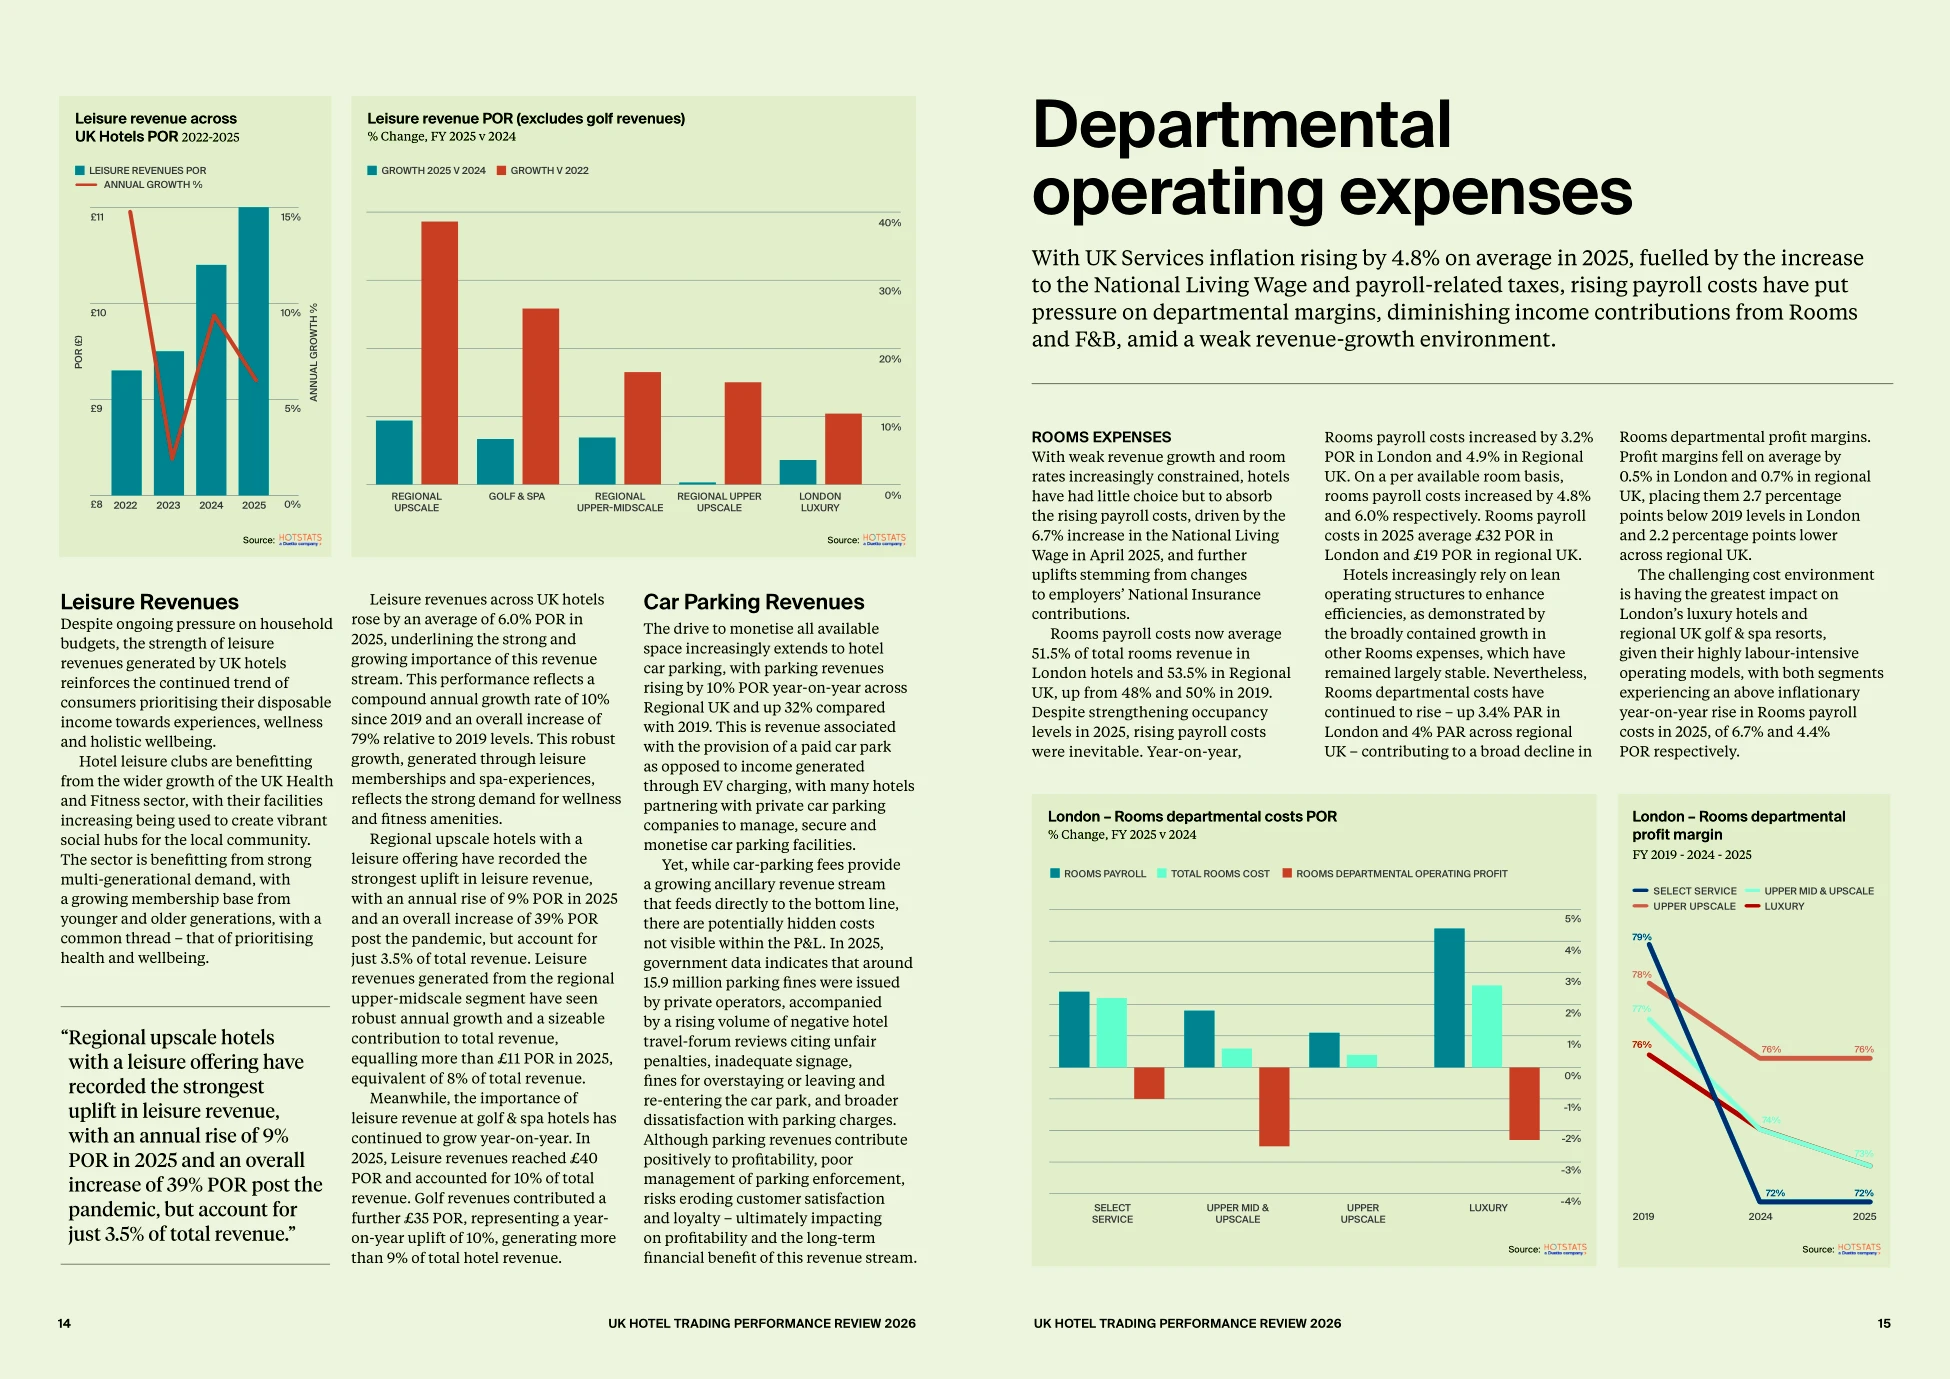
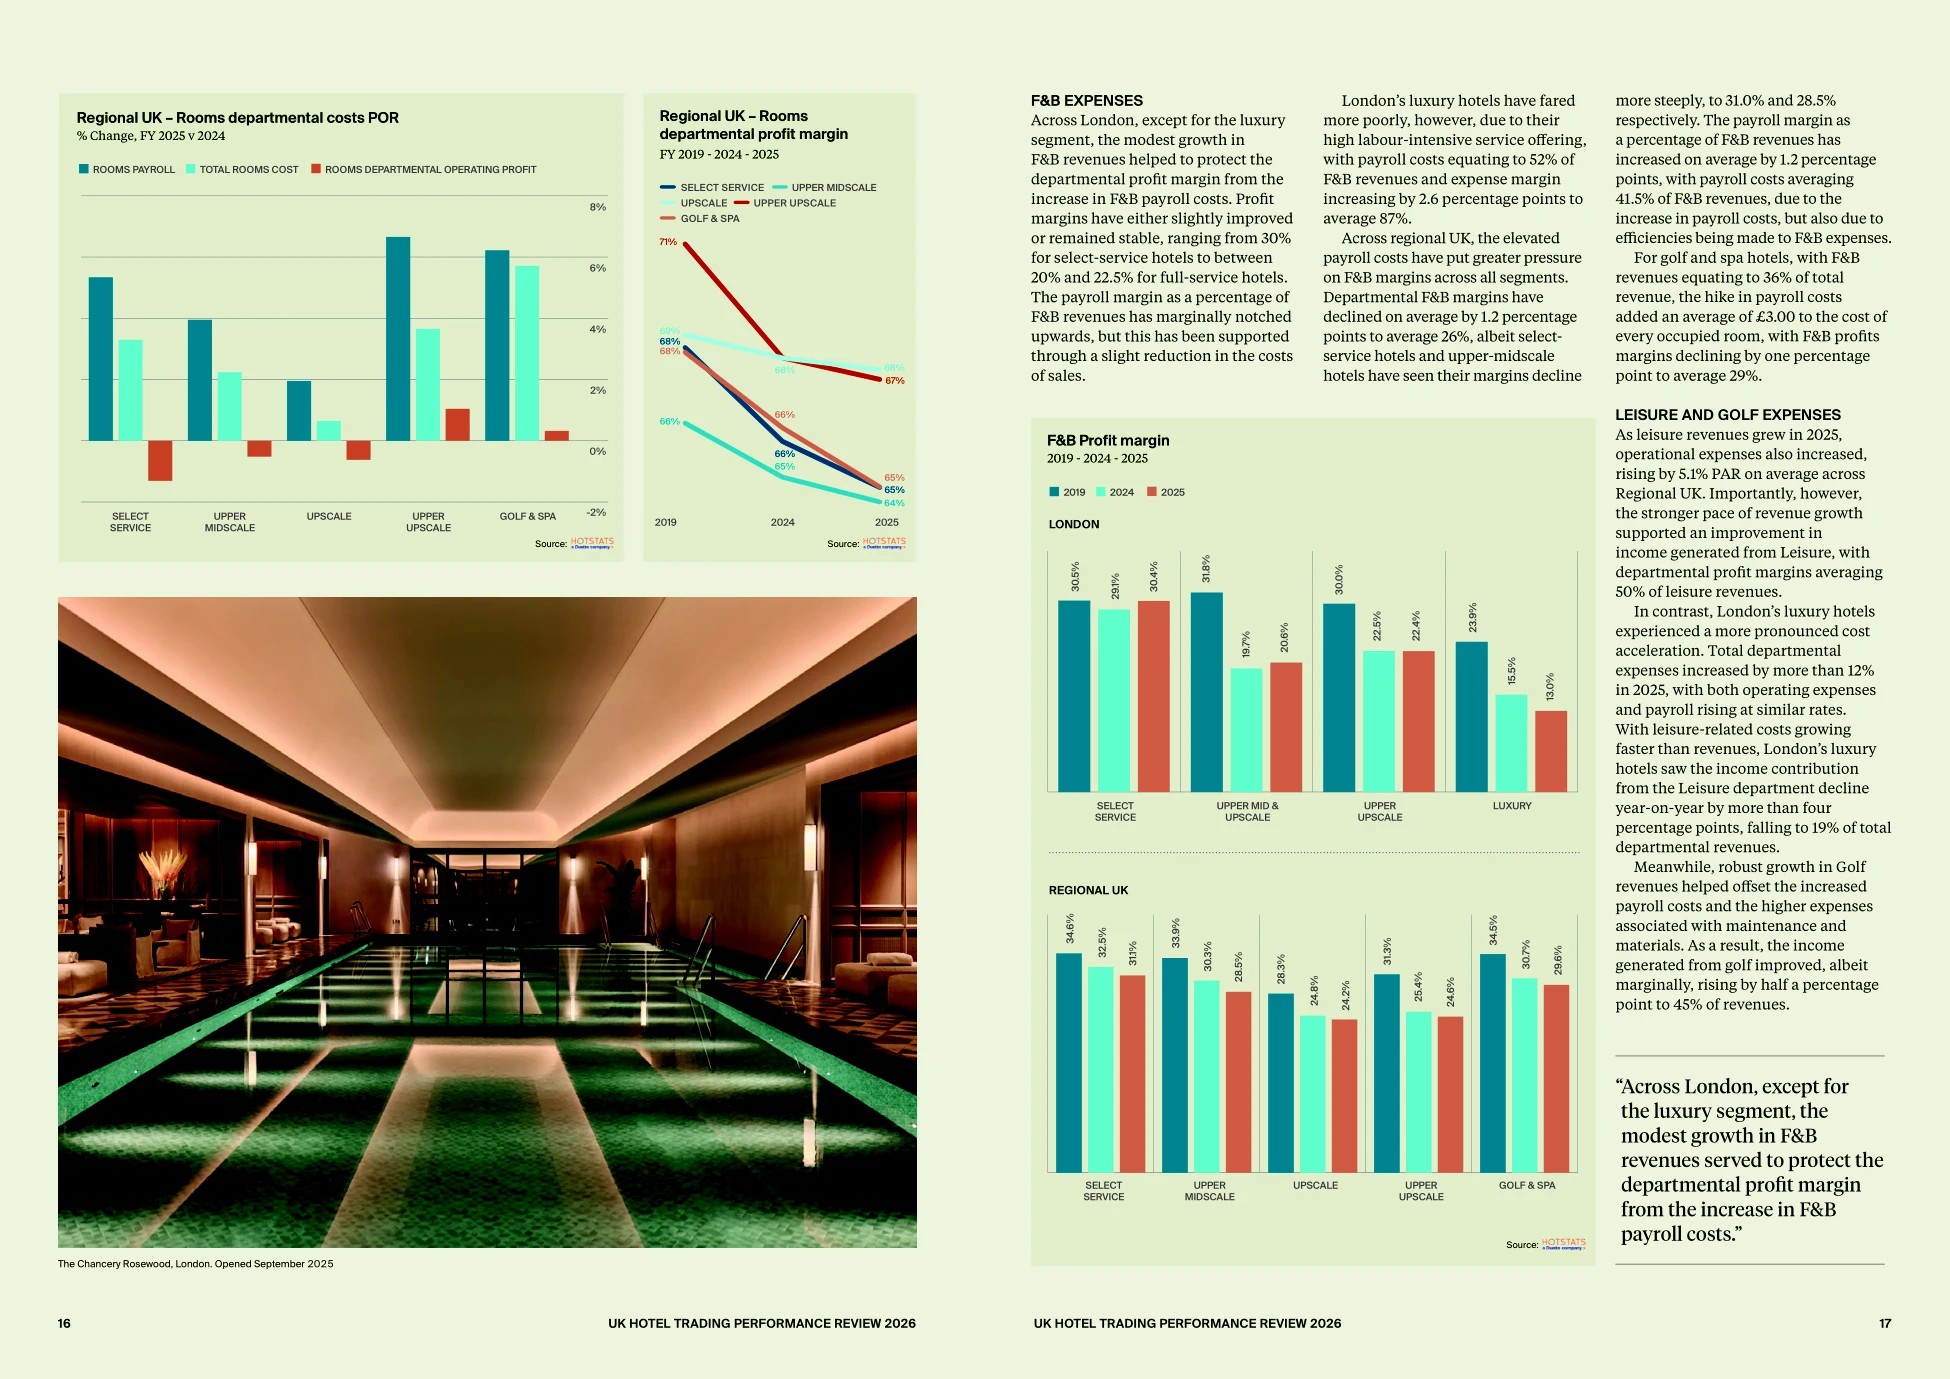
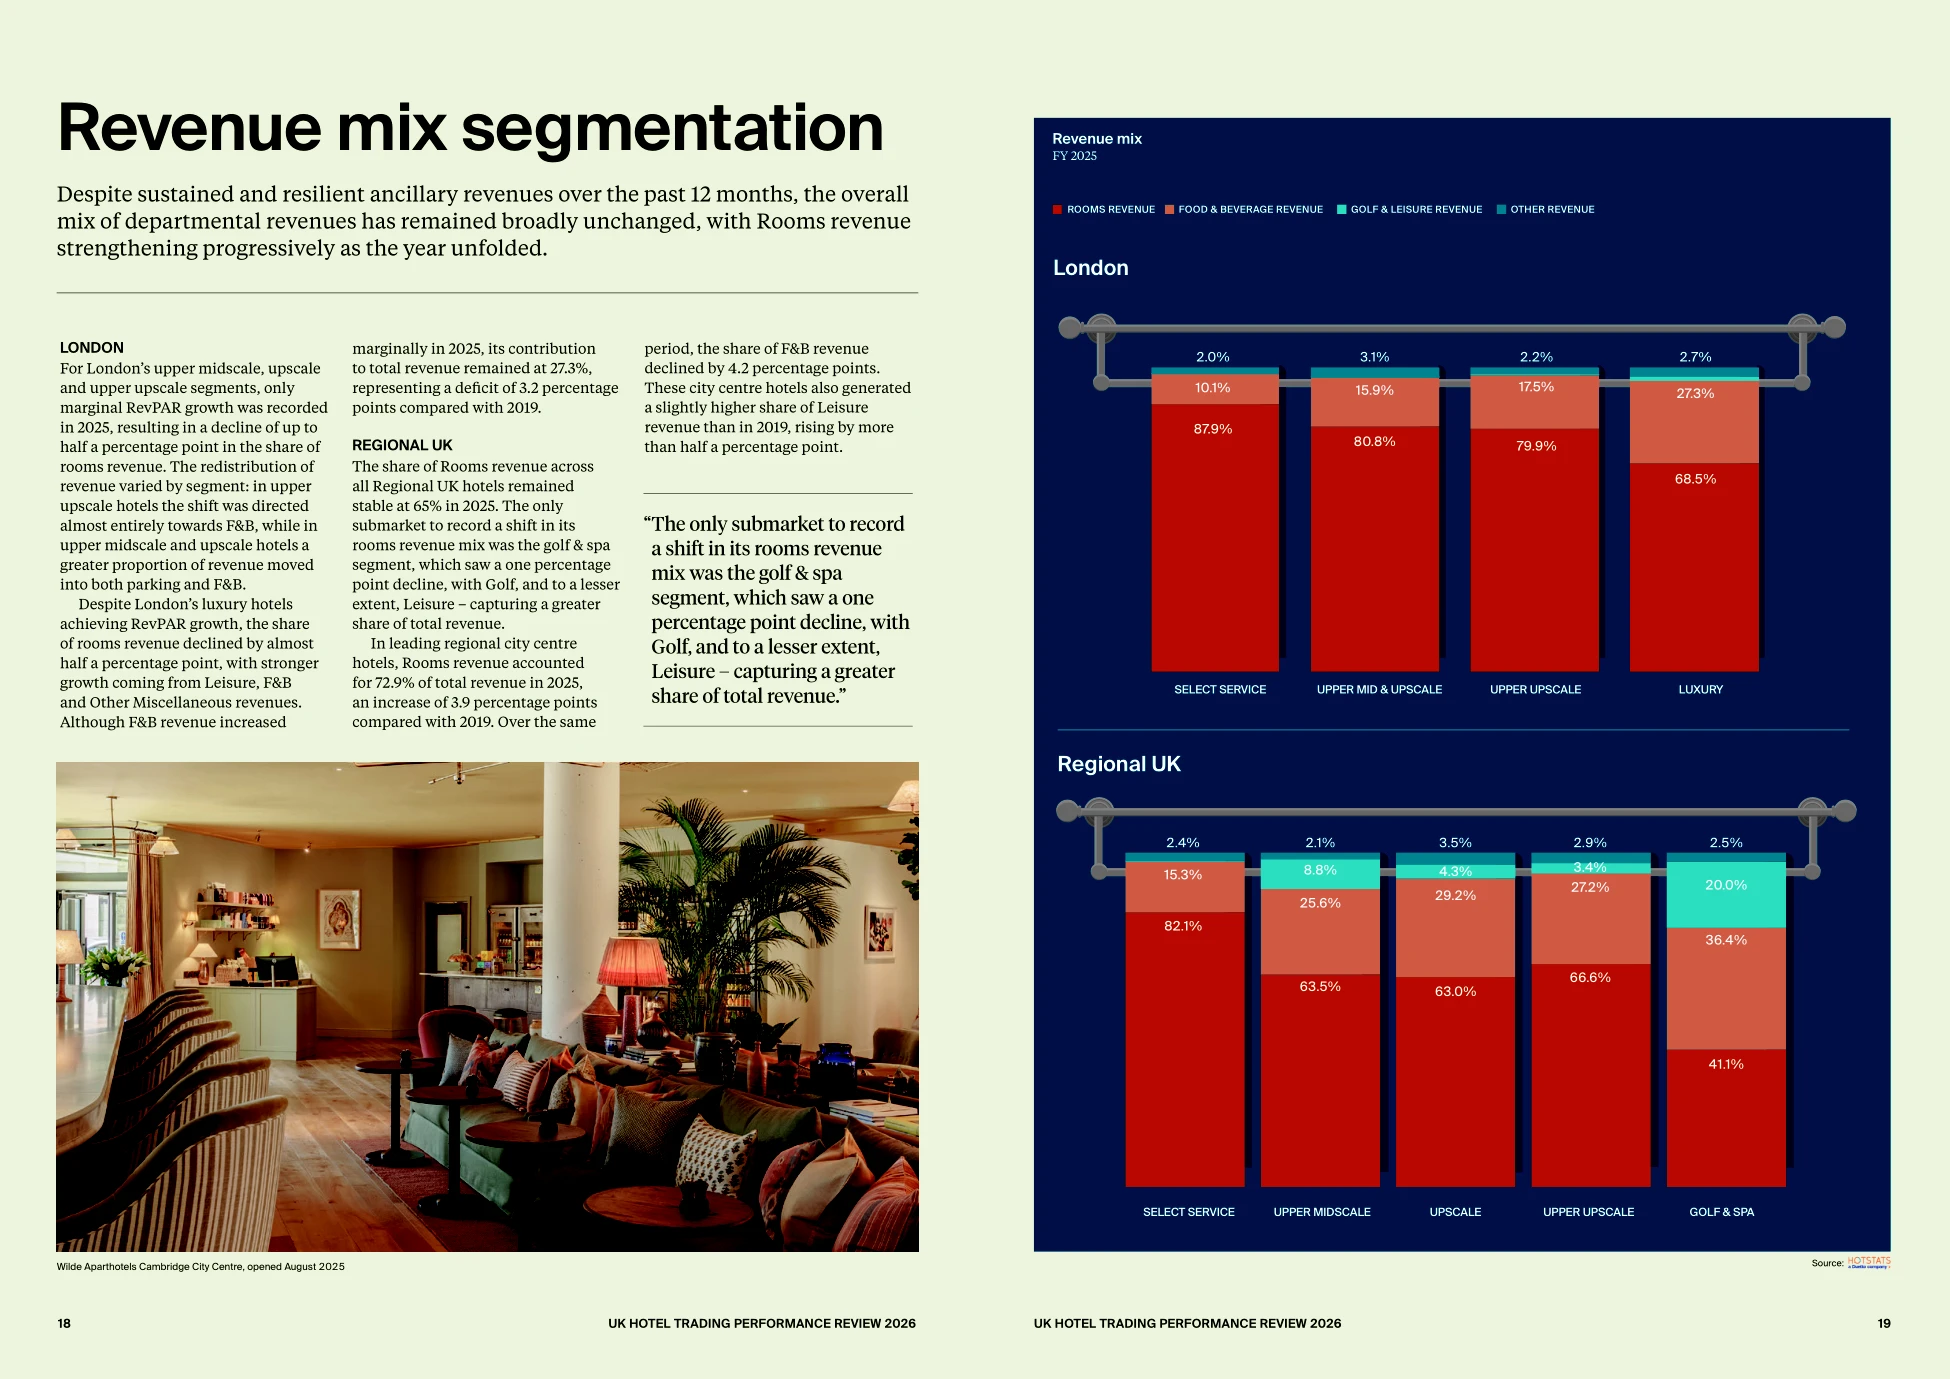
UK HotelTrading Performance Reviewhttps://www.knightfrank.co.uk/research/sectors/hotels2026A year of two halves in 2025, but one of steadfast resilience. Thebiggest challenge for the year ahead will be protecting the Net Operating Income, as the strong rise in business rates is expected to erode margins across all segments of the UK hotel market.Confronting the headwinds and building resilience have been key themes which the UK hotel sector has battled in recent years, whilst simultaneously driving its recovery in a post-pandemic era. Despite the unsettled and challenging trading environment encountered in 2025, the sector has shown steadfast resilience, with a much more robust performance achieved during the second half of the year. As a result, the steep declines in “ Despite the unsettled and challenging trading environment encountered this past year, the sector has shown steadfast resilience, with a much more robust performance achieved during the second half of the year.”ForewordAmid low revenue growth and sustained significant cost pressures, we evaluate how the UK hotel market fared in 2025 and consider the broader implications for market conditions in the year ahead.The July London Victoria, opened July 2025rates, rising employment costs, and new regulatory obligations. Together, these pressures are likely to temper the pace of growth in the UK hotel market over the near term, and increase the likelihood of declining profitability and margin erosion across the sector. Many hoteliers will, however, be looking to sustain the positive trading momentum that underpinned the strong finish to 2025. While budgeting remains cautious across much of the sector, there is measured optimism that 2026 will bring continued revenue growth (building on last year’s comparatively resilient performance) – supported by increased room rates and continued growth in wellness and leisure demand. The biggest challenge, however, will be protecting the Net Operating Profit, as the strong rise in business rates is expected to erode margins across all segments of the UK hotel market. Once the three-year transitional relief for business rates comes to an end, as it stands, allowing for inflationary growth, many hotel owners are set to face liabilities returning to – or in many cases even surpassing – the levels of taxation seen in 2019. The key difference, however, is that the trading landscape has fundamentally shifted. Our analysis shows that operating conditions are now far more challenging, with cost burdens significantly higher than in 2019. As a result, the impending rise in business-rates obligations represents a substantial headwind for the sector, and profitability is likely to come under further pressure unless appeals are successful or additional government relief is provided beyond what is currently available.“ The biggest challenge, however, will be...