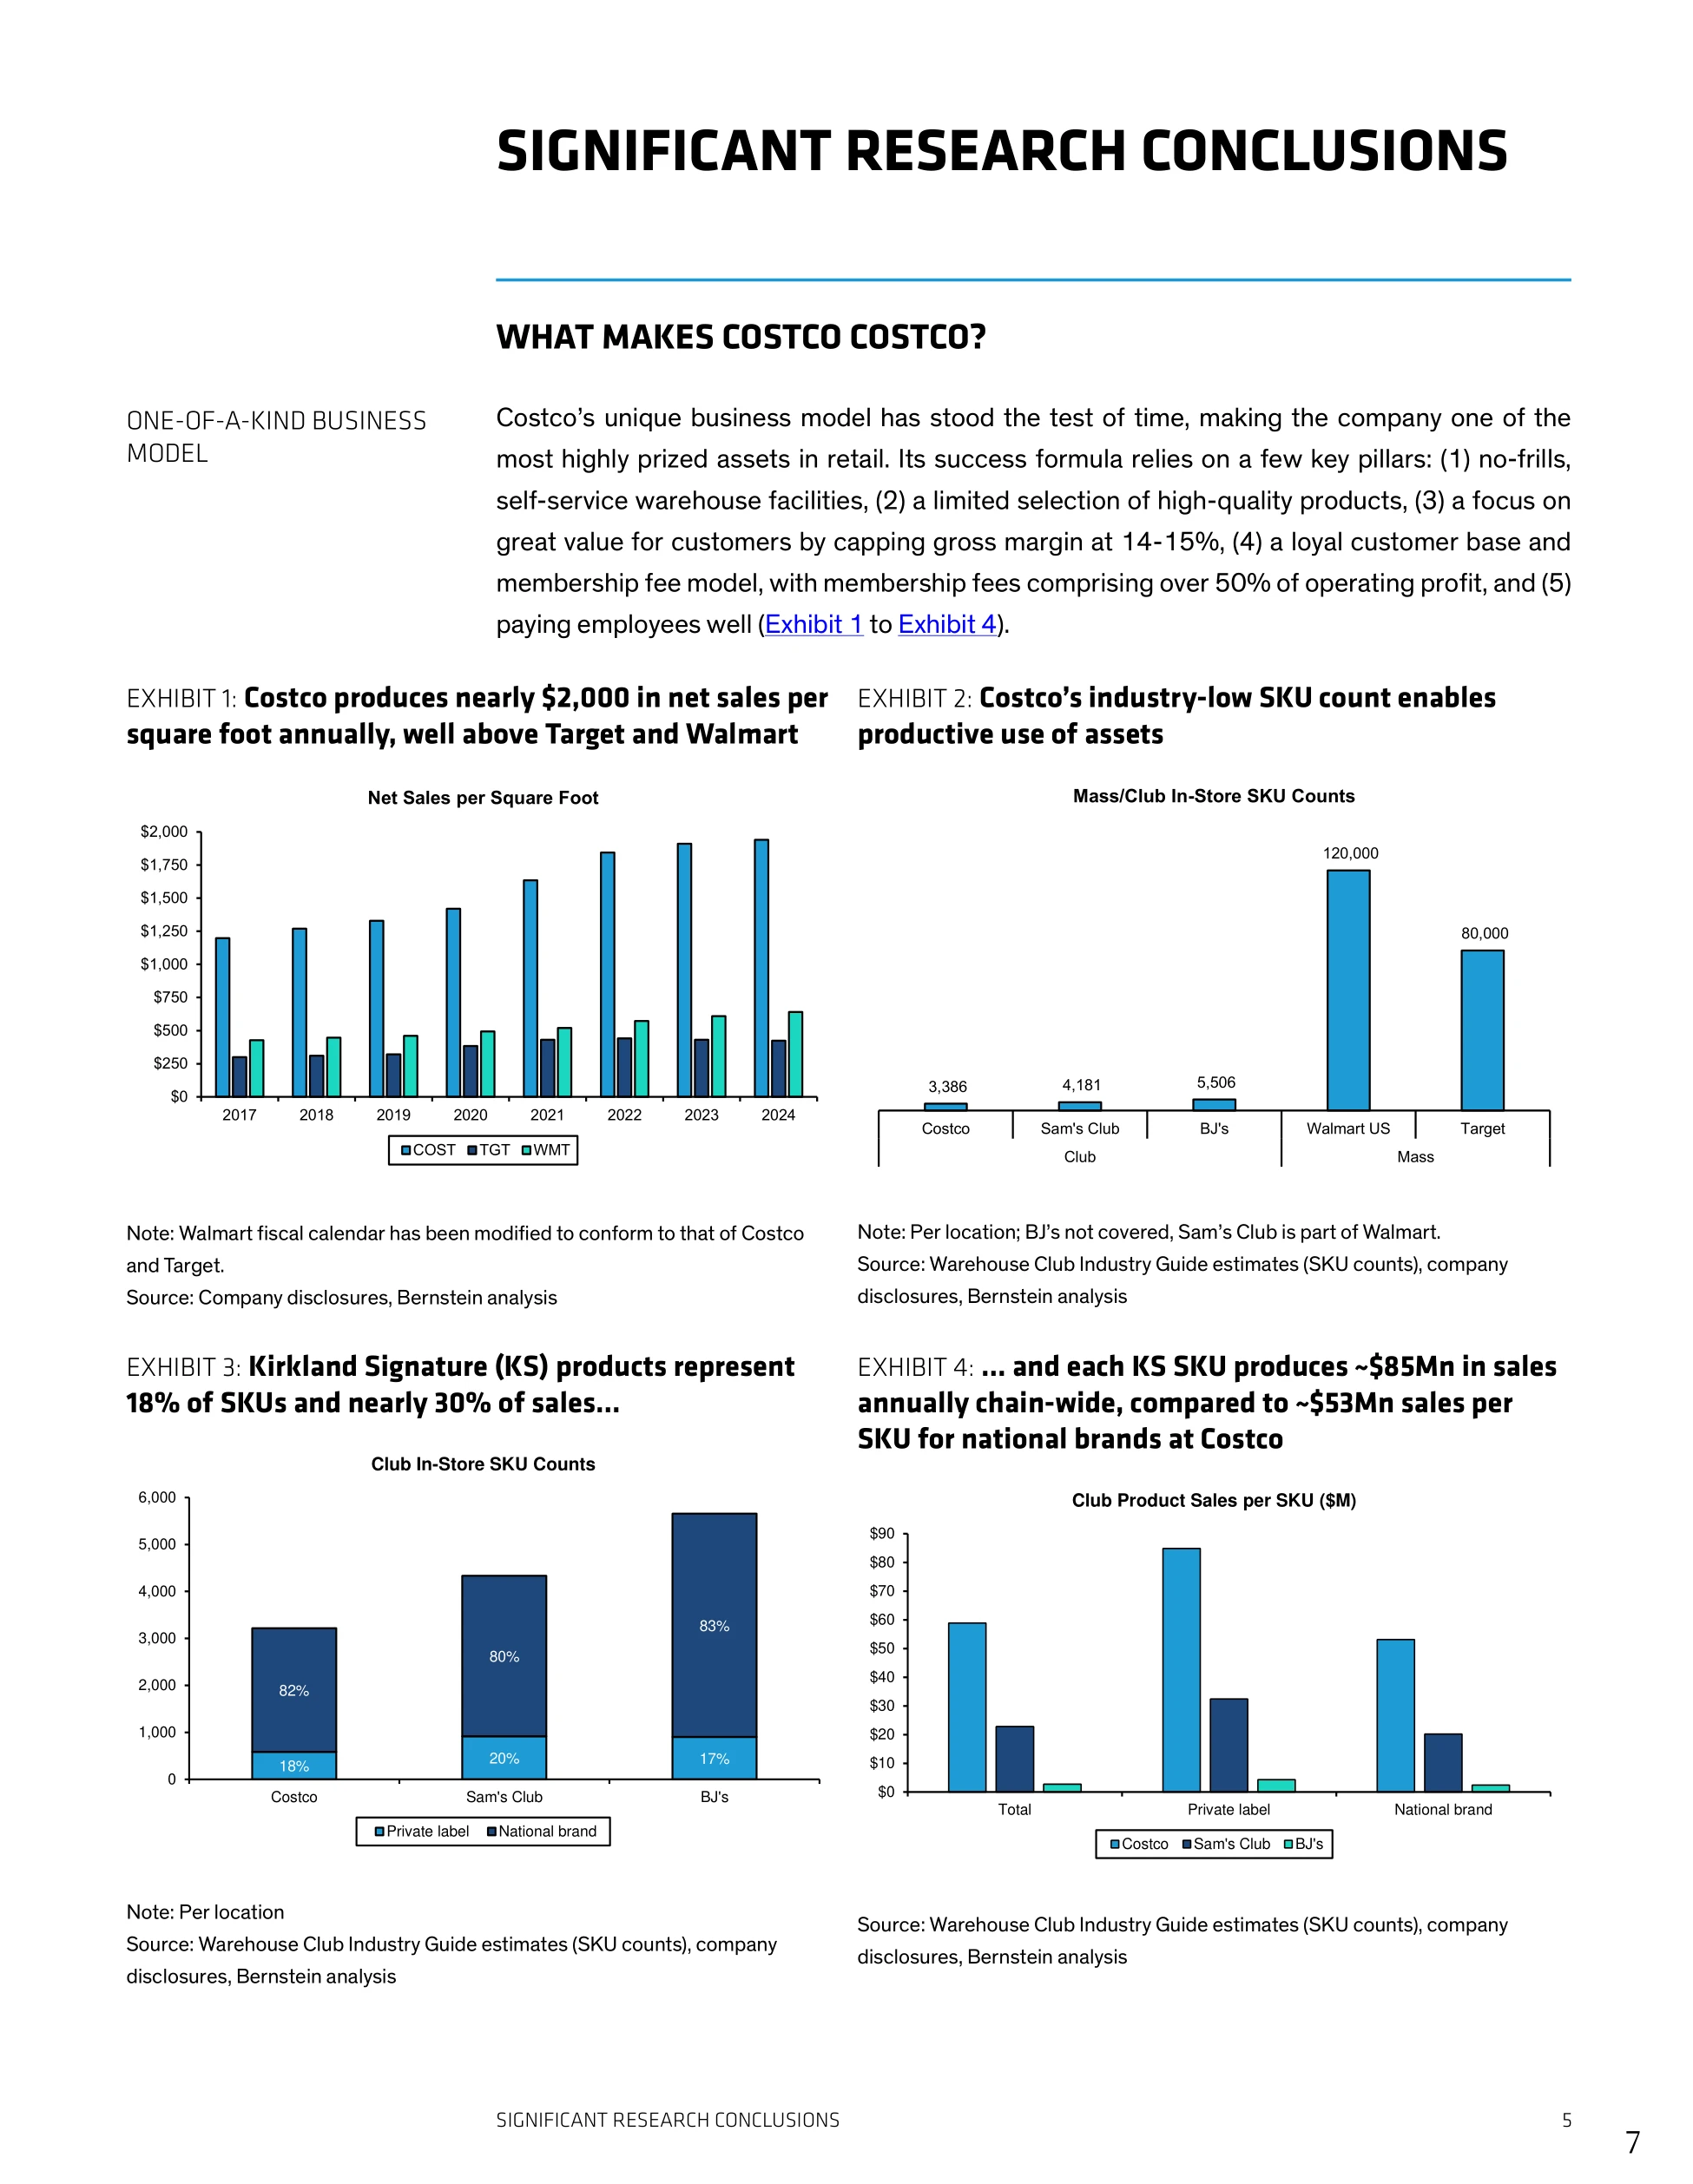
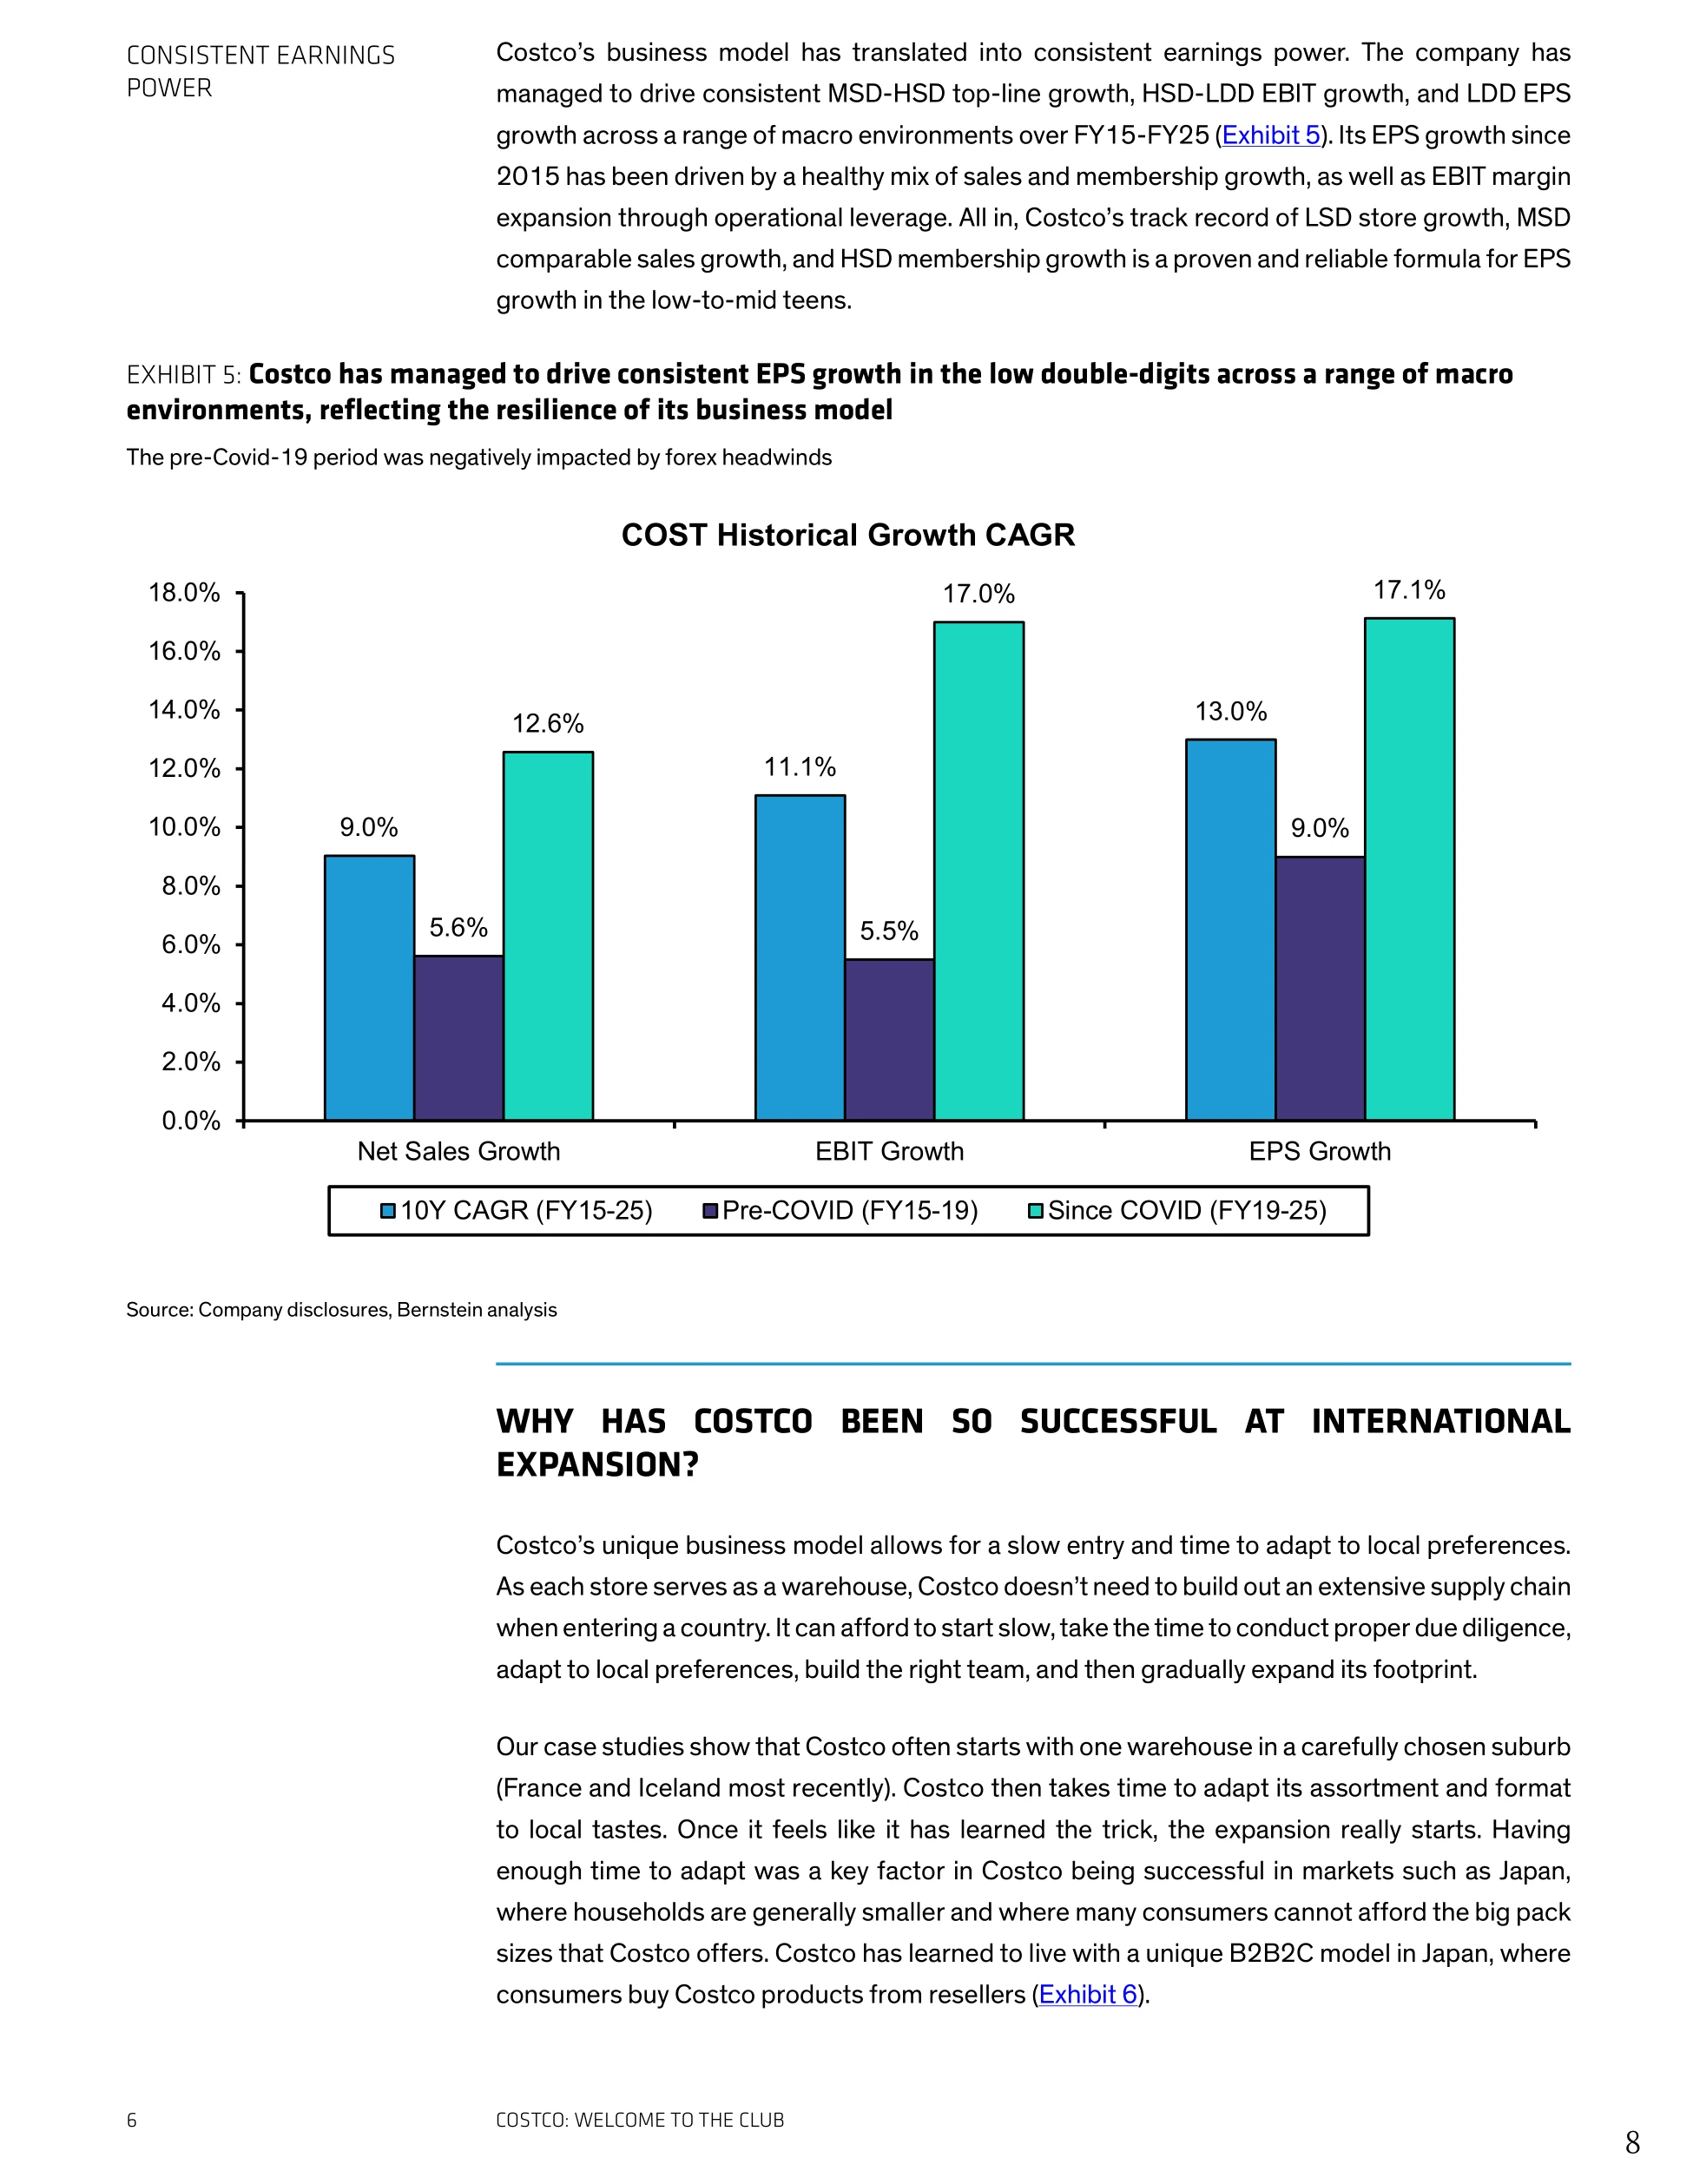
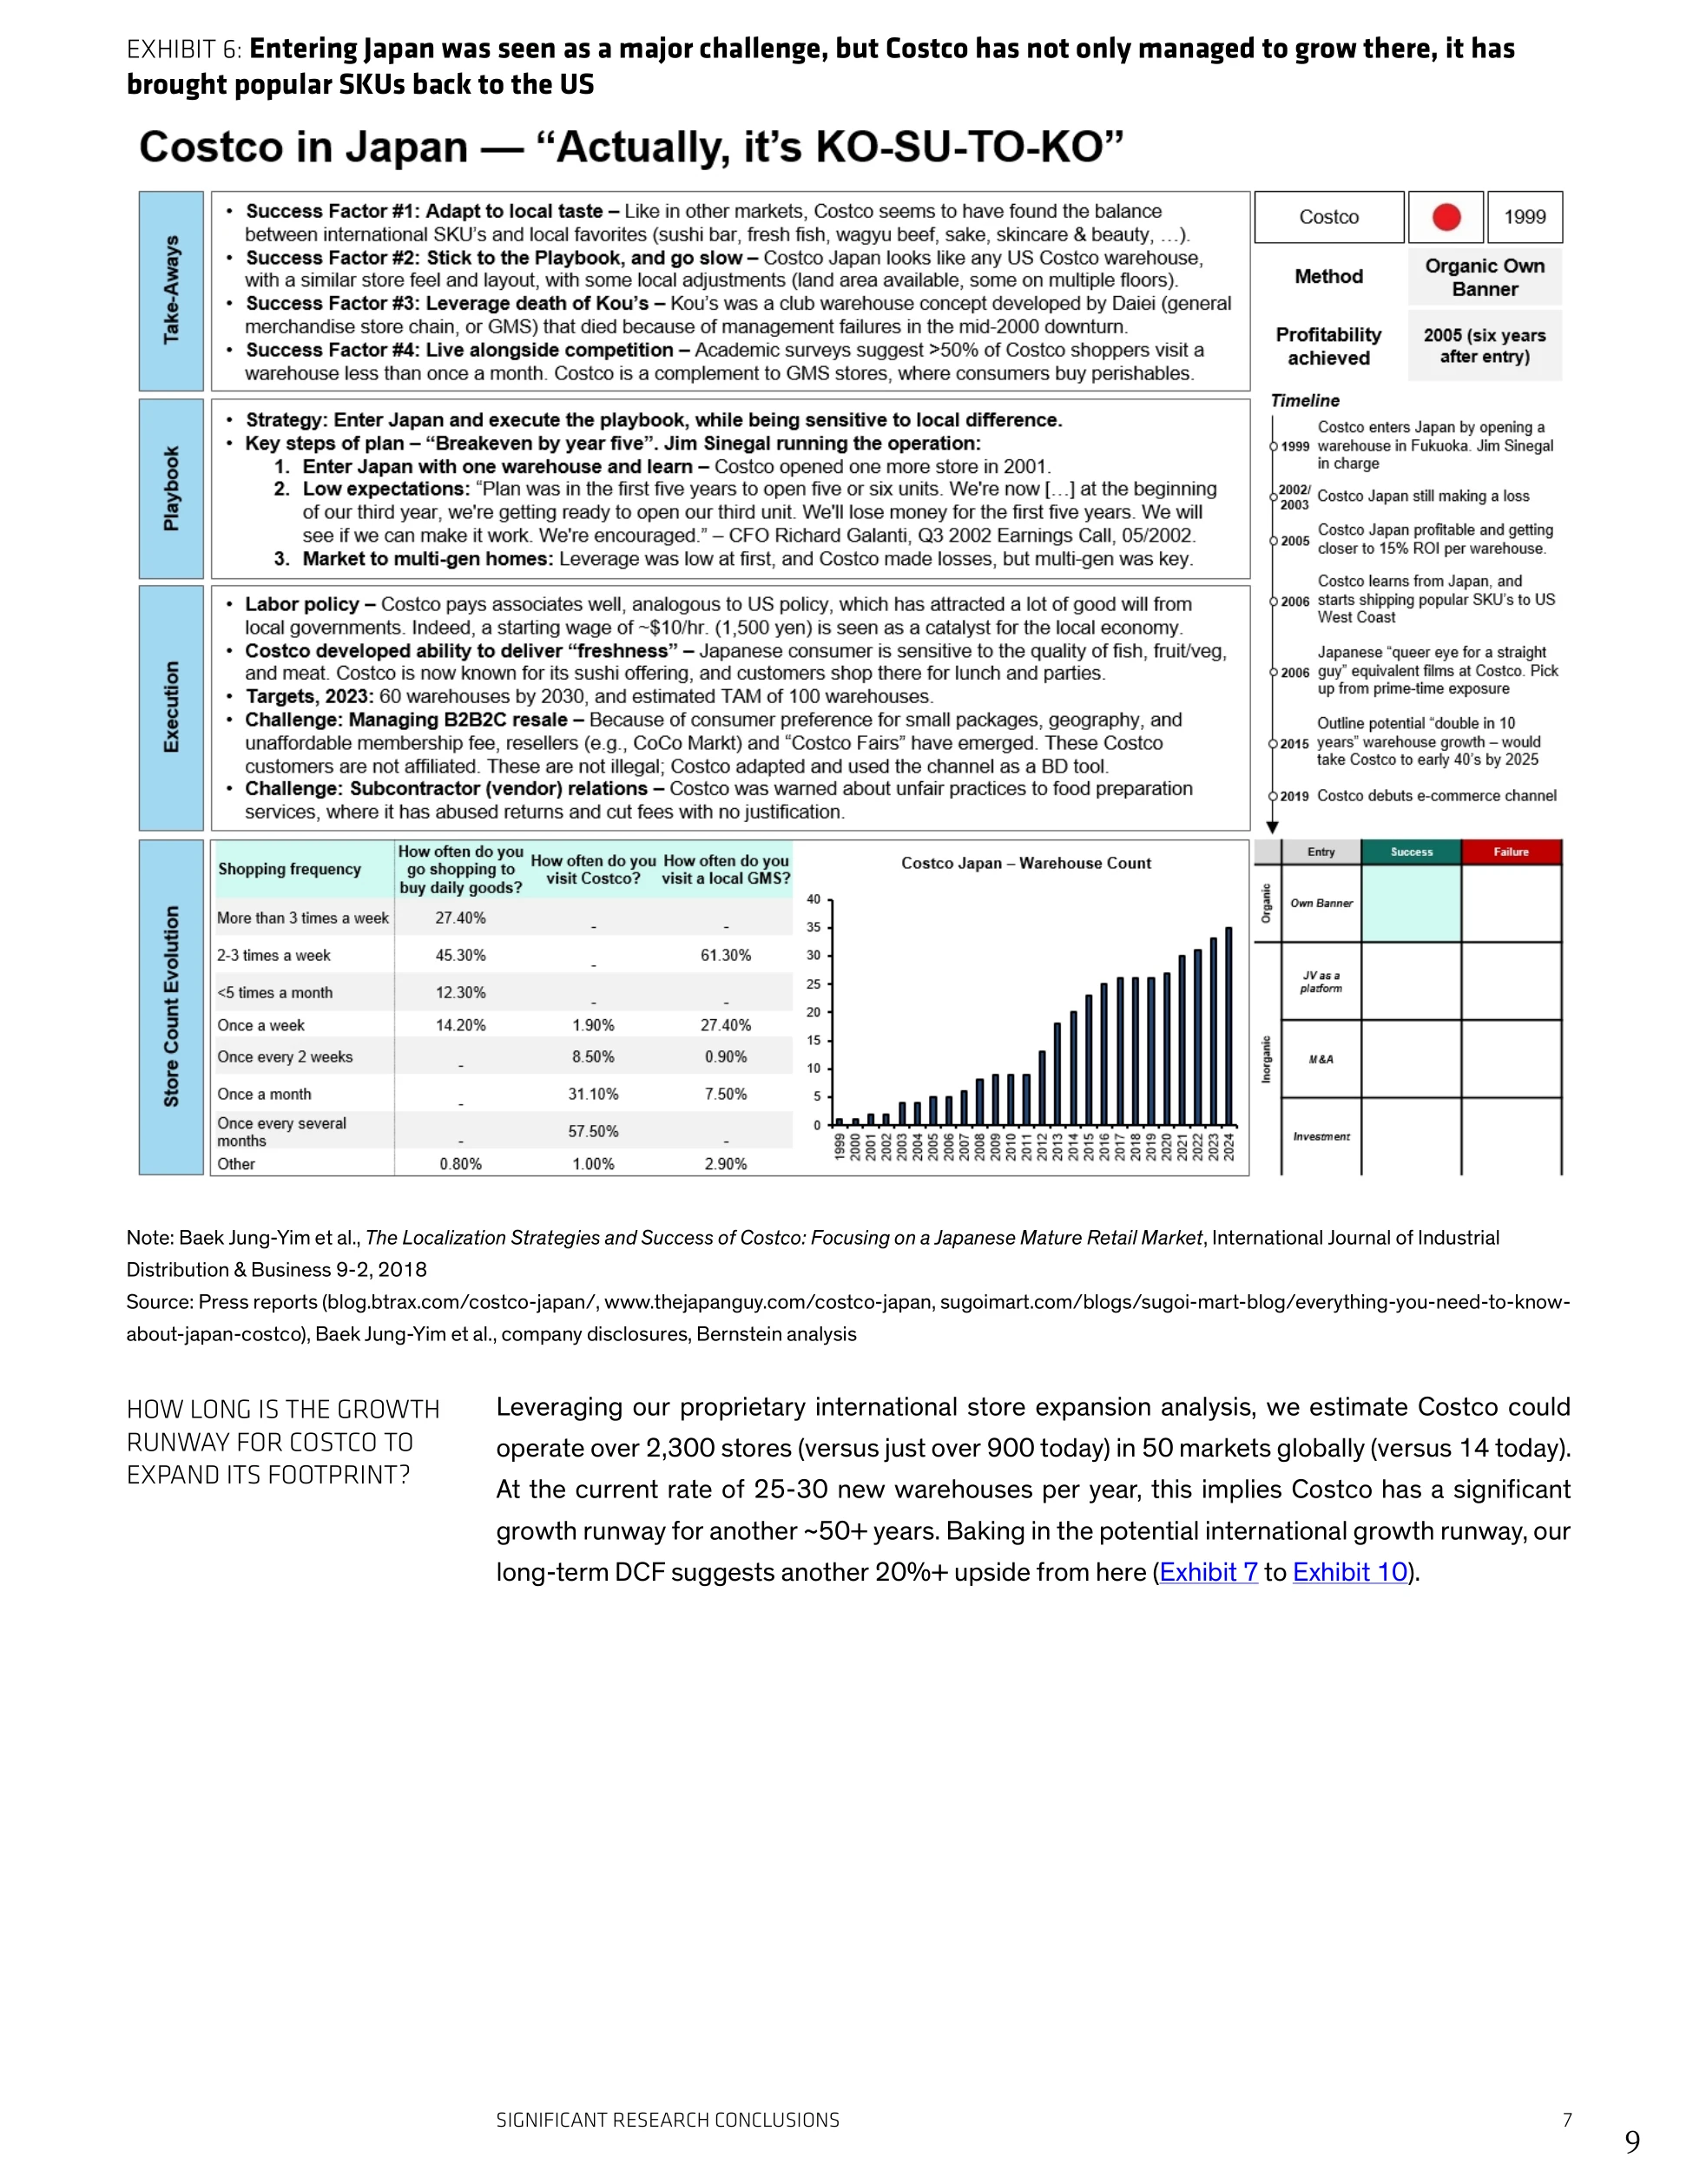
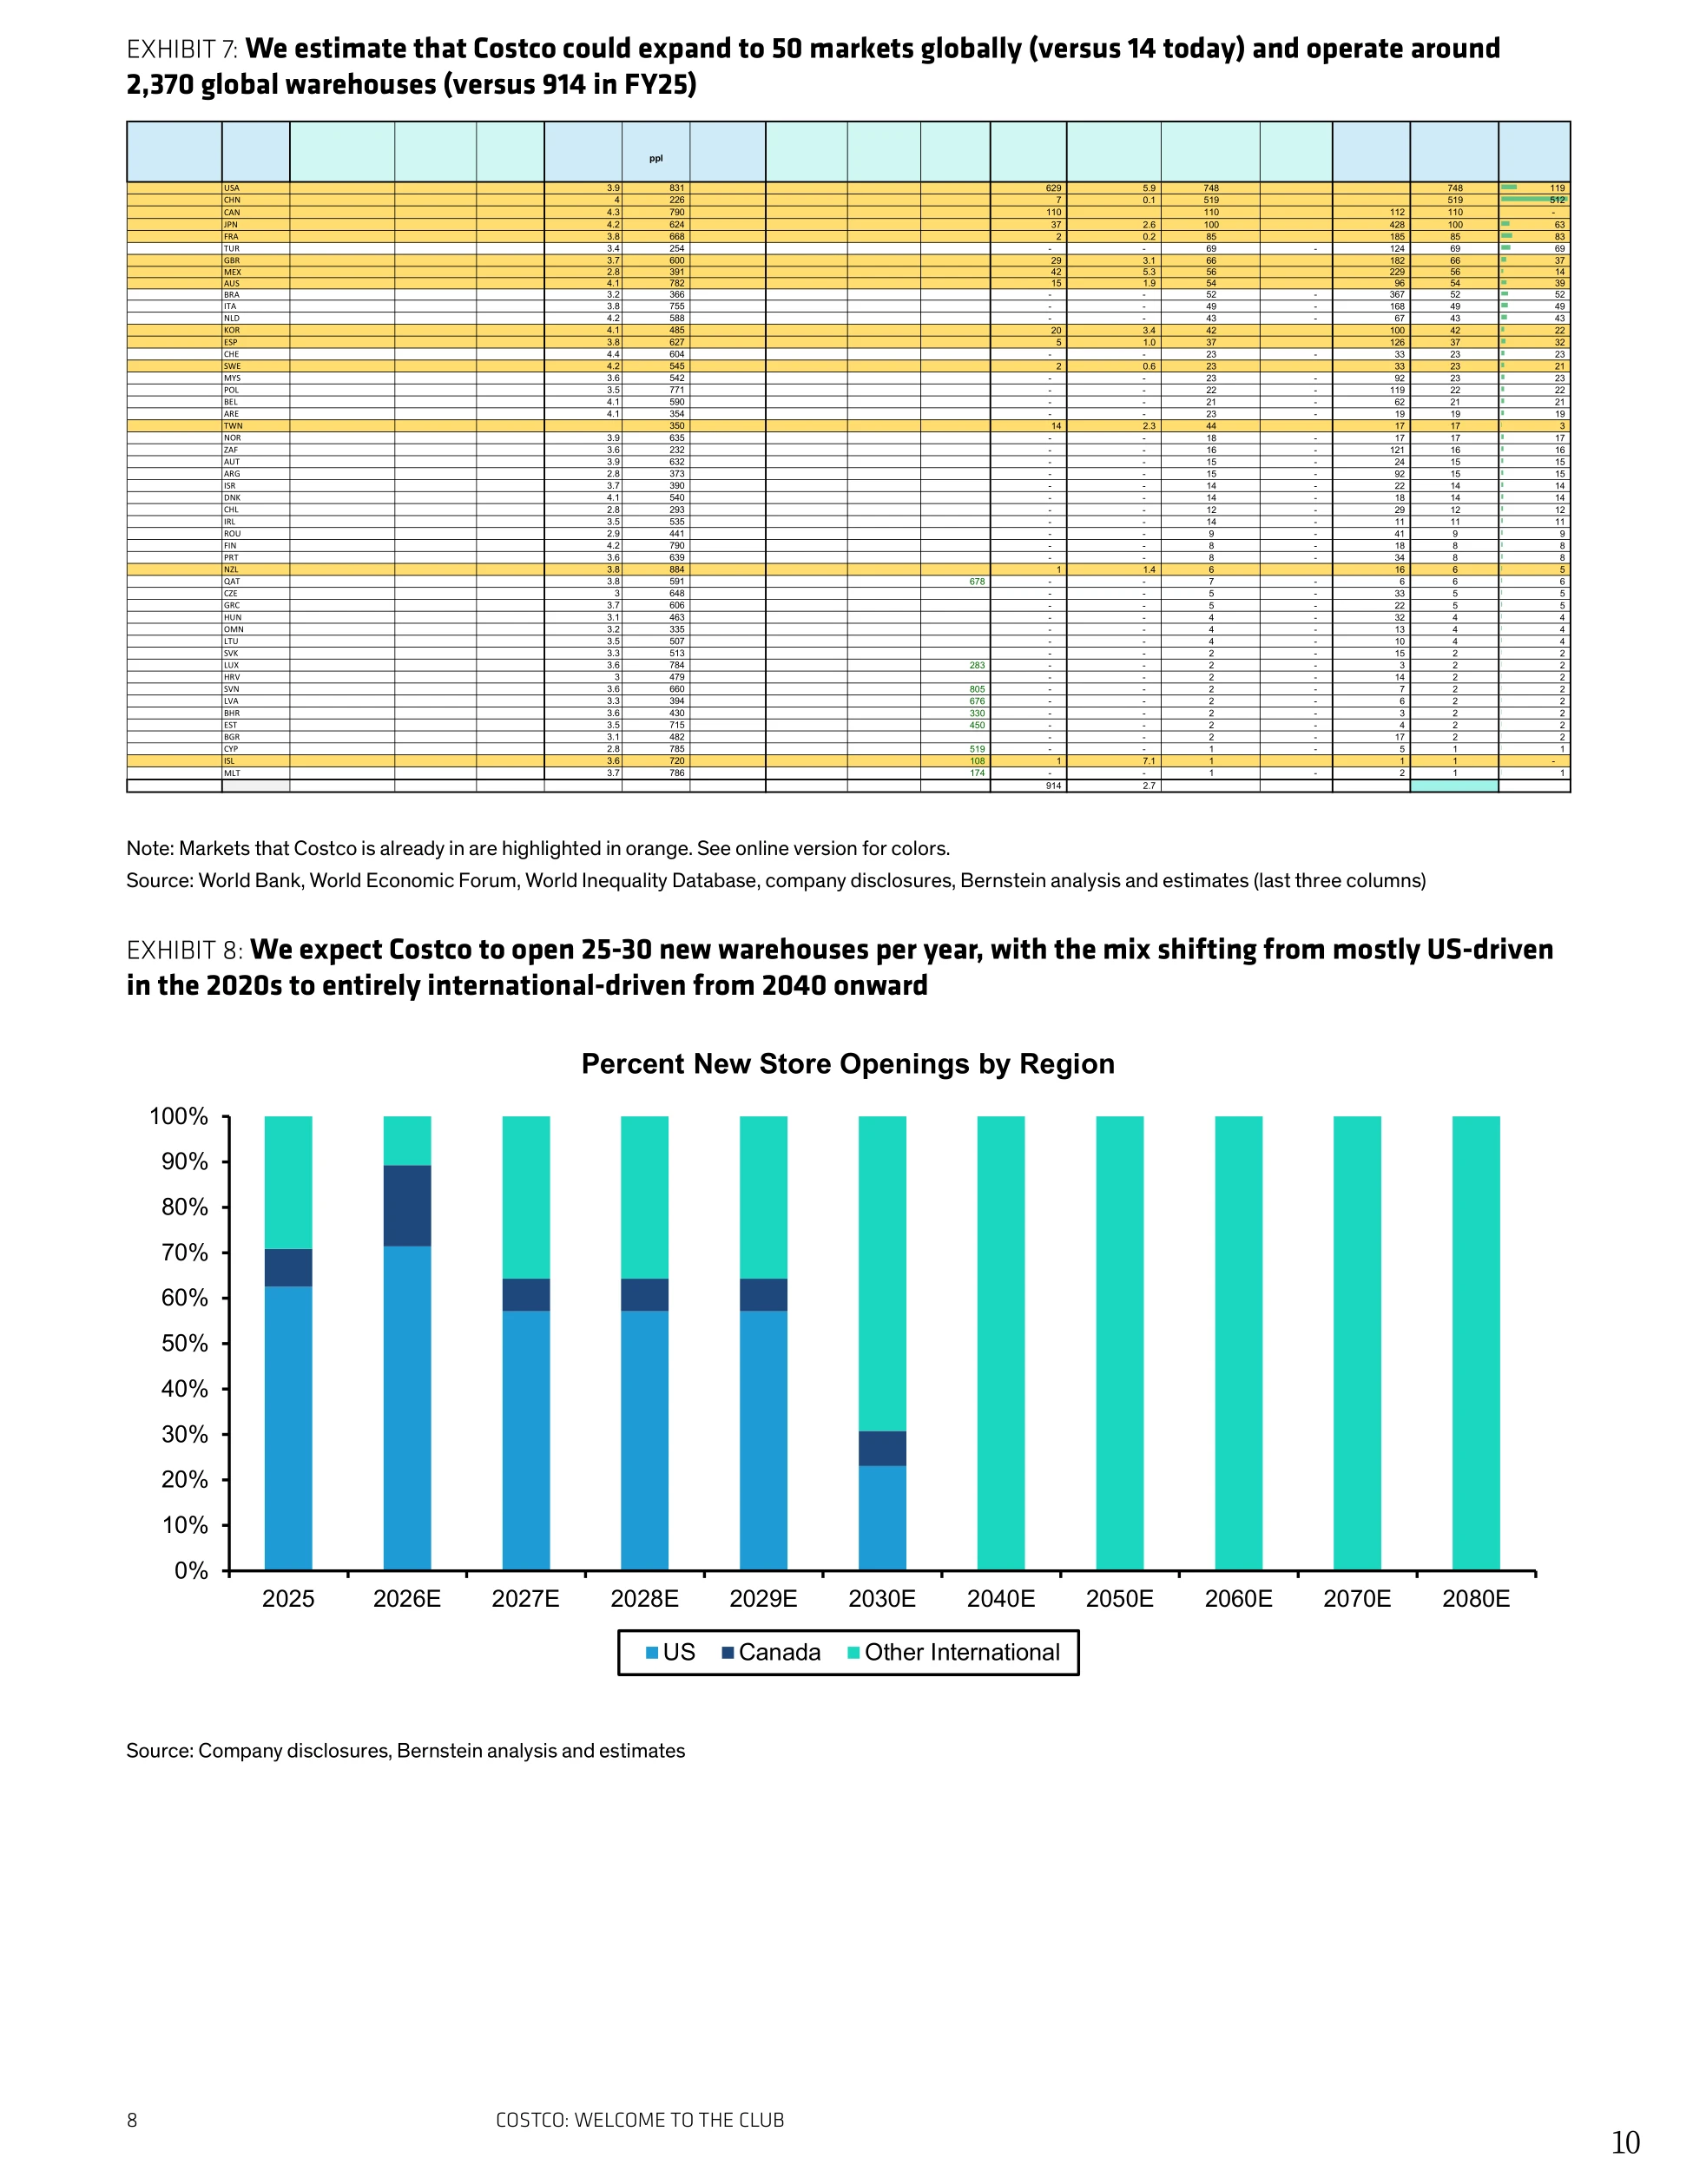
APRIL 2026COSTCO: WELCOME TO THE CLUBConsistent growth for decades to come.Whether you are craving a $1.50 hot dog or wanting to save money on a diamond ring,welcome to the club.Costco’s unique business model is centered around no-frills, self-service warehouses, alimited selection of high-quality products at extreme value, and loyal members. This has stoodthe test of time and translated into consistent earnings power — mid-to-high single-digit top-line growth, high single- to low double-digit EBIT growth, and low double-digit EPS growth.What’s perhaps the most underappreciated factor is Costco’s potential international growthrunway. We estimate that Costco could operate 2,300+ stores (vs. just over 900 today) in 50markets globally (vs. 14 today). At the current rate of 25-30 new warehouses per year, thisimplies Costco has a significant growth runway of another ~50+ years.This potential international growth runway supports Costco’s membership fee income(MFI), which accounts for >50% of EBIT. As the US becomes more saturated, we expectinternational growth to support an MFI CAGR at ~7% over multiple decades.See Disclosure Appendix of this report for important disclosures and analyst certifications1122Zhihan Ma+1 917 344 8303Jeremy Miles+1 917 344 8370April 1, 2026PORTFOLIO MANAGER'S SUMMARYWhether you are craving a $1.50 hot dog or wanting to save money on a diamond ring, welcometo the club.Costco’s business model has stood the test of time, making the company one of the mosthighly prized assets in retail. Its success formula rests on five key pillars: (1) no-frills, self-servicewarehouse facilities, (2) limited selection of high-quality products, (3) focus on value, with cappedgross margins (14-15%), (4) loyal fee-paying memberships, and (5) paying employees well. Thishas translated into consistent earnings power, with mid-to-high single-digit (M/HSD) top-linegrowth, HSD to low double-digit (LDD) EBIT growth, and LDD EPS growth over the past decade.What’s perhaps most underappreciated is Costco’s potential international growth runway. Itsbusiness model helps de-risk expansion. As each store serves as a warehouse, Costco doesn’trequire an extensive supply chain when entering a country. It can start slow, do proper duediligence, adapt to local preferences, build the right team, and then gradually expand its footprint.Leveraging our proprietary international expansion analysis, we estimate Costco could operate2,300+ stores (versus 914 FY25) in 50 markets (versus 14 today). At today’s rate of ~25-30 newwarehouses per year, this implies Costco has a significant growth runway of another ~50+ years.International growth should support Costco’s membership fee income (MFI) growth. The annuity-like MFI stream, worth >50% of EBIT, is key in Costco’s valuation premium. Although Costco hasdomestic growth opportunities, the US is saturated — we estimate that three in...